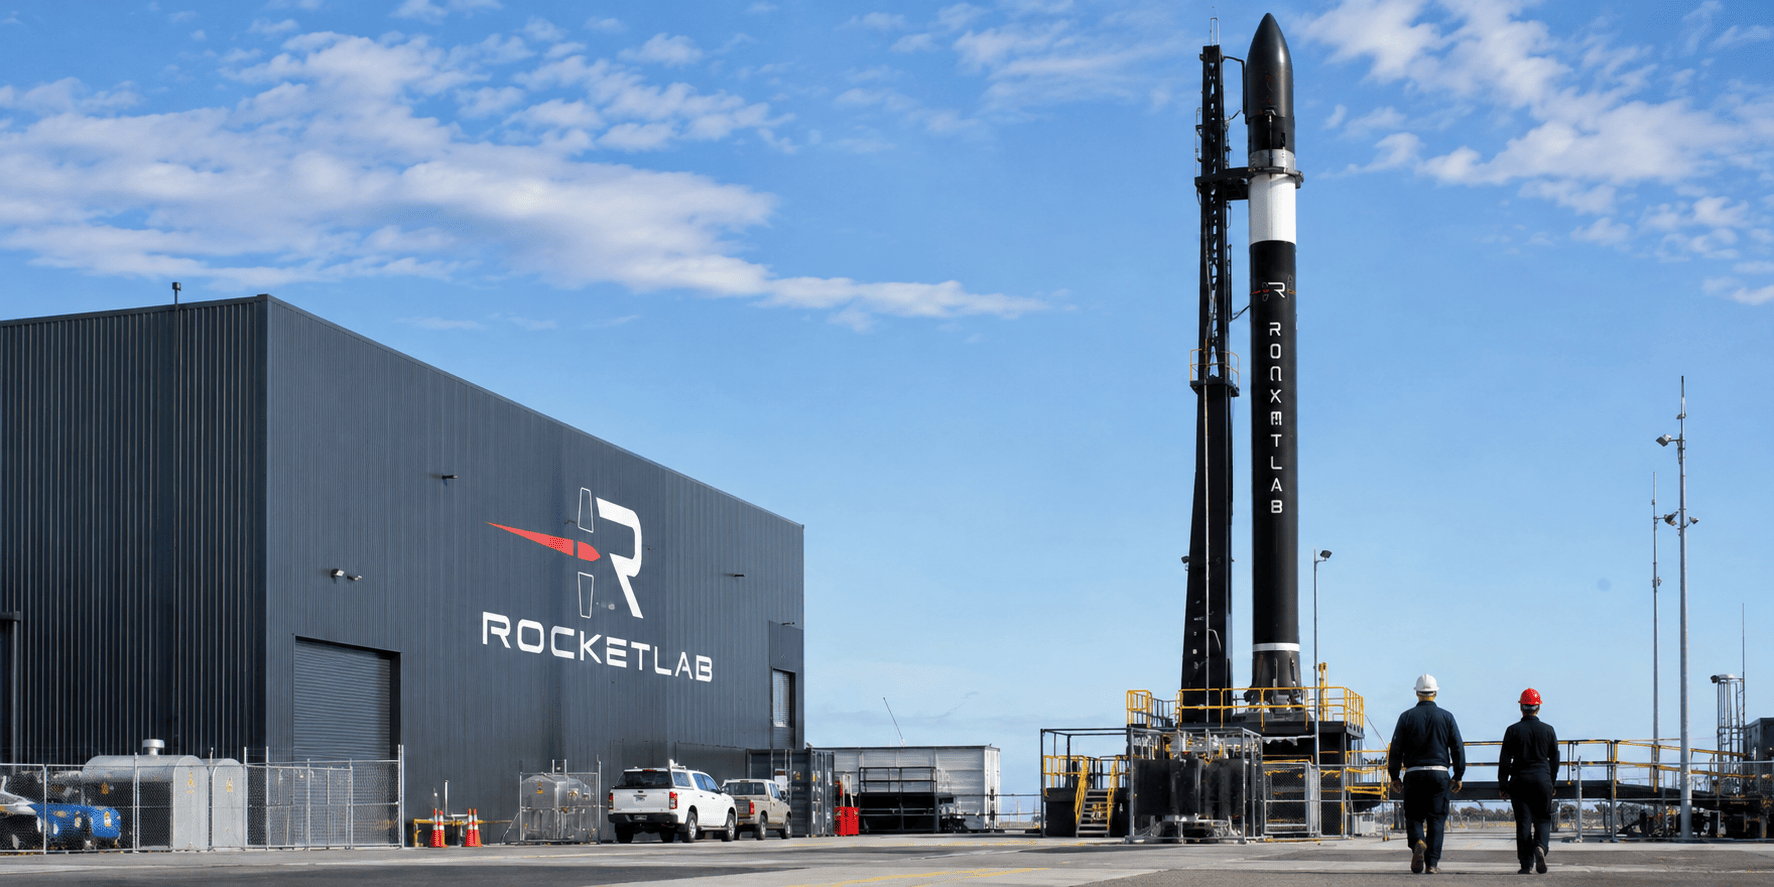
Rocket Lab (NASDAQ: RKLB) is set to release its third-quarter financial results later today, with the stock having already declined sharply in the second half of the year. The shares have dropped to around $53, erasing the gains made in the first six months, as investors await a potential SpaceX IPO and digest delays in the Neutron launch program.
According to consensus estimates from Yahoo Finance, analysts expect Rocket Lab to report revenue of $257 million for the quarter, a 65% year-over-year increase. This growth is attributed to sustained demand for the company's launch and space systems services. The company has a history of beating expectations, which could push its annual revenue past the $1 billion milestone sooner than anticipated.

In the previous quarter, Rocket Lab reported revenue of $234 million, up 62% year-over-year, with a record backlog of $2.36 billion. The backlog is supported by contracts such as a $397 million deal with the U.S. Space Force for multiple satellite spacecraft on Neutron, and a $160 million contract for three geostationary satellites.
The company's recent $8 billion acquisition of Iridium is expected to create a vertically integrated player capable of designing, building, launching, and operating its own satellite constellations. This move positions Rocket Lab to potentially compete with SpaceX's Starlink in the future.
However, the earnings report comes amid a series of analyst downgrades triggered by the delay of the Neutron launch, now expected next year instead of this quarter. Citizens' Trevor Walsh lowered his price target from $130 to $90, KeyCorp's Michael Leshock cut his from $135 to $100, and Bank of America reduced its target from $110 to $100. Conversely, some analysts remain bullish, with Needham reiterating a buy rating and a $120 target, and Citigroup maintaining an outperform rating.
From a technical perspective, RKLB has formed a head-and-shoulders pattern on the daily chart, with a neckline at $58.20. The stock has already retested this neckline, which often confirms a continuation of the downtrend. It remains below the 50-day and 100-day moving averages, suggesting further downside potential. The stock could drop to $44 after earnings, or alternatively, rebound to test resistance at $60.
Investors will be closely watching the earnings call for updates on Neutron's timeline, the Iridium integration, and any changes to full-year guidance. The stock's reaction to the results will likely hinge on these factors, as well as the overall market sentiment toward high-growth space stocks.
This article is for informational purposes only and does not constitute financial advice.

