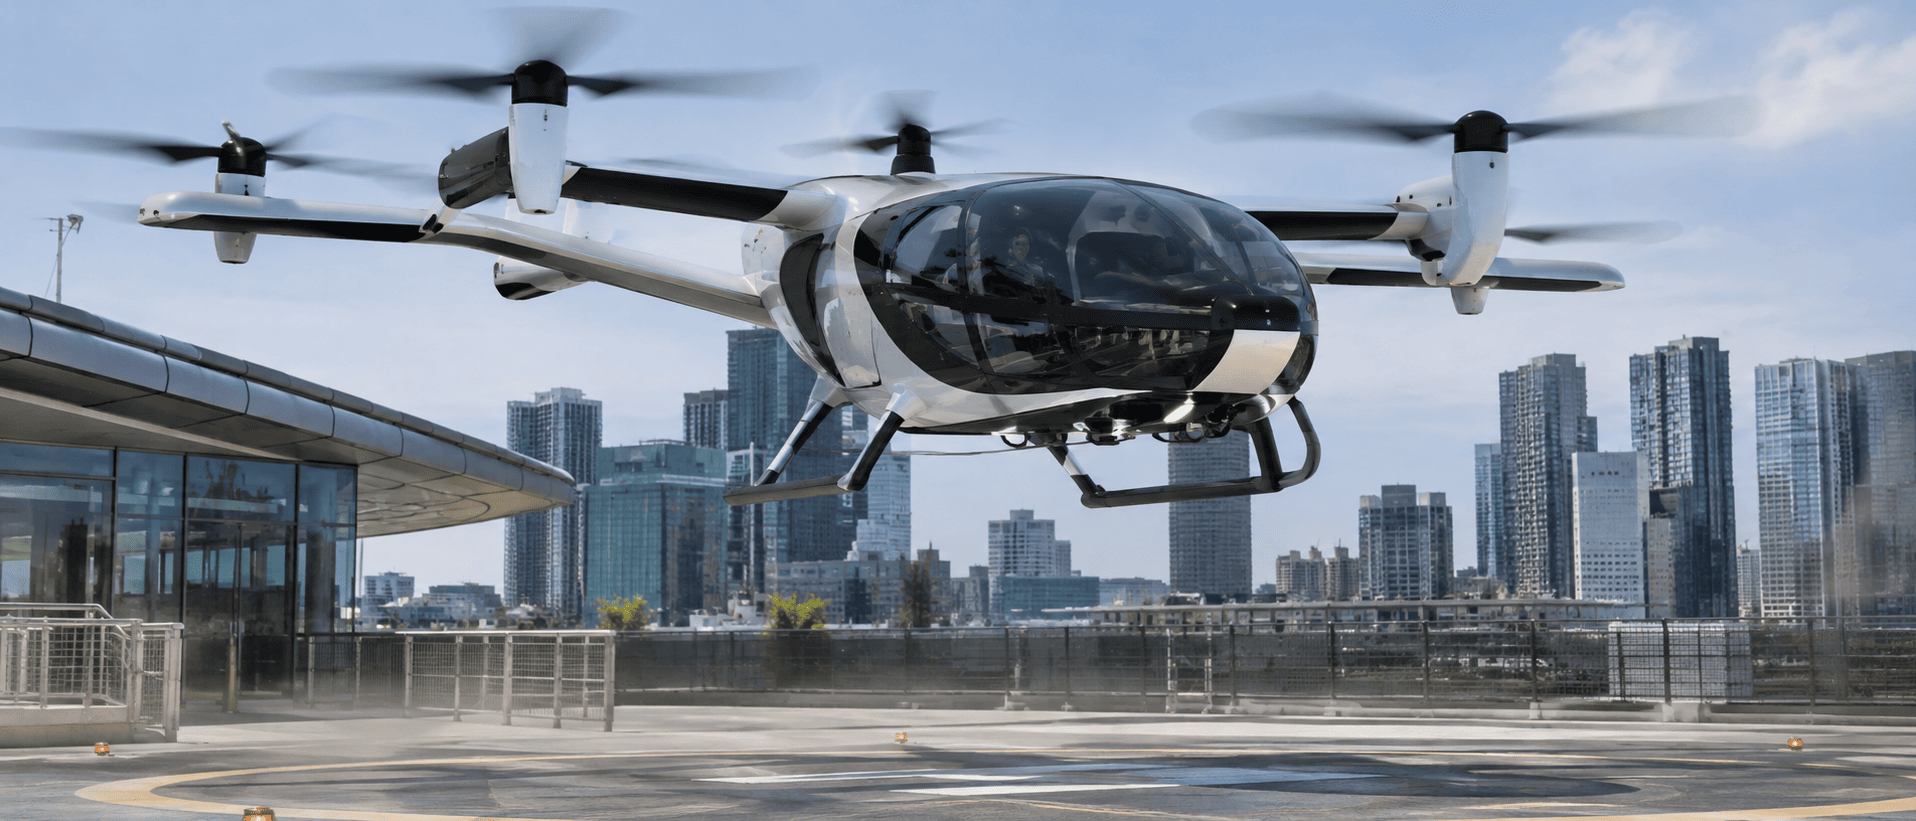
Joby Aviation's shares climbed on Thursday after the electric air taxi developer reported third-quarter results that topped revenue expectations, narrowed losses, and lifted its full-year sales outlook. The company also pointed to advances in FAA certification, a critical step toward launching commercial operations.
However, the market's enthusiasm may be overlooking several red flags embedded in the earnings report. While the headline numbers look encouraging, a closer examination reveals that the core eVTOL business is still far from generating meaningful revenue, and the path to profitability remains steep.

Revenue Quality Raises Questions
Joby reported revenue of approximately $55 million for the quarter, comfortably beating analyst estimates and marking a sharp increase from the prior year. Yet the bulk of that revenue came from Blade, the helicopter ride-sharing service Joby acquired, rather than from its electric vertical takeoff and landing (eVTOL) aircraft operations.
This distinction is crucial for investors. The investment thesis for Joby has always centered on commercializing electric air taxis, not operating a conventional aviation services business. Blade may provide cash flow and customer relationships, but it does not validate the economic viability of Joby's core eVTOL platform.
Despite the revenue beat, Joby still posted a net loss exceeding $200 million for the quarter. Adjusted EBITDA losses remained substantial, indicating that revenue growth alone is not translating into operating leverage. Investors cheering the top-line momentum may be ignoring that the flagship business remains in development, not in commercial deployment.
Certification Progress Is Not Completion
Management highlighted progress in the fifth and final stage of FAA certification, which is undoubtedly a positive development. The company also completed additional for-credit testing and reported that manufacturing output is scaling. These are important milestones for any aerospace firm attempting to bring a new aircraft to market.
However, certification progress should not be confused with certification completion. Joby's own update indicates that parts of the certification process remain unfinished. Aerospace history is replete with examples of programs that seemed close to commercialization only to face unexpected regulatory, engineering, or operational delays.
Moreover, certification is not the end of the road. After approval, Joby must demonstrate reliable fleet operations, scale production, manage maintenance requirements, and build customer demand at commercially attractive economics. The stock market often prices in future success years in advance, and the risk is that investors are valuing Joby shares as though these milestones have already been achieved.
Cash Burn and Dilution Risks
One bullish argument frequently cited by Joby supporters is the company's liquidity position. As of September 30, Joby reported about $2.2 billion in cash, cash equivalents, and short-term investments. On the surface, that provides a comfortable runway.
Yet the other side of the equation deserves attention. Joby used roughly $195 million during the quarter and expects second-half cash usage of between $385 million and $415 million. The company also raised some $128 million through its at-the-market equity program during the quarter, reminding investors that shareholder dilution remains a real possibility if commercialization timelines extend.
In other words, Joby is still consuming capital at a rapid pace while operating in one of the most complex and regulation-intensive industries in the world. The market's initial reaction suggests investors are focusing on what could go right, but long-term shareholders should equally consider what happens if certification takes longer, operating costs remain elevated, or commercial demand develops more slowly than anticipated.
For now, Joby's story remains compelling, but the gap between current progress and large-scale commercial operations is still wide.
This article is for informational purposes only and does not constitute financial advice.

