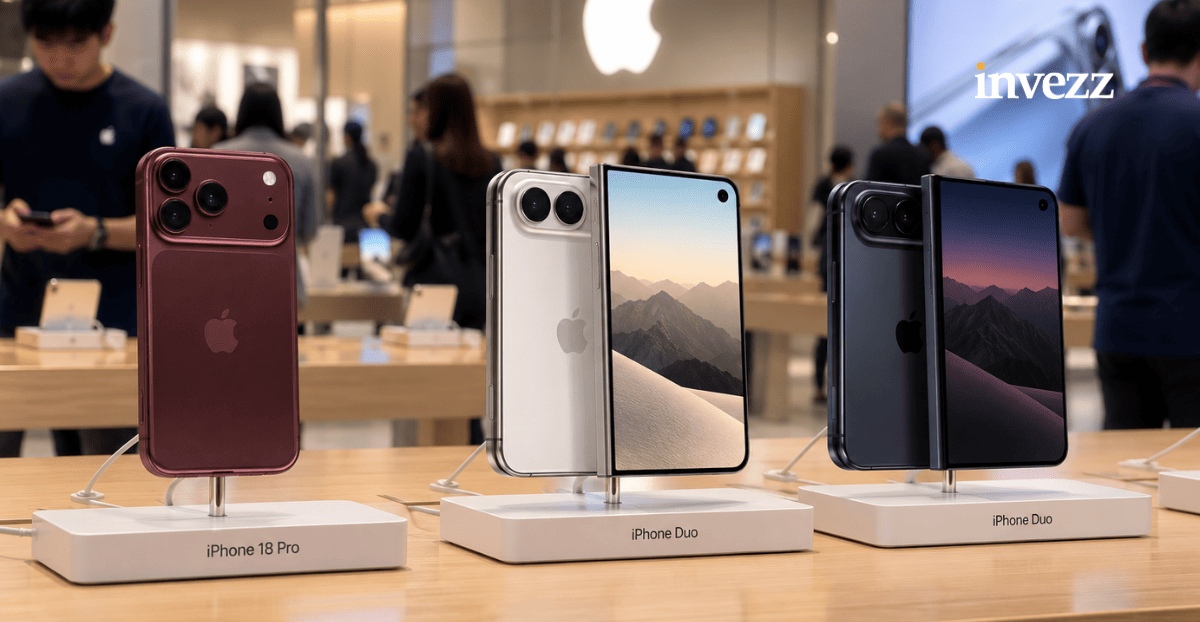
Apple shares advanced 1.6% on Wednesday after China Renaissance upgraded the stock to Buy from Hold and lifted its price target to $425 from $280, citing the growth potential of the company's first foldable iPhone. The new target implies roughly 22% upside from Tuesday's closing price of $348.51.
Analysts Jack Zhou and Lemuel Lin said the iPhone Duo, launched in October, has shifted their outlook on the company. They believe the device could reshape the iPhone replacement cycle and create a new growth platform, helping offset pressures from higher memory costs and slower services growth.

China Renaissance Sees New Growth Cycle
The analysts noted that their previous Hold rating reflected concerns about memory chip-driven margin pressure and slowing services growth. However, they now view the foldable device as a potential catalyst for a longer period of expansion.
“We view Duo as a new growth platform with the potential to reshape the iPhone replacement cycle,” Zhou and Lin wrote in their research note. They added that the combination of a foldable display, multitasking capabilities, and Siri AI could introduce new use cases for the iPhone, supporting productivity, content consumption, and AI-assisted workflows, thereby incentivizing upgrades.
Initial reactions to Apple's first foldable phone have been mixed, with enthusiasm about the hardware tempered by concerns over software limitations and durability. Some users have reported creasing or breakage of the inner screen. Despite these issues, China Renaissance believes the Duo could usher in a new decade of growth for Apple by driving smartphone sales and upgrades, potentially offsetting near-term business pressures.
Memory Costs Remain a Margin Concern
Apple continues to face rising memory costs as demand for AI infrastructure chips pressures supply and prices. The company recently projected that its fiscal first-quarter 2027 gross margin would decline sequentially by 1.4 percentage points to between 45% and 46%, excluding tariff refunds. China Renaissance acknowledged that memory inflation and weaker services growth could weigh on near-term earnings, but said pricing actions and lower costs for non-memory components should provide some relief, while the iPhone Duo offers longer-term upside.
Wall Street Remains Broadly Positive
The upgrade adds to a generally favorable analyst outlook on Apple. Of the 48 firms tracked by FactSet, the stock carries an average Overweight rating (equivalent to Buy), with only four Sell ratings and two Underweight ratings. Morgan Stanley analyst Erik Woodring also has an Overweight rating with a $350 price target. Following Apple's fiscal fourth-quarter results, he flagged slower services growth and potential gross margin pressure as concerns, but argued that Apple's free cash flow and its reluctance to spend heavily on AI could appeal to investors seeking stability amid uncertainty in the broader AI trade.
Recent checks from other investment banks present a mixed picture of demand for the Duo. UBS reported that its tracking across more than 30 geographies showed average delivery wait times falling by two days for the Pro and seven days for both the Pro Max and Duo. JPMorgan, which reiterated its Overweight rating on Monday, saw no material change in quoted delivery dates for the Duo, with availability extending into late January and no in-store pickup option.
With only a handful of Sell ratings among 48 firms, Apple remains a staple holding for many investors on top investment platforms.
This article is for informational purposes only and does not constitute financial advice.