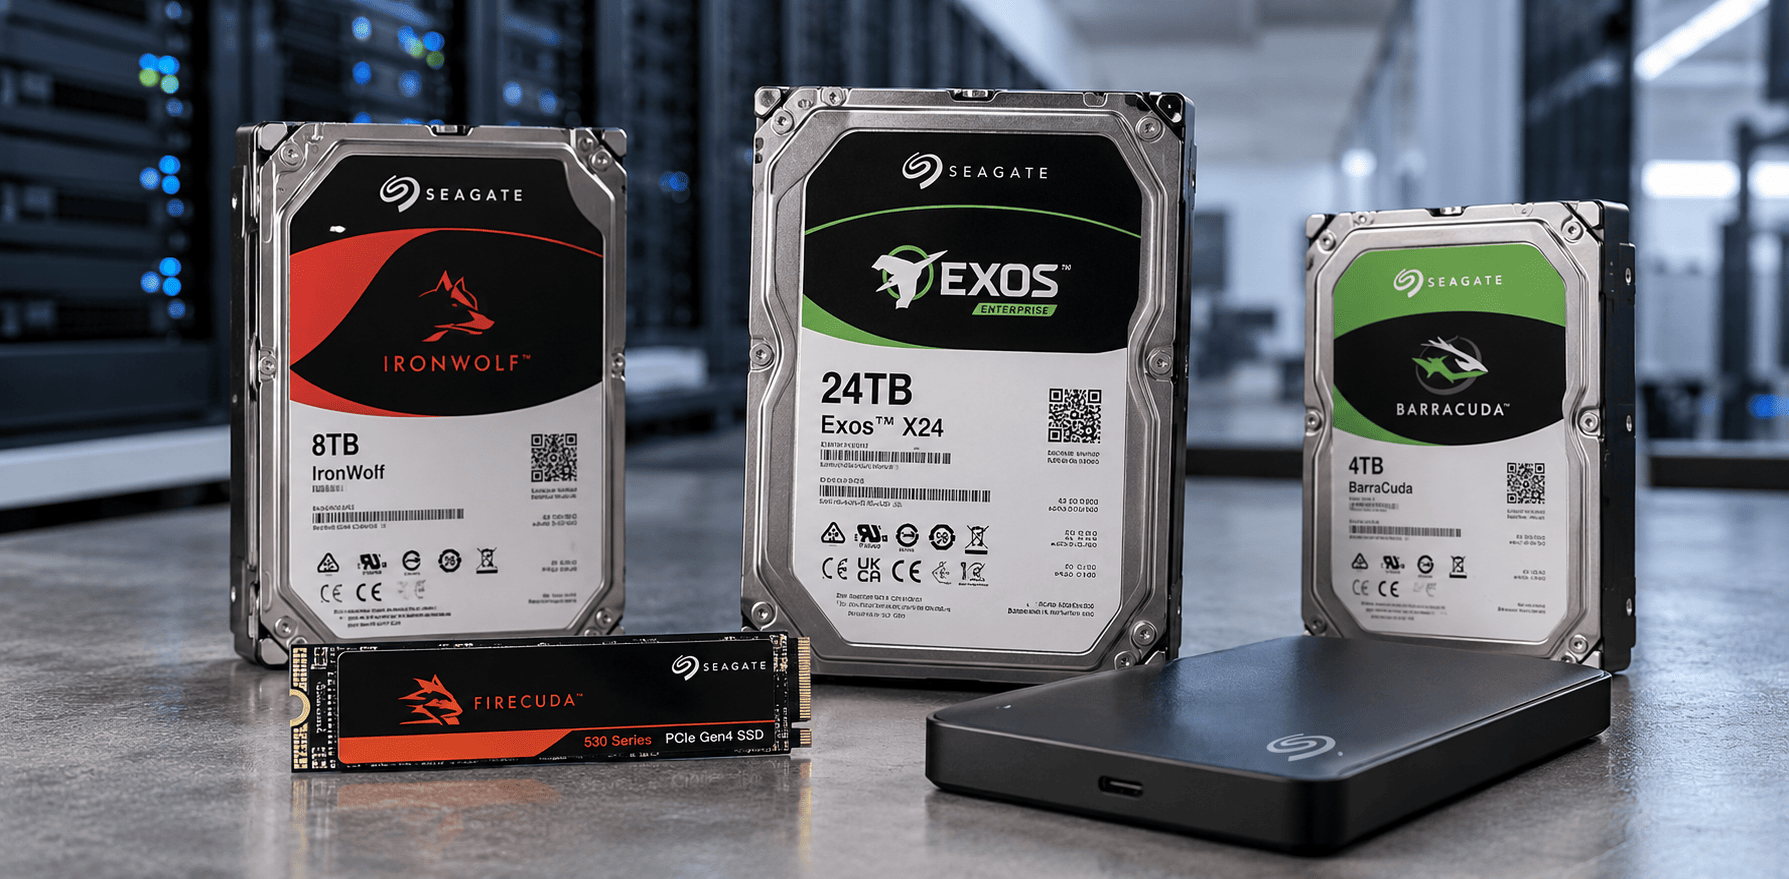
Seagate Technology Holdings plc (NASDAQ: STX) saw its shares decline approximately 2% in premarket trading on Wednesday, even after the data-storage company reported fiscal first-quarter results that surpassed analyst expectations and provided a robust outlook for the current quarter. The pullback comes on the heels of a remarkable 132% surge in the stock year-to-date, prompting some investors to lock in profits.
For the September quarter, Seagate posted revenue of $4.23 billion, exceeding the consensus estimate of $4.15 billion. Adjusted earnings per share came in at $7.68, above the anticipated $7.45. The company also guided for December-quarter revenue of approximately $4.8 billion and EPS of $9.20, both ahead of Wall Street's projections of $4.55 billion and $8.66, respectively. That revenue guidance implies a year-over-year growth of about 70% and a sequential increase of 13%.
Gross margin for the quarter stood at 57.8%, while cash flow from operations reached $1.7 billion and free cash flow totaled $1.5 billion. CEO Dave Mosley highlighted the company's record profitability and free cash flow, attributing the strength to a robust demand environment driven by data creation, retention, and reuse. He emphasized that the company's HAMR-based technology roadmap positions it to capitalize on growing exabyte demand while maintaining supply discipline.
Despite the positive earnings and guidance, the market reaction was muted, with shares slipping in premarket trading. Analysts pointed to a moderation in shipment growth as a key concern. Wedbush Securities analyst Matt Bryson noted that while the previous quarter saw exceptionally strong shipment growth, the fiscal first quarter did not match that pace. He also flagged that the implied gross margin guidance of around 60% suggests a slowdown in margin expansion.
Bryson characterized the slowdown as cyclical, following an unusually strong prior quarter. He added that the market's reaction could also reflect a "sell-the-news" pattern, as investors had already priced in a strong earnings report. The stock's recent rally, which has seen shares more than double this year, may have prompted profit-taking.
Despite the near-term weakness, analysts remain bullish on Seagate's longer-term prospects. Evercore ISI reiterated its Outperform rating and a $1,000 price target, implying roughly 50% upside from Tuesday's closing price. Baird raised its price target to $1,350 from $1,080, also maintaining an Outperform rating, and suggested the stock's decline was tied to a one-quarter slowdown in exabyte growth due to a product transition, with growth expected to reaccelerate in the December quarter.
Baird also noted that Seagate's December-quarter guidance would mark the fourth consecutive quarter of year-over-year gross-margin gains exceeding those of its competitor. The firm cited widening supply-demand imbalances and exabyte growth driven solely by higher storage densities as additional reasons for optimism.
Morgan Stanley analyst Erik Woodring recently raised his price target on Seagate to $1,200 from $1,187, drawing parallels between the hard-drive market and the memory market a year ago, before AI-driven demand fueled substantial gains in memory stocks. The firm's industry checks point to a potential supply shortfall of around 400 exabytes in 2027 and 2028, and spot hard-drive transactions are reportedly trading at prices two to five times higher than contracted levels, which could support margins and earnings.
Seagate's stock performance on Wednesday underscores the market's focus on growth sustainability, even as the company delivers strong financial results. The AI infrastructure boom continues to drive demand for data storage, but investors are closely watching how shipment trends and margin dynamics evolve in the coming quarters.
This article is for informational purposes only and does not constitute financial advice.