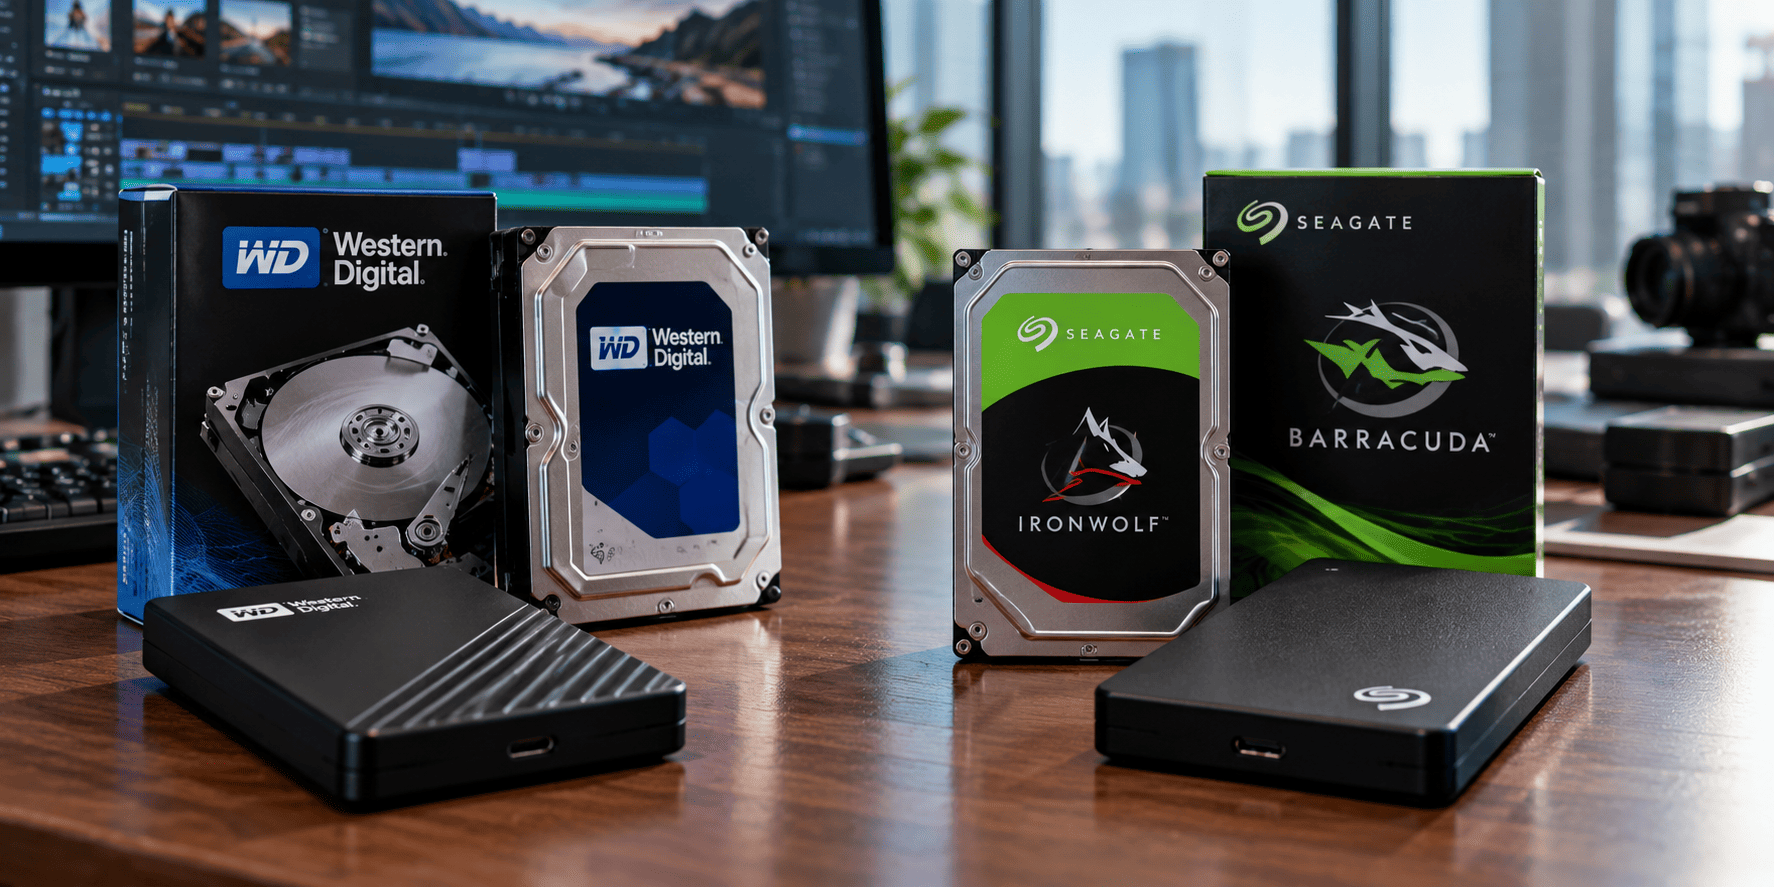
Seagate Technology Holdings (NASDAQ: STX) saw its shares advance more than 4% in Tuesday's trading session, as market participants positioned ahead of the company's fiscal first-quarter 2027 earnings release, scheduled for after the market close. The report is expected to provide critical updates on data-center storage demand, pricing dynamics, and management's outlook for the coming quarters.
The earnings come at a pivotal time for the hard-disk-drive (HDD) manufacturer, which has benefited from robust demand for high-capacity storage solutions driven by artificial intelligence (AI) workloads. Despite this tailwind, Seagate's stock has retreated approximately 40% from its record closing high set on June 22, 2026, reflecting broader market volatility and sector-specific concerns. Over the past year, however, shares remain up nearly 200%, trading at $675.18 as of Tuesday's close.
Analyst Adjustments Ahead of Results
In the lead-up to the earnings announcement, several financial institutions have revised their price targets for Seagate. Rosenblatt Securities lowered its target to $1,100 from $1,400, while maintaining a Buy rating. Analyst Kevin Cassidy attributed the reduction to sector-wide valuation multiple compression, though he noted that Seagate's near-term earnings-per-share upside is more pronounced as its heat-assisted magnetic recording (HAMR) technology scales. HAMR enables higher data density on hard drives, positioning the company to meet growing cloud storage requirements.
Conversely, Morgan Stanley raised its price target to $1,200 from $1,187 last week, reaffirming an Overweight rating and reinstating Seagate on its Top Picks list. The firm cited improving HDD fundamentals and a broadening customer base as key drivers. Bank of America also increased its target to $1,200 from $1,150, reiterating a Buy rating. Analyst Wamsi Mohan expects Seagate to raise prices as its build-to-order contracts for nearline hard drives come up for renewal, with margins and pricing expected to expand well into 2028.
According to FactSet, 83% of analysts covering Seagate rate it the equivalent of a Buy, with an average price target above $1,100.
Earnings Expectations: Revenue and EPS Growth
Wall Street anticipates Seagate's fiscal first-quarter revenue to rise approximately 58% year-over-year to $4.15 billion, based on Koyfin data. Adjusted earnings per share are projected to increase 185% to $7.43, compared with $2.61 in the prior-year period. These forecasts align closely with the company's July guidance, which called for revenue of $4.1 billion (plus or minus $100 million) and non-GAAP EPS of $7.30 (plus or minus $0.20).
In the previous quarter, Seagate reported revenue of $3.63 billion and adjusted EPS of $5.71, supported by strong demand from cloud data centers. The upcoming report will provide investors with clarity on whether the company is tracking to its targets as AI applications continue to drive demand for high-capacity storage.
AI Demand and Supply Dynamics
Seagate and Western Digital are the only US-based HDD manufacturers, and both have capitalized on tight supply conditions by securing long-term customer contracts at favorable margins. AI applications generate and process vast amounts of data, fueling demand for storage infrastructure. However, the industry remains sensitive to shifts in supply and demand. Western Digital recently beat earnings expectations, but its shares declined afterward due to concerns about rising capital expenditure and the potential for additional HDD supply. Seagate's stock also came under pressure earlier this month following reports that Japan's Toshiba planned to increase production capacity, raising investor worries about a possible easing of supply constraints.
Seagate CEO Dave Mosley has previously stated that the company expects continued growth in demand for high-capacity storage as AI applications produce ever-increasing volumes of data.
This article is for informational purposes only and does not constitute financial advice.