Modine Manufacturing (NYSE:MOD) shares surged nearly 29% in after-hours trading on Thursday following reports that Samsung Electronics is in discussions to acquire the U.S. data-center cooling specialist. The stock climbed to $136.90 after the regular session closed at $106.10.
Bloomberg reported that talks could yield an agreement within weeks, though no offer price has been disclosed and negotiations may still collapse. The potential deal underscores how the artificial intelligence boom is funneling investment beyond semiconductor chips into the infrastructure needed to keep powerful servers cool.
Samsung's Strategic Move into AI Cooling
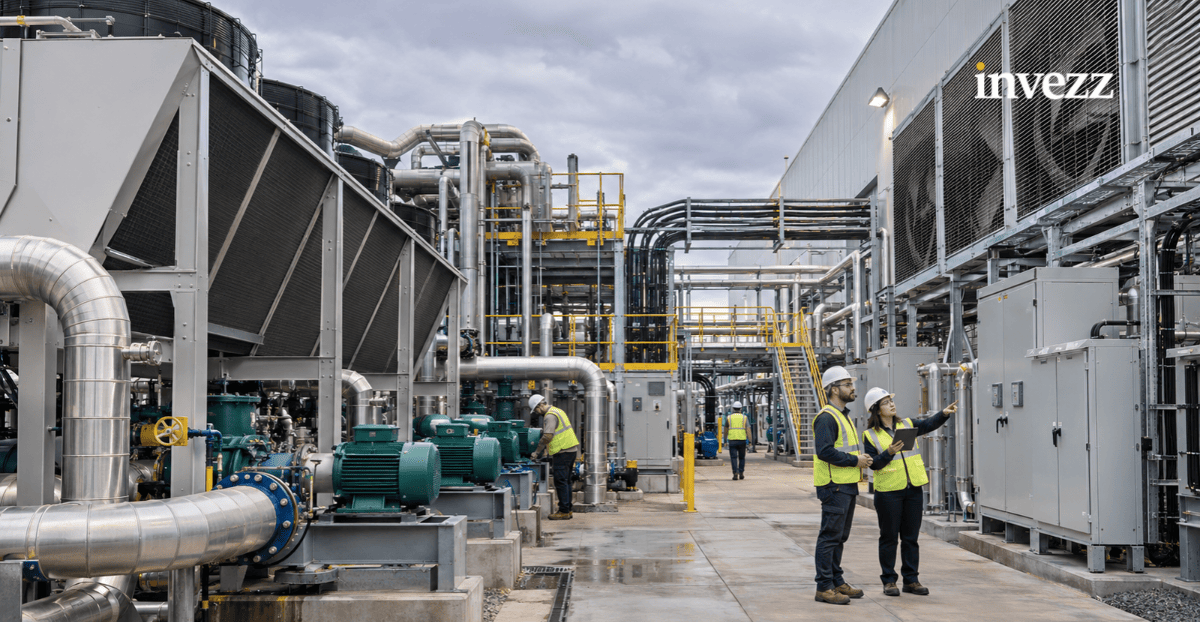
The acquisition would deepen Samsung's involvement in AI data-center infrastructure, where cooling is critical for energy-intensive processors. Modine, based in Wisconsin, manufactures industrial heating and cooling equipment, with data-center systems now its fastest-growing segment. The company recently spun off its automotive-related Performance Technologies division to focus on thermal management.
Samsung has a track record of expanding beyond memory chips through acquisitions, having purchased German heating and cooling specialist FläktGroup in 2025 for €1.5 billion to bolster its ventilation and precision cooling capabilities. Bloomberg Intelligence analyst Masahiro Wakasugi noted that acquiring Modine would help Samsung diversify away from its heavy reliance on memory chips.
Before the share-price jump, Modine's market capitalization stood at approximately $5.6 billion, though that figure does not represent an agreed purchase price. Another bidder could emerge, and neither company has officially announced a transaction. Investors are thus reacting to the possibility of a takeover premium rather than a confirmed offer.
Strong Demand Meets Margin Pressure
Modine's latest earnings illustrate why a buyer might be interested. Fiscal second-quarter revenue rose 35% to $994.4 million, with data-center sales jumping 95% to $439.7 million. The company reported over $1 billion in data-center orders, marking its fourth consecutive record. Adjusted EBITDA increased 31% to $136.2 million.
However, robust demand has not shielded margins. The Data Centers segment's gross margin fell to 19.7%, partly due to higher material costs, component prices, and tariffs. During the earnings call, Oppenheimer analyst Noah Kaye questioned whether better pricing could protect future profits, given four consecutive quarters of record orders.
Prior to the results, D.A. Davidson analyst Matt Summerville warned that supply chain conditions remain dynamic, and his firm subsequently cut its price target to $235 from $330 while maintaining a Buy rating. Modine is expanding capacity at a Texas plant that began producing Airedale chillers this week, which should support deliveries but also ties up cash.
Investor Sentiment and Risks
The after-hours surge follows a difficult period for shareholders, with the stock having fallen roughly 15% since early November results as higher costs overshadowed an expanding order book. Roth MKM analyst Thomas Hayes reduced his price target to $180 from $302 on Tuesday, reflecting uncertainty about Modine's standalone valuation rather than Samsung's intentions.
A completed acquisition could deliver a premium to shareholders, but the final terms may differ from prices implied by late trading. Talks could fail, and there is no guarantee another buyer will step forward. Modine has scheduled an investor day for November 18 to outline long-term plans following the automotive-business separation, though management has not promised any update on Samsung.
This article is for informational purposes only and does not constitute financial advice.