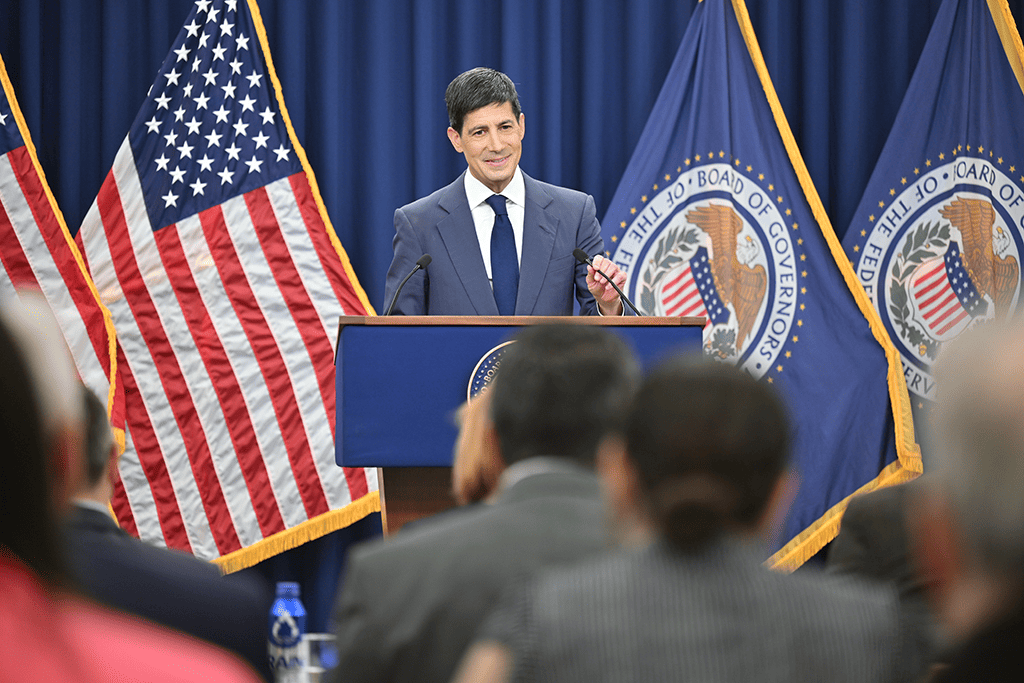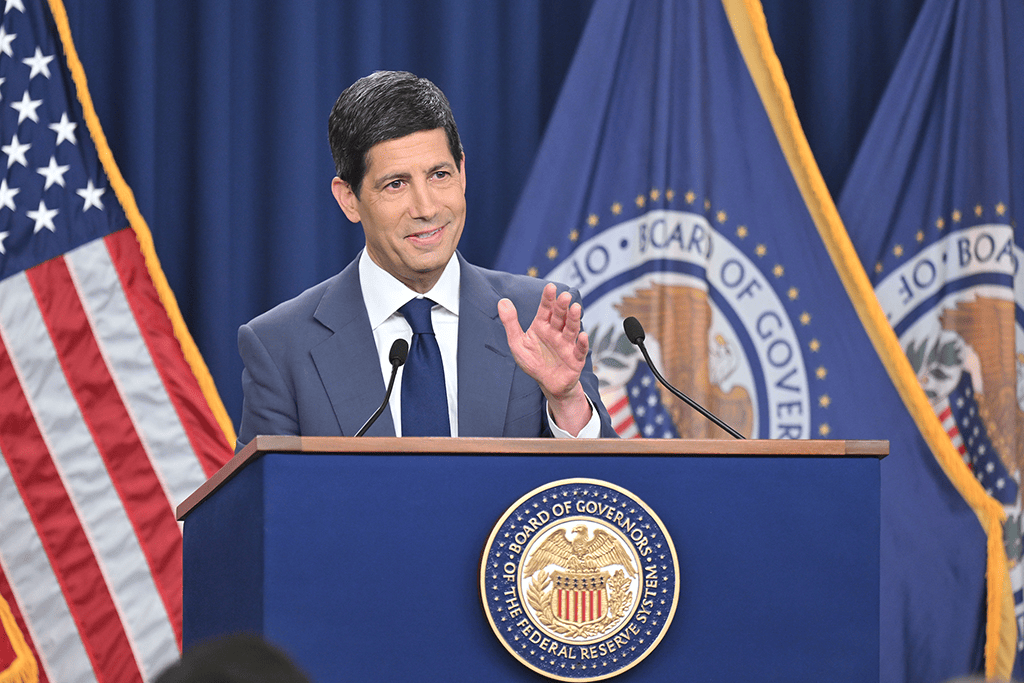
The Federal Reserve's decision to keep its benchmark interest rate unchanged was widely expected, but the accompanying guidance left investors guessing about the next move. The Federal Open Market Committee voted 10-2 on Wednesday to maintain the federal funds target range at 3.75%-4%, with two dissents favoring an immediate quarter-point increase.
In its post-meeting statement, the committee upgraded its assessment of economic activity from "solid" to "strong," citing resilient consumer spending, robust capital investment, and productivity gains. However, it reiterated that inflation "remains elevated" and noted that "the accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee's 2 percent goal." This language left room for another hike but stopped short of committing to one.
Fed Chair Kevin Warsh declined to signal the next move, saying, "I don't believe in forward guidance absent exigent circumstances, absent a crisis." His remarks were interpreted as hawkish on inflation but dovish on urgency, leaving markets to parse the mixed signals. Following Thursday's PCE inflation report, traders priced an 84.6% probability of a quarter-point hike in December, but that figure had slipped to around 73% by Friday.
Economists were divided on the message. Rebecca Homkes, an economist and lecturer at London Business School, said the meeting "managed to somehow meet expectations and still induce frustrations," noting that Warsh's brief statements "could be interpreted as inconsistent." She argued that while the outcome was expected, "guidance as to what data might inform a further hike would have been welcome," and warned that the Fed risked falling behind the curve if it did not act while price pressures persisted.
JoAnne Bianco, senior investment strategist at BondBloxx, offered a different view, saying the meeting should not be read as a dovish shift because Warsh reiterated that inflation remained above target and that the committee was prepared to tighten further if necessary. She noted that Warsh's acknowledgment that financial conditions had tightened did not mean policymakers considered them restrictive, as he said he was "unwilling and unable to call them tight."
The meeting took place six days before the US midterm elections, prompting questions about political influence. Warsh insisted politics played no role, saying he "didn't hear an utterance about politics" during the deliberations. However, Robert R. Johnson, professor of finance at Creighton University's Heider College of Business, said he believed the approaching elections were a contributing factor, arguing that "it will be much easier to raise rates in December and avoid criticism that any decision was politically motivated."
Inflation data released Thursday did little to ease concerns. The personal consumption expenditures price index rose 0.5% in September from the prior month, up from 0.3% in August, while the annual rate accelerated to 3.6% from 3.4%. Core PCE, which excludes food and energy, increased 0.3% monthly and 3.1% annually, compared with 3.0% in August. The readings were broadly in line with expectations, but they reinforced that price pressures remain sticky.
David Russell, global head of market strategy at TradeStation Group, said the PCE report did not move the needle because markets had already seen elevated CPI, PPI, and import/export price data. Bianco said the figures highlighted the uneven progress on inflation but did not materially change her December outlook. Johnson said the report provided another data point supporting a rate increase.
Looking ahead, Russell said a December hike remained his base case, given that inflation is above target while the economy and labor market remain strong. He noted that a single weak jobs report was unlikely to alter expectations, adding that "a credible decline in energy prices might be the only catalyst that could meaningfully impact interest rates."
This article is for informational purposes only and does not constitute financial advice.