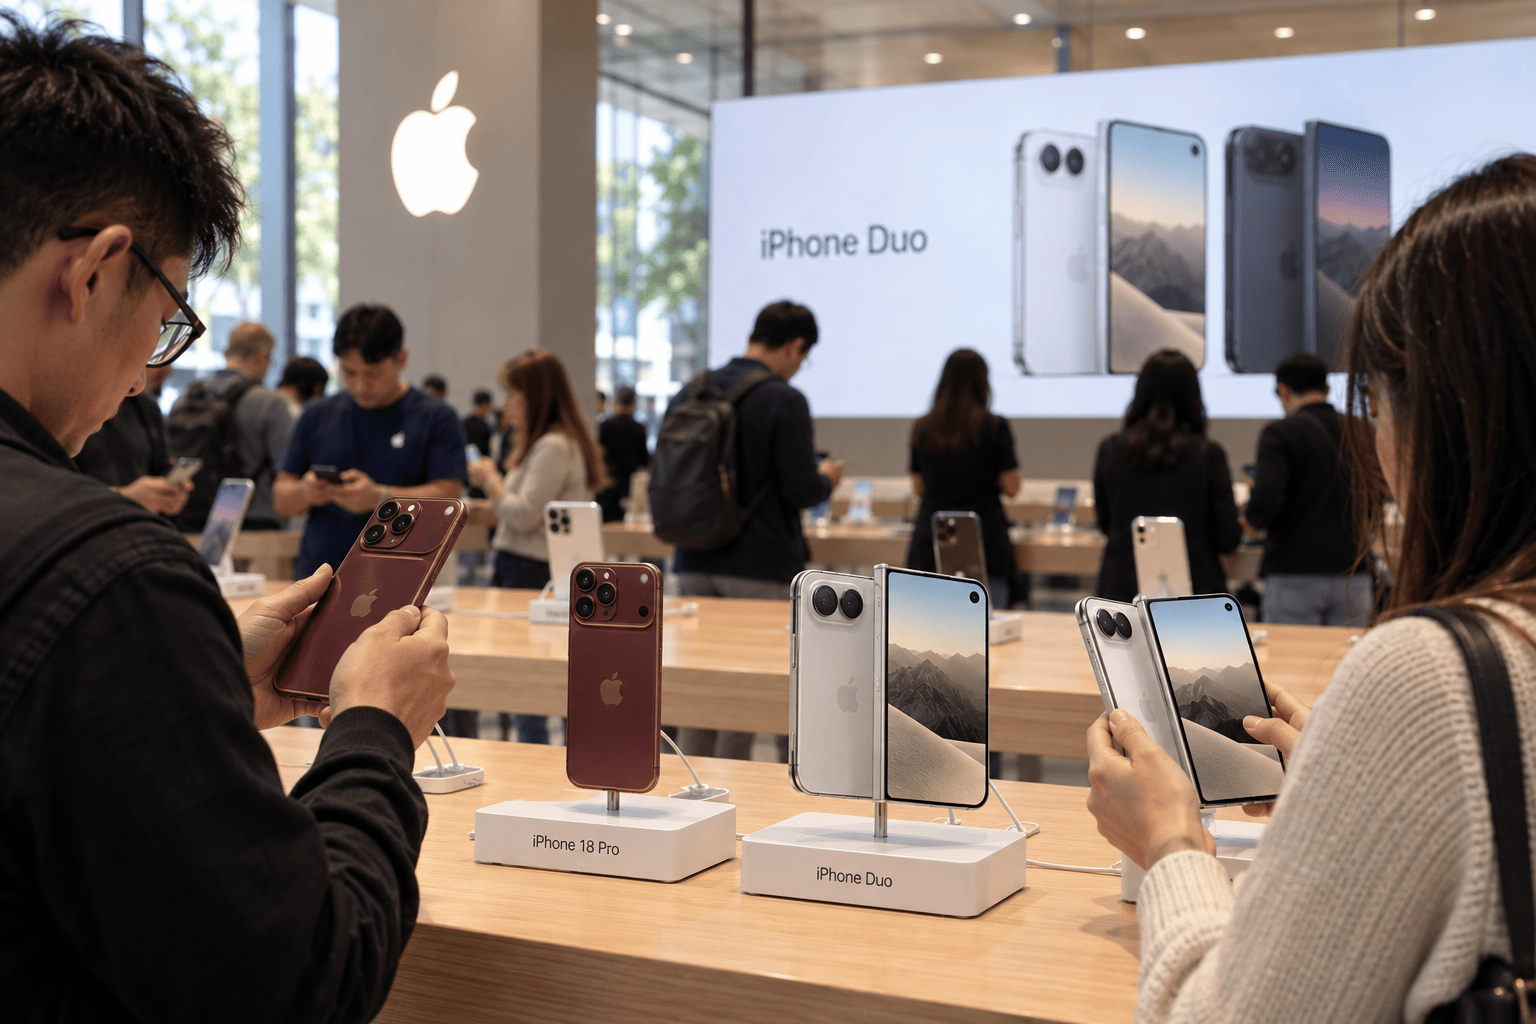
Apple's stock (NASDAQ:AAPL) reached a fresh all-time high on Friday, closing at $347.73 after touching $351.73 intraday, as robust demand for its first foldable iPhone, the iPhone Duo, fueled expectations of a significant upgrade cycle. However, Wall Street remains divided on whether the initial enthusiasm can translate into sustained earnings growth, given manufacturing hurdles and an already rich valuation.
iPhone Duo Demand Drives Rally
The iPhone Duo, priced at $1,999 and launched on October 23, sold through its initial inventory quickly, with some delivery estimates stretching into January. According to Taiwan's Economic Daily, Apple has requested a 30% increase in production orders after preorders exceeded available stock. Additionally, Apple reportedly raised its 12-month production target by 44% to 14 million devices from 9.7 million, though these figures are not confirmed company guidance.
Dan Ives, a partner at Yorkville Ives, described demand as "running well ahead of supply out of the gates," according to CBS News. Ives maintains an Outperform rating and a $400 price target, roughly 15% above Friday's close, expecting premium upgrades to support sales beyond the launch and potentially lift average selling prices further.
Supply Chain Challenges Cast a Shadow
While long delivery estimates can signal strong appetite, they also highlight production difficulties. JPMorgan analyst Samik Chatterjee noted that waits exceeding three months were partly driven by "supply ramp challenges," as reported by StreetInsider. Wall Street has trimmed its 2026 Duo shipment forecast to eight million to nine million units from 10 million, even as Chatterjee argues that current order patterns suggest demand may already exceed those projections. He kept an Overweight rating and a $360 target.
The manufacturing process is unusually demanding. Supply-chain reports indicate Foxconn's final-assembly yield was slightly above 60% in September, though Apple has not confirmed that figure. A low yield means more devices fail quality checks, raising production costs and slowing shipments. Foldable displays and hinges add further complexity, and Apple must improve yields quickly to meet holiday-season demand.
Valuation and Earnings Concerns
Loop Capital offered the clearest warning when analyst Ananda Baruah downgraded Apple to Hold from Buy on October 20, cutting his price target to $330 from $370. His supply-chain checks suggested Apple would not recover 13 million iPhone shipments previously removed from second-half plans. Loop now forecasts 79 million December-quarter shipments, below Wall Street's 85 million estimate. The brokerage also flagged rising memory costs and reduced its normalised earnings estimate to $11 a share from $12.
"The stock also requires a fundamental catalyst reset after its recent stock appreciation," Baruah said, according to Investing.com. Apple reports fiscal fourth-quarter earnings on November 2, but the September-ended period will not include Duo sales. Investors will instead examine iPhone 18 demand, profit margins, and management's guidance on increasing foldable production.
While the Duo's higher selling price could benefit Apple, that advantage shrinks if assembly inefficiencies and costly components eat into gross margins. The stock's recent appreciation has left little room for error, and the market will be watching closely to see if Apple can convert initial hype into durable financial performance.
This article is for informational purposes only and does not constitute financial advice.