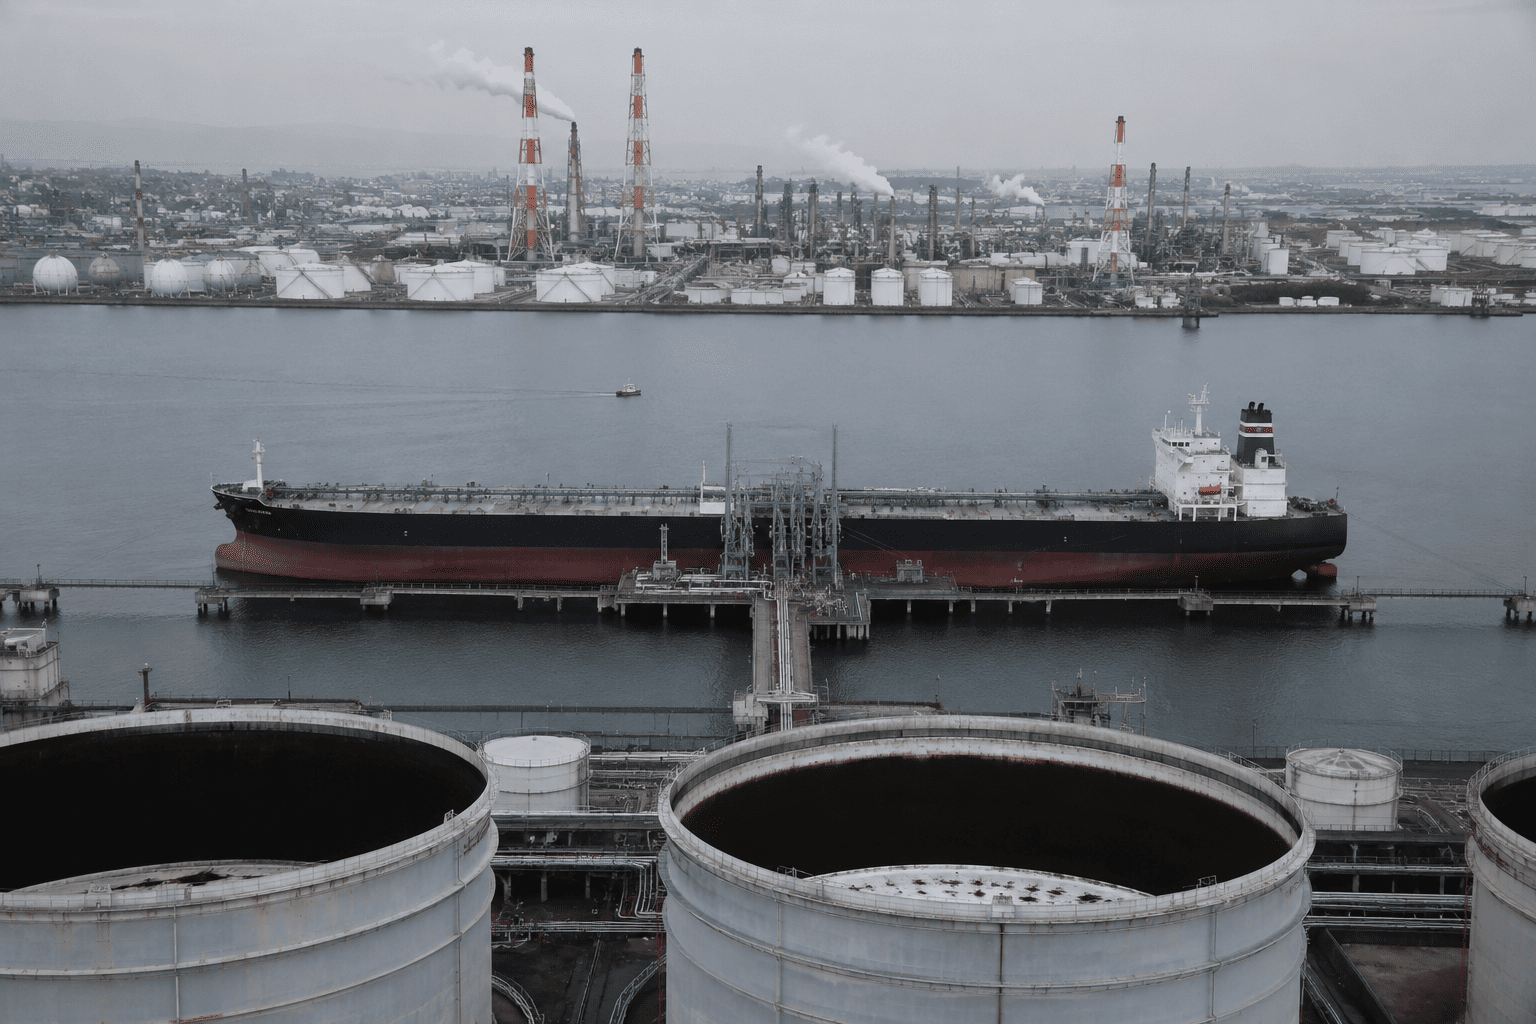
Oil prices slipped on Monday as diplomatic efforts to de-escalate the US-Iran conflict offered some relief, but the specter of renewed supply disruptions kept traders on edge. Brent crude fell $2.21 to $114.51 a barrel, while US West Texas Intermediate dropped 2.16% to $101.04. The previous week had seen Brent gain about 6% following attacks on Saudi Arabia that heightened concerns over regional energy supplies.
The pullback has left the market weighing two contrasting outcomes: a gradual rebuilding of inventories or a fresh disruption that could drive Brent toward $120. Qatari mediators traveled to Tehran on Sunday in an attempt to reduce tensions with Washington, prompting investors to trim some of the risk premium built into prices. Yet the security situation remains fragile, with the Iran-aligned Houthis claiming attacks on Saudi airport and oil facilities over the weekend, and Saudi authorities reporting interceptions of further missiles and drones.
Why the retreat may not last
Vanda Insights cautioned that shipping workarounds are becoming increasingly vulnerable to new attacks, placing Brent in a $110–$120 trading range with risks tilted upward near $114. That leaves little room for disappointment if talks fail to produce a meaningful reduction in hostilities. The market is acutely sensitive to any sign that the diplomatic window is closing.
Goldman's $120 scenario
Goldman Sachs outlined a $120-a-barrel scenario in September if attacks on Middle Eastern shipping intensified, though it was an escalation case rather than the bank's central forecast. The mechanism is straightforward: attacks on vessels or export facilities could restrict available cargoes, raise insurance and freight costs, and force refiners to compete for barrels before supplies actually disappear. On the Goldman Sachs Exchanges podcast published on 23 October, commodities research co-head Daan Struyven noted that refiners were buying ahead of possible shortages, while investors were using oil to hedge against rising energy prices.
Struyven also highlighted an imbalance beneath the crude recovery. Persian Gulf crude exports were running above their 2025 average, but refined-product exports, including diesel and petrol, remained at about 40% of last year's levels. This leaves fuel markets especially vulnerable, even if headline crude shipments continue to recover.
Bearish counterargument
There is also a reason crude has retreated from Friday's $116.72 settlement. Vivek Dhar of Commonwealth Bank of Australia said in comments reported by The Wall Street Journal on Monday that Middle Eastern oil flows had recovered towards prewar levels, easing the immediate threat of inventory depletion. Continued shipments could allow crude and fuel stocks to rebuild. Goldman's latest base case sees Brent at $90 by year-end, well below its earlier $120 escalation scenario.
The market now faces a delicate balance: diplomatic progress could support a gradual normalization, but any renewed attack on shipping could quickly reverse the decline and push prices toward the upper end of the range. Traders are watching for further developments in the Middle East and any signs of inventory builds in the coming weeks.
This article is for informational purposes only and does not constitute financial advice.