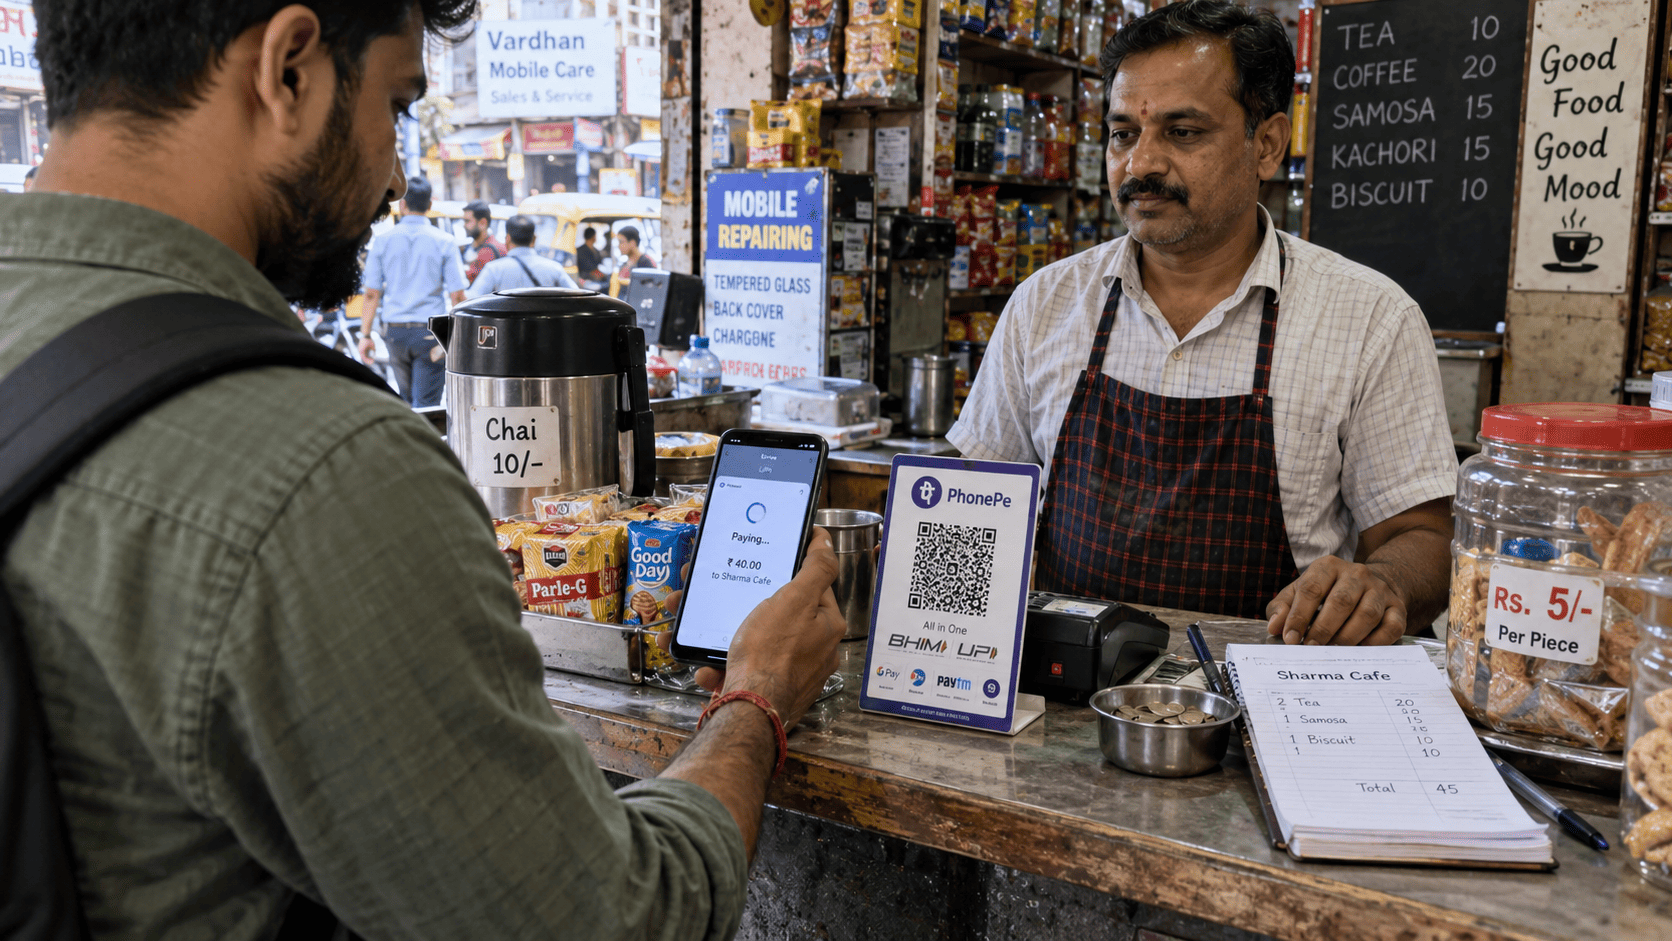
India's move to introduce a merchant discount rate (MDR) on selected UPI payments has sparked debate over who should fund the country's digital payment infrastructure. Starting October 15, person-to-merchant transactions above ₹2,000 will attract a 0.4% fee, capped at ₹300, while smaller payments and small merchants remain exempt. The government says about 96% of merchant transactions will be unaffected.
But the bigger issue lies beyond the fee itself. UPI is not just a payment rail; it generates digital transaction records that can help formalise businesses, improve credit assessment, and give lenders a clearer view of cash flows. As India begins monetising UPI directly, the data generated by the network could ultimately be worth more than the MDR revenue.
UPI's value extends beyond moving money
The scale is enormous. UPI processed 24.5 billion transactions worth about ₹29.82 lakh crore in August, according to NPCI data. For banks and fintechs, a payment can have value beyond the few basis points earned for processing it.
Indian policymakers have recognised this. Government material on digital public infrastructure says UPI has helped small businesses establish verifiable transaction histories, improving the ability of banks and fintechs to assess creditworthiness. That does not mean UPI transaction data can simply be sold or repurposed. Lending and data-sharing remain subject to consent, privacy, and regulatory safeguards. But the financial footprint created by digital payments can become an underwriting input when accessed lawfully.
This matters in India, where many small businesses have historically lacked the financial records lenders prefer. The data-driven credit assessment is a key benefit of digital payments.
MDR solves one problem but could create another
The case for MDR is straightforward: UPI costs money to operate. Professor Ashish Das of IIT Bombay told Invezz that the network has a real operating cost. “There is a cost for running the UPI system. The approximate cost can run into several thousand crores,” Das said. He estimated annual costs could fall between ₹5,000 crore and ₹20,000 crore, while the new MDR system could generate roughly ₹15,000 crore. Those are estimates rather than audited figures, but they illustrate the funding problem.
Das said the economics depend on how closely MDR revenue matches the actual cost of running UPI. If revenue exceeds that cost, the system creates a profit pool; if it falls short, the funding gap remains. ASSOCHAM President Nirmal K Minda told Invezz that MDR would make UPI more sustainable and support investment in infrastructure, fraud prevention, and innovation. Jyoti Prakash Gadia, managing director of Resurgent India, made a similar argument, saying the revenue could help banks and payment providers fund cybersecurity and expansion, although it may not fully recover investments already made in building UPI.
The hidden risk is losing valuable digital behaviour
The tension begins if merchants respond to MDR by changing behaviour. Dr Manoranjan Sharma, chief economist at Infomerics Ratings, told Invezz that the legal incidence of the charge and its economic incidence need not be the same. Merchants could absorb the cost, but they could also reduce discounts, raise prices, or steer customers towards other payment methods. Sharma said consumers should watch for cash discounts, altered pricing, and payment-specific incentives.
“If merchants raise broad prices rather than visibly charging UPI users, MDR becomes part of general operating costs and consumers may not identify its source,” he said. Previous government policy promoted low-value UPI partly because digital payments formalise transactions and create financial footprints that can improve access to credit. A cash transaction produces far less usable information for a lender assessing business activity.
That makes the trade-off more complicated than MDR revenue versus merchant costs. India could gain a recurring source of funding for its payments network while weakening, at the margin, the data trail that makes the network useful for lending and formalisation. The revenue versus data trade-off is a common theme in tech-driven sectors.
The real prize may sit beyond payments
The new MDR framework does not necessarily undermine UPI's data advantage. Most transactions remain outside the charge, and small merchants retain protections. But policymakers now have two objectives to balance. UPI needs sustainable economics for banks, apps, and payment providers. It also needs merchants to keep choosing digital payments often enough for their transaction histories to remain useful.
Gadia told Invezz that the central challenge is ensuring higher ecosystem costs do not ultimately translate into higher consumer costs. The same logic applies to data. For India, that less visible asset may ultimately prove more important. As the value of data grows, the balance between monetising UPI and preserving its data-generating role will be crucial.
This article is for informational purposes only and does not constitute financial advice.