Bloom Energy shares climbed 12% on Tuesday after RBC Capital Markets senior analyst Chris Dendrinos reaffirmed a bullish stance on the fuel cell manufacturer, keeping an Outperform rating and a $335 price target. That target implies upside of just under 30% from the stock's prior close, even after the session's sharp advance.
The call arrives as Bloom Energy stock sits roughly 15% below its year-to-date high, a pullback that follows a powerful run earlier in 2026. Dendrinos frames that retreat as an attractive entry point rather than a warning sign, arguing the company's fundamental demand picture has strengthened even as the share price cooled.

Why RBC is bullish
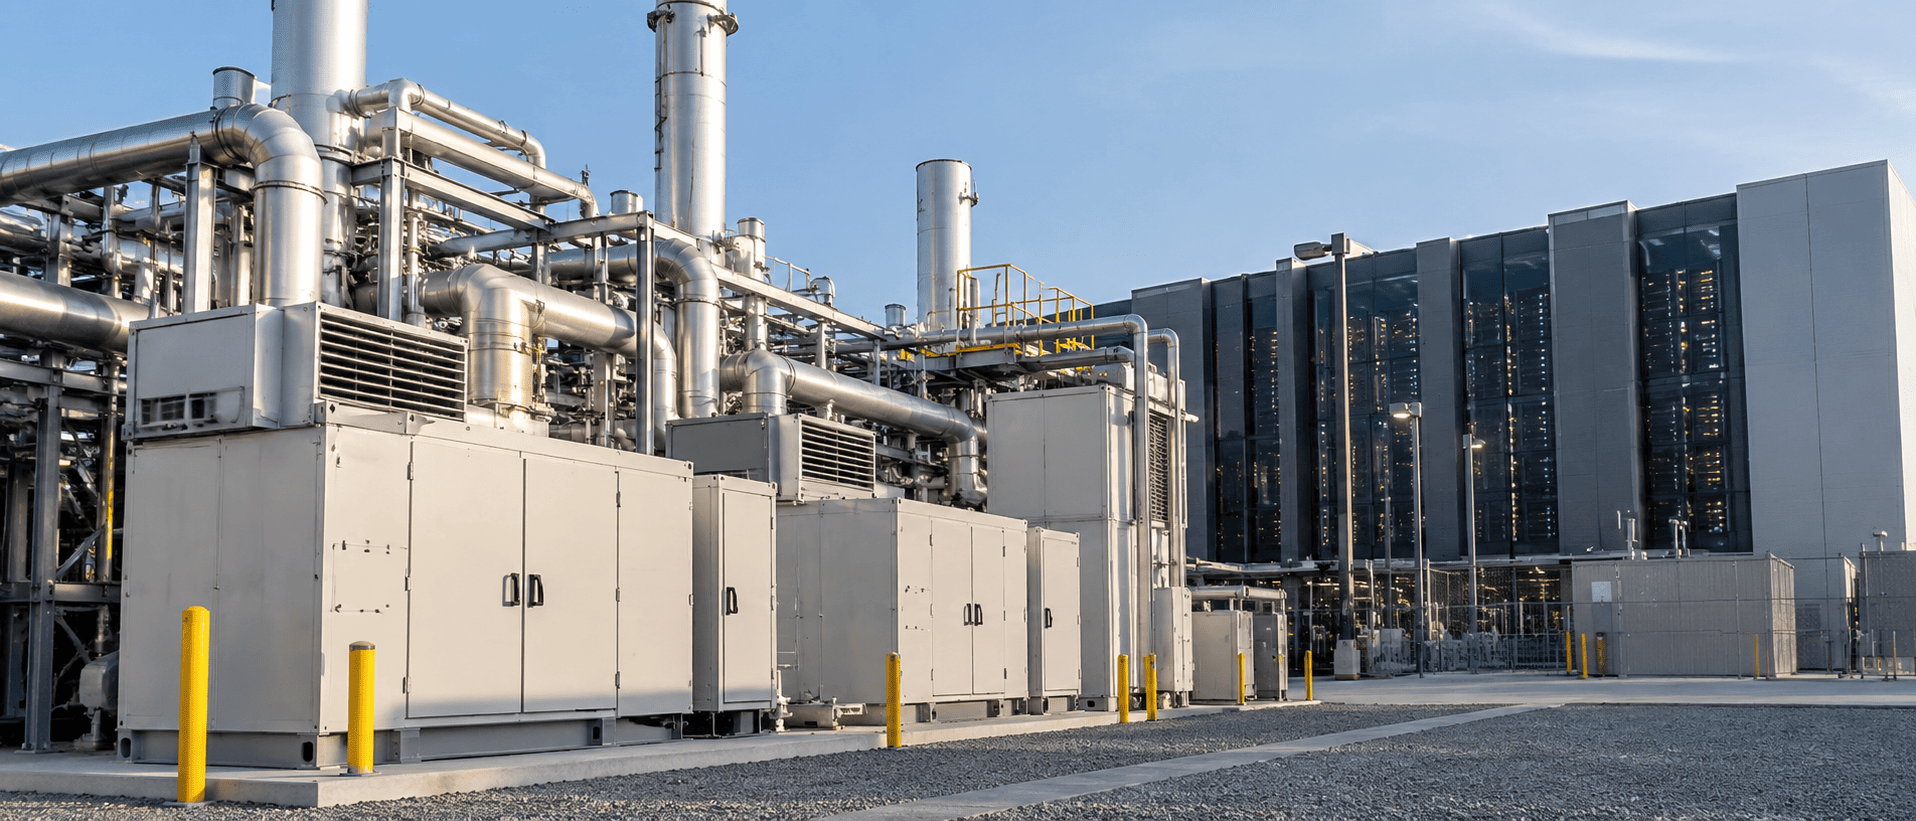
At the center of the thesis is Bloom's solid oxide fuel cell technology, which RBC contends is uniquely suited to address the immediate power constraints facing artificial intelligence data centers. As hyperscalers race to lock down reliable off-grid electricity, Bloom's rapid-deployment systems offer a bridge where traditional utility interconnections can take years to complete.
RBC also points to expanding commercial partnerships, favorable momentum in clean energy, and a substantial backlog of data center orders as evidence that underlying demand drivers remain intact. From a technical standpoint, the stock pushed through its 20-day moving average on Tuesday, a signal that buyers have regained near-term control.
Catalysts for the fourth quarter
Dendrinos highlighted key operational catalysts expected in late 2026 that could reignite the shares. Bloom is entering the final quarter with accelerating manufacturing throughput and improving unit economics, which the analyst says positions the company to deliver strong top- and bottom-line results.
As production scale lowers the cost structure and operating leverage takes hold, RBC expects expanding profit margins to reassure investors. The analyst views anticipated project completions and new order announcements as potential triggers for a re-rating, reinforcing his view that Bloom offers a compelling, underpriced growth runway into year-end.
Manufacturing expansion underpins the case
Central to the bullish outlook is Bloom's aggressive capacity expansion, most notably the ramp-up at its Fremont manufacturing facility. Dendrinos notes that scaling production infrastructure directly targets the large order backlogs coming from energy-intensive sectors.
By broadening its physical footprint and optimizing manufacturing lines, Bloom is working to reduce the production bottlenecks that previously constrained delivery schedules. RBC stresses that this structural scaling not only improves operational reliability but also strengthens Bloom's competitive moat as a primary off-grid power provider. Rising factory utilization rates into year-end, the analyst argues, provide a clear pathway to sustaining hyper-growth through 2026 and beyond.
Wall Street is not unanimous
Investors should note that Dendrinos' enthusiasm is not shared across the entire analyst community. While the consensus rating on Bloom Energy stands at Overweight, the mean price target of $287 sits below the stock's current share price, implying that the average analyst sees limited upside from here.
The divergence highlights the debate around Bloom's valuation after its strong 2026 performance. RBC's $335 target places Dendrinos among the more optimistic voices on the Street, and his case rests on execution against a data center power bottleneck that shows few signs of easing.
This article is for informational purposes only and does not constitute financial advice.

