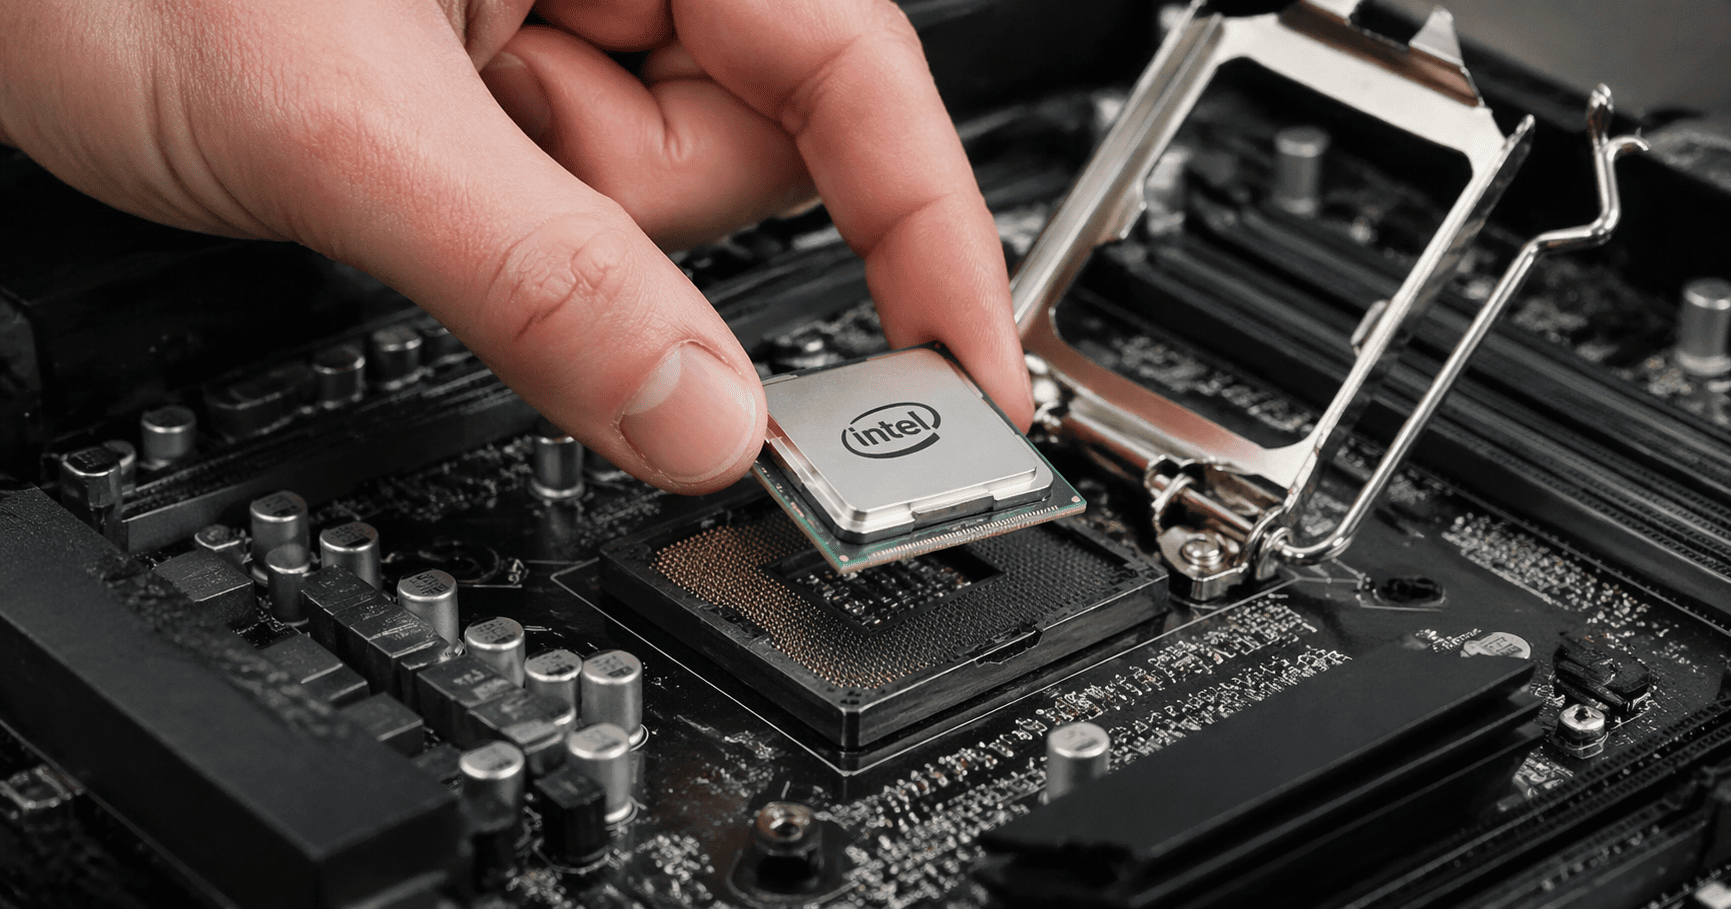
Intel Corporation is set to release its fiscal third-quarter earnings after the market close on October 29. While the stock has already delivered a remarkable 135% gain year-to-date, derivatives market activity suggests traders anticipate further upside following the report.
Consensus estimates project revenue of $16.48 billion and earnings per share of $0.40, representing year-over-year increases of approximately 21% and 74%, respectively. The semiconductor giant has been a standout performer in 2026, but questions remain about the sustainability of its rally.
Options Data Points to Post-Earnings Rally
According to recent options data, the put-to-call ratio for Intel contracts expiring November 6 stands at 0.67, a level typically interpreted as bullish sentiment. The upper price bound implied by these options is around $102, suggesting a potential gain of more than 9% from current levels through the end of next week.
If this options-driven scenario plays out, Intel shares would break above key moving averages, potentially supporting continued momentum through the remainder of the year. However, the stock does not offer a dividend, which may deter income-focused investors.
Needham Maintains Cautious Stance
Just days before the earnings release, Intel announced plans to acquire Classiq, a quantum software firm, for approximately $2.3 billion—the largest quantum software deal to date. While this acquisition complements Intel's silicon spin-qubit hardware and positions it as a full-stack quantum computing platform, Needham analysts have reiterated a Hold rating on the stock.
In a research note, the firm acknowledged the strategic value of the Classiq deal but highlighted concerns about Intel's AI accelerators being less competitive and ongoing market share losses in the data-center CPU segment. With the stock trading at roughly 83 times forward earnings, Needham sees limited near-term upside.
Key Factors to Watch on October 29
Beyond the headline numbers, investors will focus on management's forward-looking commentary. A quarterly beat alone may not suffice; the market will look for evidence that stronger demand translates into durable profitability, rather than just higher sales.
Management's remarks on customer commitments, capital allocation, and the timing of returns on investment will be critical in shaping the market's response. The earnings call could also provide clarity on how the Classiq acquisition fits into Intel's broader strategy and its impact on future margins.
The average analyst price target for Intel currently stands at approximately $114, implying about 20% upside from current levels. However, with the stock already up significantly this year, the upcoming earnings release will test whether shareholders have fresh reasons to stay invested as attention shifts toward 2027.
As the market awaits the results, the options data offers a bullish near-term signal, but the fundamental challenges highlighted by Needham serve as a reminder of the risks that lie ahead.
This article is for informational purposes only and does not constitute financial advice.