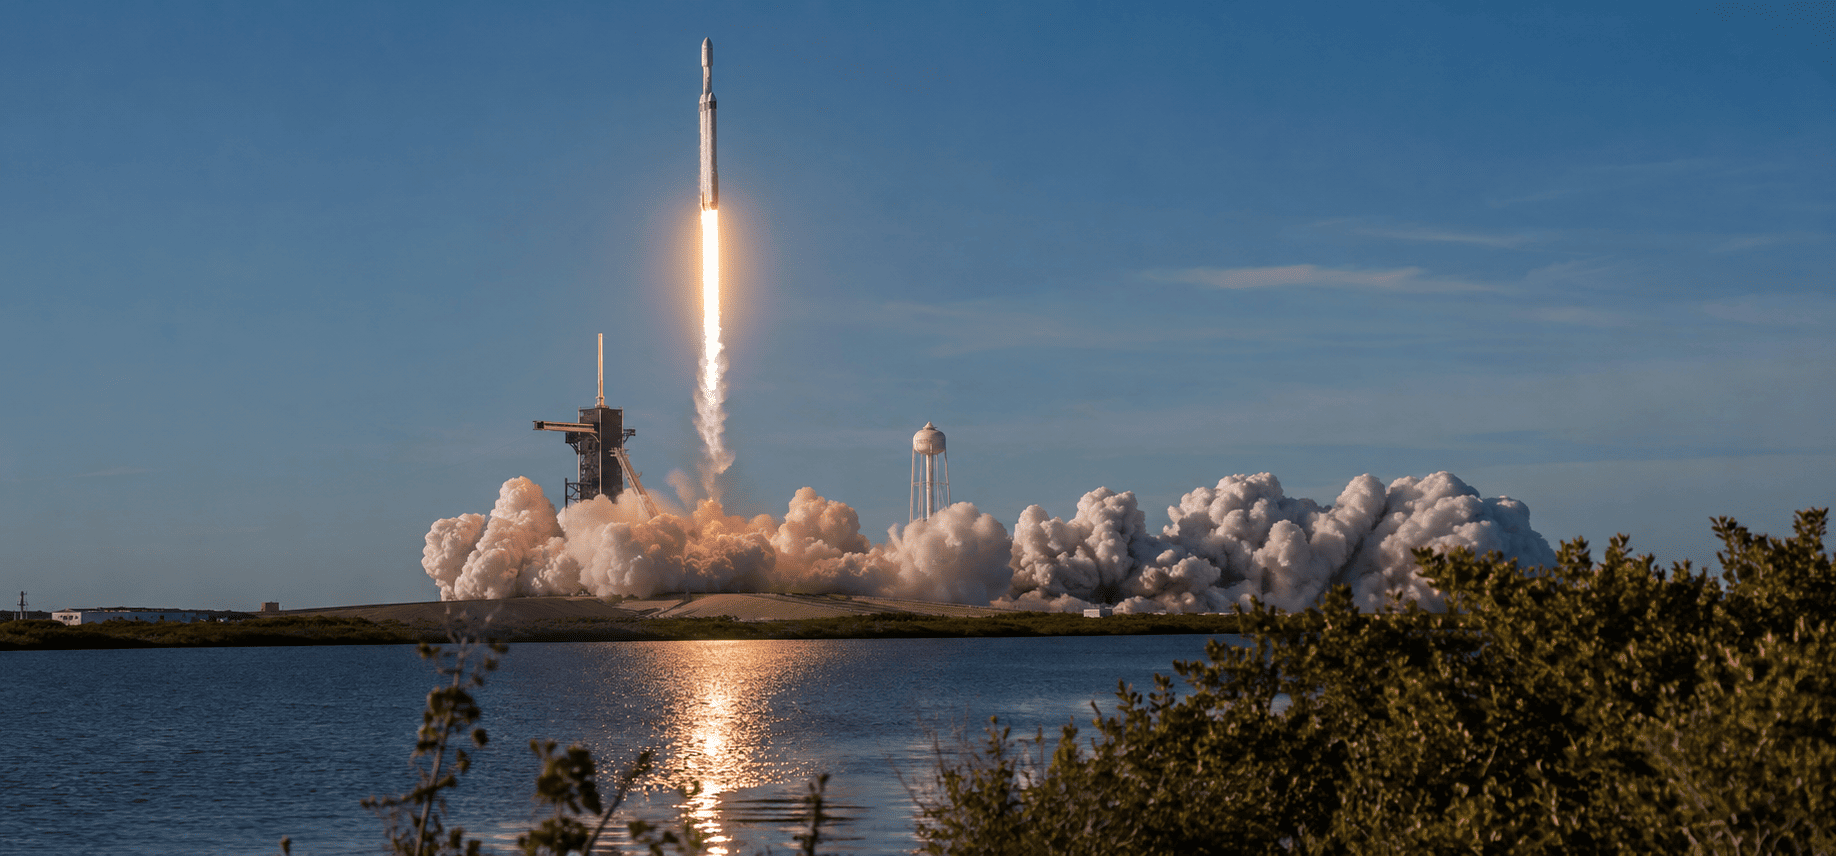
SpaceX shares declined 4.2% to $156.54 on Tuesday, even as Wall Street analysts maintain a bullish outlook. According to TipRanks, the average price target of $216 implies approximately 38% upside, with 28 Buy ratings, five Holds, and two Sells. This disconnect highlights the tension between SpaceX's long-term vision and the substantial capital required to achieve it.
The latest catalyst for investor caution is SpaceX's agreement to acquire up to 14 MHz of nationwide 800 MHz spectrum from Grain Management for about $8 billion. This purchase aims to support Starlink Mobile, providing low-band frequencies that can improve indoor and rural coverage. Pivotal Research analyst Jeffrey Wlodarczak raised his price target to $230 from $220, maintaining a Buy rating, and noted that SpaceX "appears to have created a legitimate new low-cost carrier" initially targeting rural and suburban customers. Pivotal forecasts roughly 160 million Starlink Mobile subscribers globally by 2036.
However, the addressable market is enormous only if SpaceX successfully integrates satellites, spectrum, and terrestrial infrastructure. Investors are being asked to value this opportunity years before its economics are proven, and a roughly $2 trillion valuation leaves little room for delays or missteps.
Ground infrastructure remains the missing piece
Owning spectrum is not the same as operating a dependable nationwide network. Stifel analyst Jonathan Siegmann reiterated a Buy rating and $190 target, but identified the central challenge: "Ground infrastructure is the missing piece." He suggested SpaceX could build the network itself, partner with existing operators, or redesign its architecture. Barron's reported that a competitive direct-to-cell network could require more than $100 billion if SpaceX builds much of the infrastructure independently.
Raymond James analyst Frank Louthan offered a more measured view, stating that "the recent fears over competition from SpaceX are overblown, as they are 3+ years away from becoming reality." Incumbents have far greater terrestrial capacity, and building a reliable network from scratch is a formidable task.
Financing the future could become the bigger valuation test
SpaceX is also ramping up spending on Starship, satellite deployment, and an expanding artificial-intelligence push. The company is seeking roughly $40 billion in financing to purchase Nvidia chips, including about $10 billion in bank loans and $30 billion in investment-grade debt. JPMorgan analyst Doug Anmuth projects capital expenditure could reach about $200 billion in both 2027 and 2028, after SpaceX spent $28.5 billion in the first half of 2026.
Debt raises interest expenses, while equity financing can dilute shareholders. Delays in Starlink Mobile, Starship, or AI monetisation would leave investors carrying these costs for longer. The market is already pricing in some of this risk: the Financial Times reported that SpaceX's five-year credit-default-swap spread reached a record as investors assessed the borrowing surge.
For now, the gap between analyst optimism and investor selling reflects a fundamental question: can SpaceX execute on its ambitious roadmap without eroding shareholder value? The answer may take years to unfold, but the market's skepticism is evident in the stock's recent price action.
This article is for informational purposes only and does not constitute financial advice.