Rocket Lab (RKLB) shares broke below a closely watched support level this week after the company disclosed another delay to its Neutron launch program. The stock fell to $54.54, its lowest print since December 2025, and now sits roughly 65% below its high for the year, wiping out billions in market capitalization.
Neutron pushed to 2027
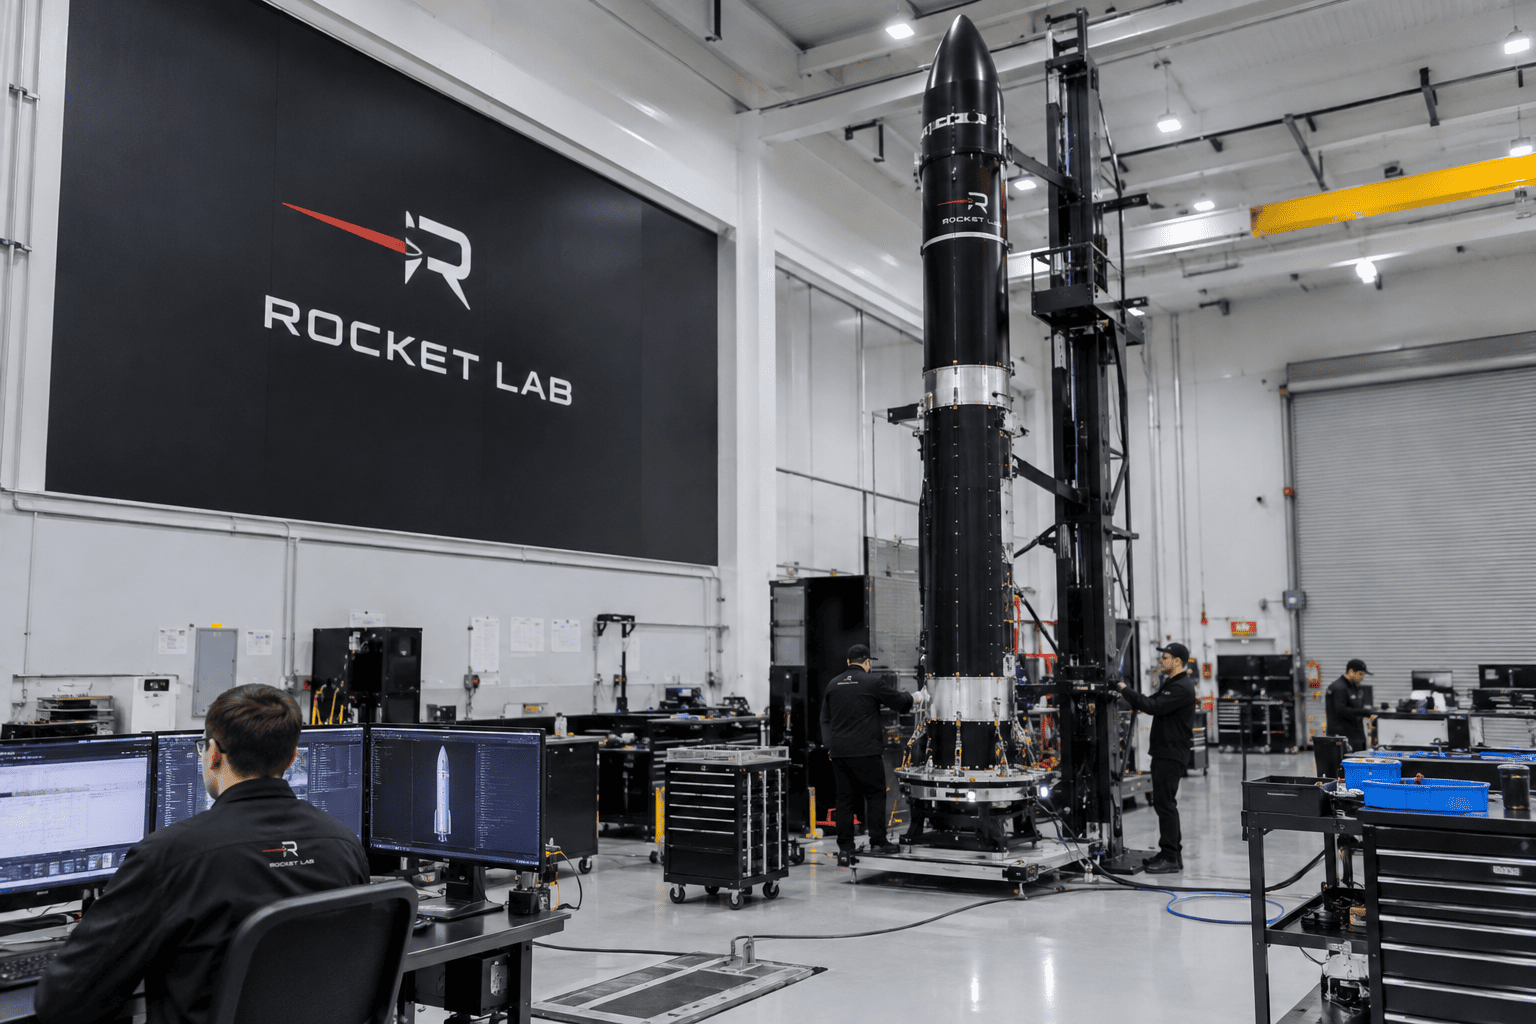
The sell-off intensified after Rocket Lab said it now expects Neutron to fly sometime in 2027, without specifying a month. Management framed the decision as necessary to ensure safety, but the delay stems from a newly identified issue in the manufacturing of the rocket's propellant tanks, according to Bloomberg. Neutron is the company's reusable medium-lift vehicle, designed to carry payloads of up to 13,000 kilograms — far more than the Electron rocket currently in service. Once operational, it is intended to compete directly with SpaceX's Falcon 9 and Blue Origin's New Glenn.
This is not the first schedule slip for Neutron. The program has been delayed repeatedly since 2024, and the latest pushback means the company will continue absorbing development costs without the associated revenue for longer than investors had anticipated.
Competitive pressure mounts
Rocket Lab's stock is also under pressure from an increasingly crowded launch market. SpaceX continues to dominate, particularly in NASA contracts, while Blue Origin recently raised capital at a $140 billion valuation as it looks to scale up its competitive position. Those dynamics make Neutron's timely arrival more important, not less.
Core business still growing
Despite the Neutron setback, Rocket Lab's underlying operations remain healthy. Second-quarter revenue climbed 62% year over year to $234 million, with the bulk of that coming from the space systems segment and the remainder from launch services. Backlog rose above $2.2 billion, split roughly 60% commercial and 40% government, signaling solid demand across its product lines.
Analysts expect the next quarterly report to show revenue of about $257 million, a 65% increase, with the most bullish estimates near $265 million. For the full year, consensus calls for revenue growth of roughly 60% to $960 million.
Technical picture weakens
On the daily chart, RKLB has been under sustained selling pressure for months. The break below $59.18 — a level that held in July and September — confirms that bears have taken control. The stock is trading beneath both its 50-day and 100-day exponential moving averages and remains below the Supertrend indicator, suggesting the path of least resistance is lower. The next key level to watch is $50.
This article is for informational purposes only and does not constitute financial advice.