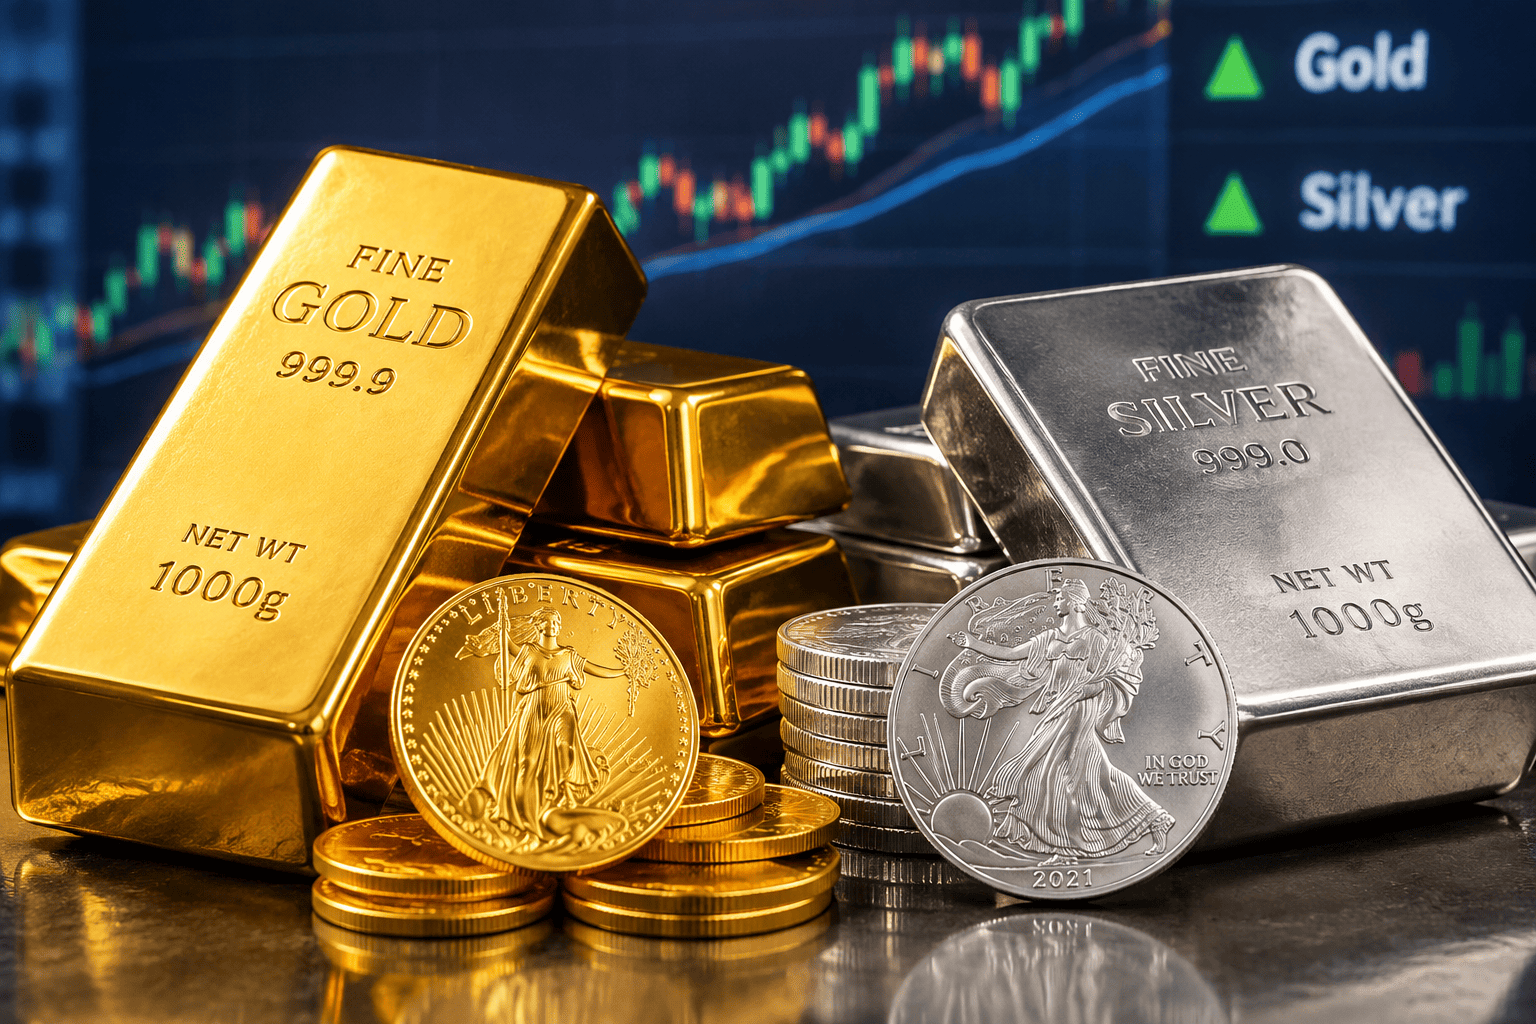
Gold has absorbed a difficult stretch of macro pressure yet continues to trade above the psychologically important $4,000 per ounce mark, a resilience that Morgan Stanley reads as evidence the metal's longer-term drivers remain in place.
The headwinds have been substantial. Long-dated bond yields sit near two-decade highs, the US dollar has stayed firm, and crude oil prices remain elevated. For a non-yielding asset, that combination is normally punishing. A sudden swing in sentiment also forced a rapid unwind of short-term algorithmic positions that had been built up during late-summer rallies, adding to the selling pressure.
Even so, bullion has not broken down. Amy Gower, who leads metals and mining strategy at Morgan Stanley, told CNBC that the case for holding gold in a portfolio is still intact. Her view rests less on short-term momentum and more on the structural forces that have been building for years.
Central bank buying anchors demand
Physical demand is the foundation. Central banks, notably in China and Poland, keep adding to reserves as they seek to reduce reliance on foreign fiat currencies. Chinese imports are on track for their strongest year since at least 2017, a sign that underlying appetite is durable even ahead of seasonal slowdowns such as Golden Week.
Alongside official-sector purchases, persistent worries about long-term sovereign debt sustainability and fiscal expansion continue to push capital toward tangible stores of value. Should central bank actions succeed in pulling long-term yields lower, or should energy costs ease, those macro concerns would likely move back to the foreground, reinforcing the $4,000 area as a structural floor rather than a temporary line in the sand.
Institutional flows defy the rate cycle
What stands out in the current environment is the behavior of institutional money. Gold-backed exchange-traded funds have kept adding to holdings, an unusual pattern during a monetary cycle shaped by Federal Reserve rate hikes. Fast-moving quantitative funds have generated sharp technical swings, but core institutional allocations have been notably stable.
Morgan Stanley expects that steady accumulation to eventually outweigh both transient dollar strength and algorithmic churn. On a 12-month view, Gower forecasts spot prices to break back above $5,000 per ounce in the second half of 2027, which implies that recent pullbacks could represent attractive entry points for investors with a longer time horizon.
Positioning across the metals complex
Beyond gold, the broader resources space calls for a more selective approach. Gold remains a core defensive holding on a 12-month basis, while base metals present a mixed picture.
- Copper is a high-conviction long on price dips, supported by tight global supply, sustained US imports, and active Chinese buying.
- Aluminum and iron ore face headwinds from expanding production margins and supply responses.
- Uranium stands out as a top-tier structural play, driven by a multi-year nuclear power expansion, severe supply-side underinvestment, and aggressive utility contracting that continues to tighten physical spot availability alongside physical ETF buying.
For investors weighing gold heading into 2027, the debate is less about whether the metal can rally in a straight line and more about whether the structural bid from central banks and institutions persists. Morgan Stanley's answer, for now, is that it does.
This article is for informational purposes only and does not constitute financial advice.