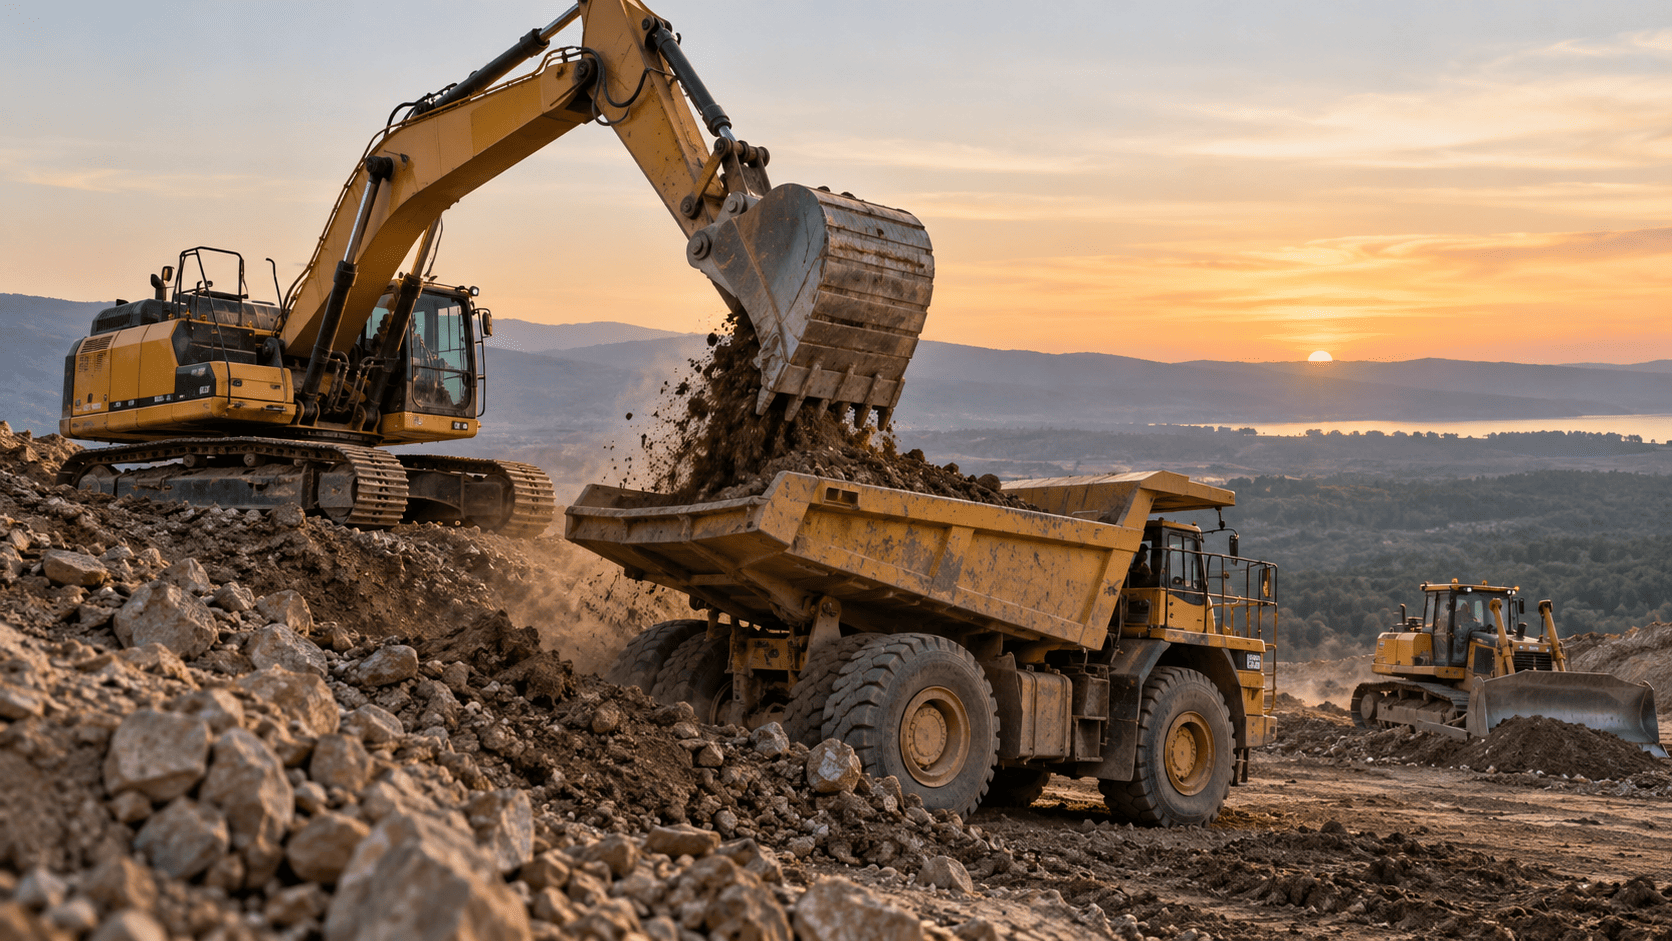
Caterpillar's shares opened sharply lower on Thursday despite the industrial giant reporting fiscal third-quarter earnings that matched analyst forecasts. The market's disappointment centered on revenue that came in roughly in line at $20.68 billion and unchanged annual sales guidance, offering little reassurance to investors seeking stronger signs of sustained growth, particularly from data center power equipment demand.
However, the pullback may present a compelling entry point for patient investors. The company's order backlog reached a record $78.1 billion, up $6 billion from the prior quarter, indicating continued customer commitment even as the pace of expansion slows. Management also reaffirmed its outlook for mid-to-high teens revenue growth for the full year.
Record Backlog Supports Future Sales
The expanding backlog provides visibility into future equipment deliveries, which is a positive signal for those willing to look beyond the immediate market reaction. While slower order growth might justify more conservative expectations, the fact that clients are still committing capital suggests underlying demand remains resilient. The bullish case for CAT shares does not rely on another acceleration in demand; converting existing commitments into profitable sales could support shareholder returns, provided execution holds and the purchase price leaves room for disappointment.
Operating Leverage Drives Profit Growth
Caterpillar's operating profit surged 38% year-over-year to $4.214 billion, outpacing the 17% revenue increase. This improvement included $128 million in tariff recoveries, but even excluding those, operating profit would have risen about 34%. This demonstrates significant operating leverage: higher equipment volumes are generating disproportionately larger profits. If demand remains resilient, CAT can potentially grow earnings without needing an equally large increase in revenue, making the current share price decline look potentially overdone.
Strong Cash Flow and Shareholder Returns
The company generated $4.4 billion in enterprise operating cash flow during the quarter and ended September with $7.9 billion in cash. It also repurchased $1.2 billion of shares. This financial flexibility is crucial when market sentiment turns negative, allowing management to fund operations and investments while continuing shareholder distributions. Repurchases at lower prices can retire more shares for the same expenditure, supporting future per-share earnings.
While the decline alone does not establish that CAT stock is cheap, and further weakness remains possible, the stronger argument for buying is that investors now have a lower entry price into a business with expanding commitments and improving profitability. For those willing to hold through an industrial cycle, that combination makes a measured purchase worth considering.
This article is for informational purposes only and does not constitute financial advice.