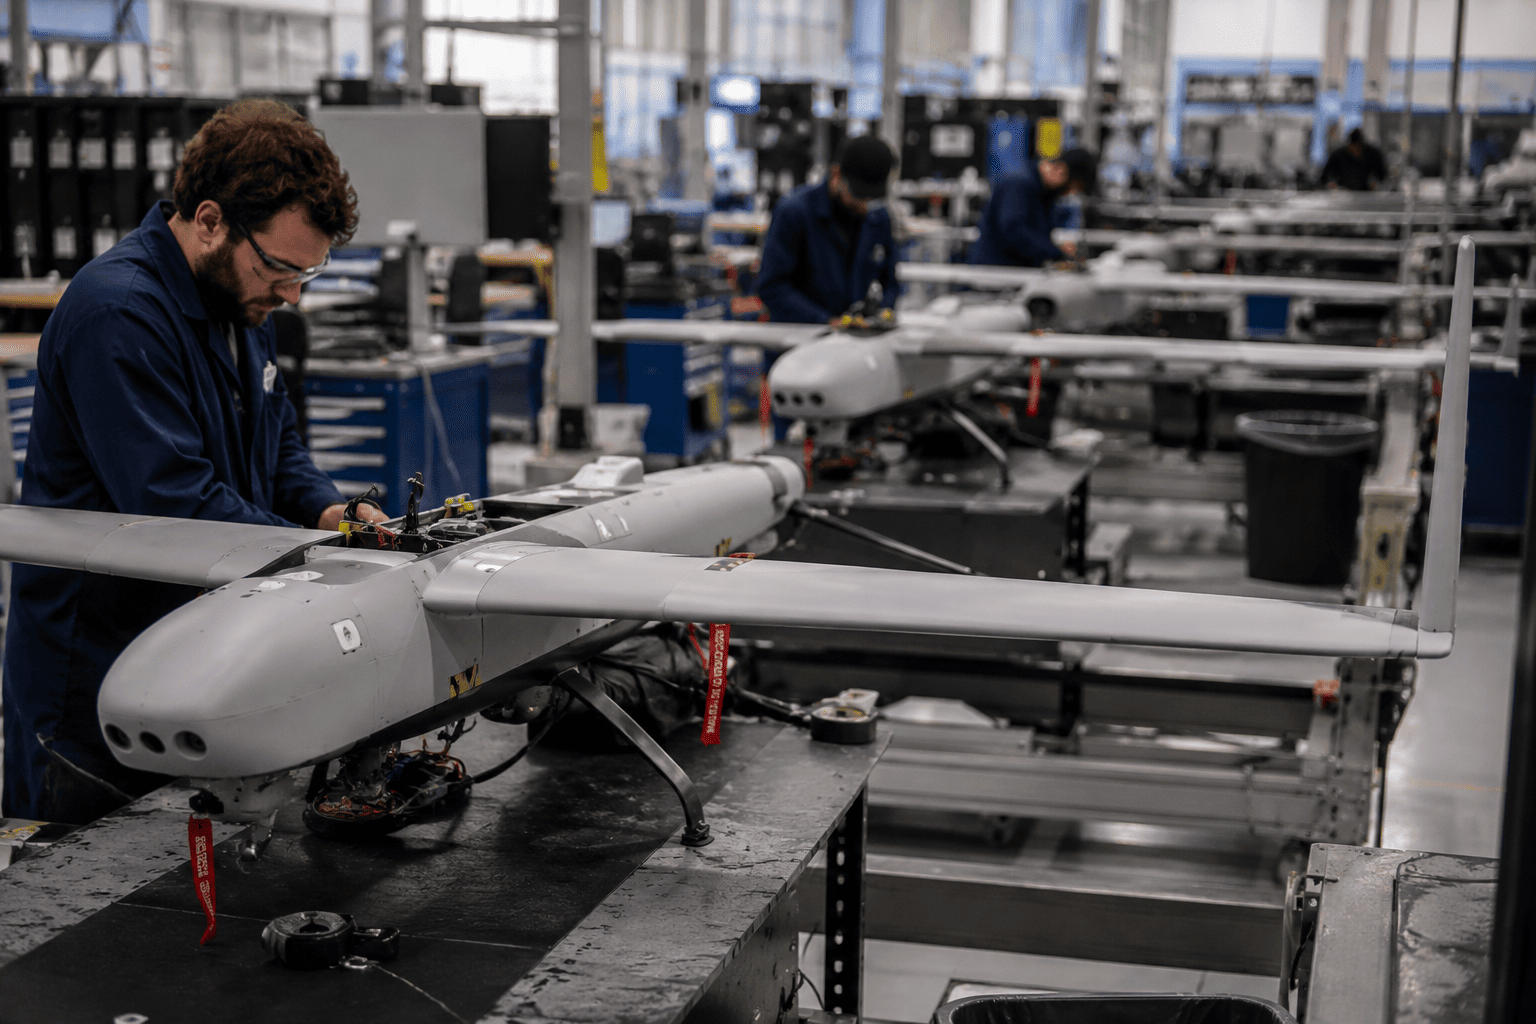
AeroVironment (NASDAQ: AVAV) shares gained more than 3% in Wednesday's trading after the defense contractor reported fiscal first-quarter results that showed solid revenue growth and a record backlog. The stock had fallen sharply from its October 2024 peak of $417 to around $140, but the latest earnings report may signal a turning point.
Strong quarterly performance
For the first quarter of fiscal 2027, AeroVironment reported revenue of $480.5 million, up 6% year-over-year. The growth was driven by a $15.5 million increase in product sales and $10.3 million in service revenue. The company's Autonomous Systems segment, which includes its drone offerings, generated over $346 million in sales, reflecting continued strong demand for unmanned systems in modern warfare.

The Space, Cyber, and Directed Energy (SCDE) segment contributed $134.5 million in revenue. Gross margins improved to 31%, supported by product revenue, though partially offset by the services segment. Notably, the operating loss narrowed significantly to $10.9 million from $69.3 million in the same period last year.
CEO Wahid Nawabi highlighted the company's strategic focus: "Our customers are continuing to field autonomous capabilities at increasing scale, and our priority is expanding manufacturing capacity across our sites and strengthening our supply chain."
Backlog and contract wins
AeroVironment's backlog reached $1.5 billion, up from $1.2 billion in the previous quarter. The company also announced a $468 million contract to produce high-energy laser weapon systems for counter-drone missions under the Army Enduring-High Energy Laser (E-HEL) program. Other notable contracts include $500 million for precision strike and defensive systems, $464 million for space and directed energy, and $117 million for uncrewed aircraft systems.
These wins underscore the growing importance of cost-effective drone and counter-drone technologies in modern defense budgets, a trend that has also benefited other defense tech firms. For context, similar momentum can be seen in the broader AI and defense supply chain, as highlighted by CoreWeave's recent backlog surge.
Outlook and analyst expectations
Management expects continued revenue growth and improved profitability. The company now projects annual revenue between $2.12 billion and $2.22 billion, with adjusted EBITDA in the range of $305 million to $325 million. According to Yahoo Finance, analysts anticipate revenue to rise 10.8% this year to $2.19 billion, followed by 15% growth to $2.53 billion in the next fiscal year.
Technical analysis and key levels
From a technical perspective, AVAV stock has been in a strong downtrend but is now sitting at a crucial support level around $134, which has held multiple times since June. The stock has formed a triple-bottom pattern, with a neckline at $207, its highest point on August 14. If buyers step in, the initial upside target is the psychological $200 level, roughly 35% above current prices.
Investors may also be watching broader defense and AI-related names for similar setups. For instance, AMD's recent rally reflects growing demand for AI infrastructure, while Dell's record high underscores the strength in AI-driven hardware.
While the fundamental picture appears improving, the stock remains volatile, and traders should watch for confirmation of a breakout above the $200 resistance level.
This article is for informational purposes only and does not constitute financial advice.

