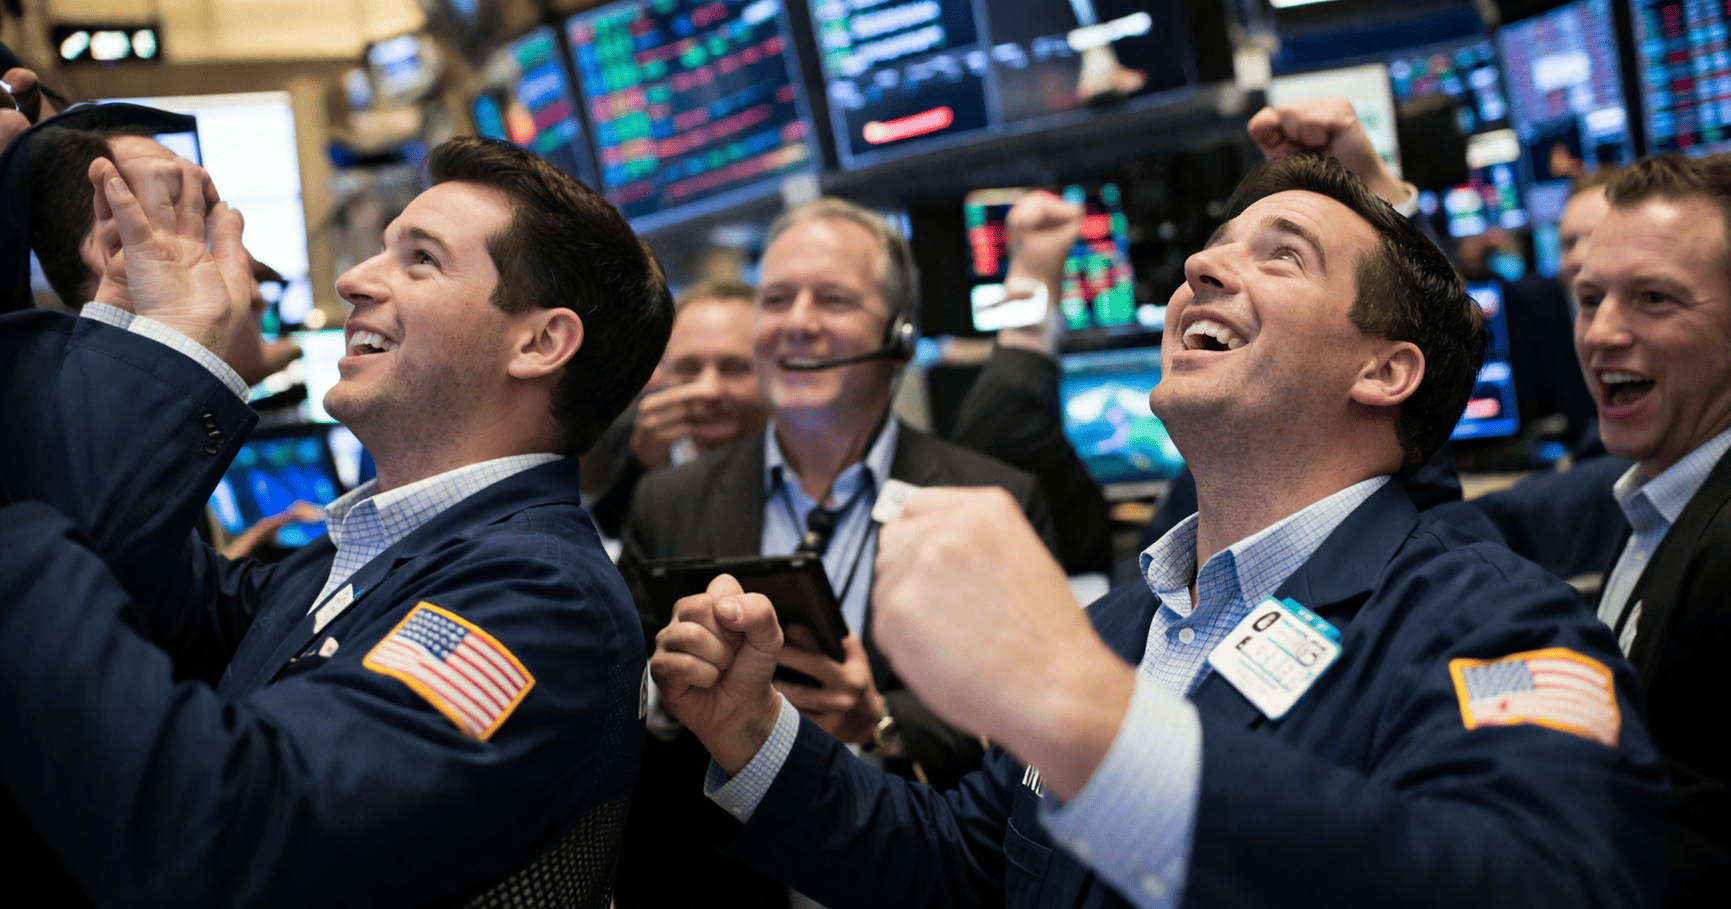
U.S. equities finished the session firmly in positive territory on Friday, propelled by a softer-than-anticipated September employment report that dampened expectations for another Federal Reserve rate increase at the upcoming October policy meeting.
The Dow Jones Industrial Average advanced 260 points, or 0.51%, while the S&P 500 climbed 0.76% and the Nasdaq Composite surged 1.19%. During the trading day, the Nasdaq briefly set an intraday record before giving back some gains as Treasury yields rebounded from their initial post-data dip.

Despite the strong close, the Dow and the S&P 500 still ended the week lower, while the Nasdaq extended its winning streak, marking its fifth weekly gain in six weeks.
Labor Market Weakness Fuels Rate Speculation
The U.S. economy added just 29,000 jobs in September, sharply below the 84,000 consensus estimate from Dow Jones and the 90,000 forecast in a Reuters poll. The unemployment rate ticked up to 4.2% from 4.1%, and payroll figures for the prior two months were revised downward, reinforcing signs of a cooling labor market.
According to CME FedWatch data, traders raised the probability of the Fed holding rates steady at its October meeting to 77%, up from roughly 76% the previous day. Expectations for at least a 25-basis-point hike fell to 22.7%, down from 24.4% a day earlier and 64.2% a week ago.
Treasury yields initially declined following the jobs report but later recovered, which tempered the equity rally. The data added to a week of mixed economic signals, including resilient activity and slower-than-expected inflation, along with cautious comments from Fed officials.
Tech and Rate-Sensitive Sectors Lead Gains
Technology stocks were among the best performers as investors rotated into riskier assets. Nvidia shares hit an all-time high for the first time since May, while CrowdStrike, Palo Alto Networks, and AMD also reached record levels. Megacap names like Nvidia and Tesla provided significant support to the S&P 500, with Tesla's advance lifting the consumer discretionary sector, the strongest of the 11 major S&P sectors.
Rate-sensitive areas also rallied. The S&P 500 real estate index gained about 1%, and the small-cap Russell 2000 rose roughly 1%, its biggest daily advance in a month.
Weekly Performance and Notable Decliners
For the week, the Dow fell about 1.3% and the S&P 500 slipped 0.2%, while the Nasdaq added roughly 0.5%. Both the Dow and the S&P 500 recorded their fourth weekly decline in five weeks, whereas the Nasdaq posted its fifth weekly gain in six weeks.
Outside the tech rally, Nike shares dropped after the sportswear giant forecast a sharp decline in annual revenue, citing weakness in China, and announced job cuts and a reorganization of its global business divisions. Data storage stocks also struggled: Western Digital and Seagate Technology were among the weakest performers in the S&P 500 technology index, following a report that Toshiba plans to double its production capacity for hard disk drives used in AI data centers by fiscal 2027.
Oil prices pulled back on reports that European countries were considering releasing strategic fuel reserves, providing additional support to equities.
This article is for informational purposes only and does not constitute financial advice.

