Rocket Lab (RKLB) shares have recovered from their recent lows, climbing back to around $70 after touching $60 earlier this month. The move has caught the attention of technical traders because the stock has carved out a double-bottom formation, a pattern that often precedes a sustained advance.
Technical setup points to a potential rebound
The daily chart shows RKLB bouncing twice from the $60 level, a floor that held in both July and August. The pattern's neckline sits at $86.45, the high reached on August 10. That level also aligns with the 78.6% Fibonacci retracement drawn from November's low to this year's peak, adding confluence to the setup.

Momentum indicators are mixed but leaning constructive. The Relative Strength Index has been grinding higher, and the stock is testing the Supertrend indicator from below. However, RKLB remains under its 50-day moving average, so the recovery is not yet confirmed. A push above the $86 neckline would mark a roughly 25% gain from current levels, while a close below $60 would negate the bullish thesis and open the door to the $50 psychological zone.
Fundamentals support the bullish case
Rocket Lab's operating performance has been strong. Second-quarter revenue rose 62% year over year to $234 million, outpacing SpaceX's space revenue growth of 22.25% over the same period. The company's backlog reached a record $2.36 billion, up 137% annually, driven by contracts for its Electron, HASTE, and Neutron launch vehicles. In the second quarter alone, Rocket Lab booked $437 million in new launch contracts.
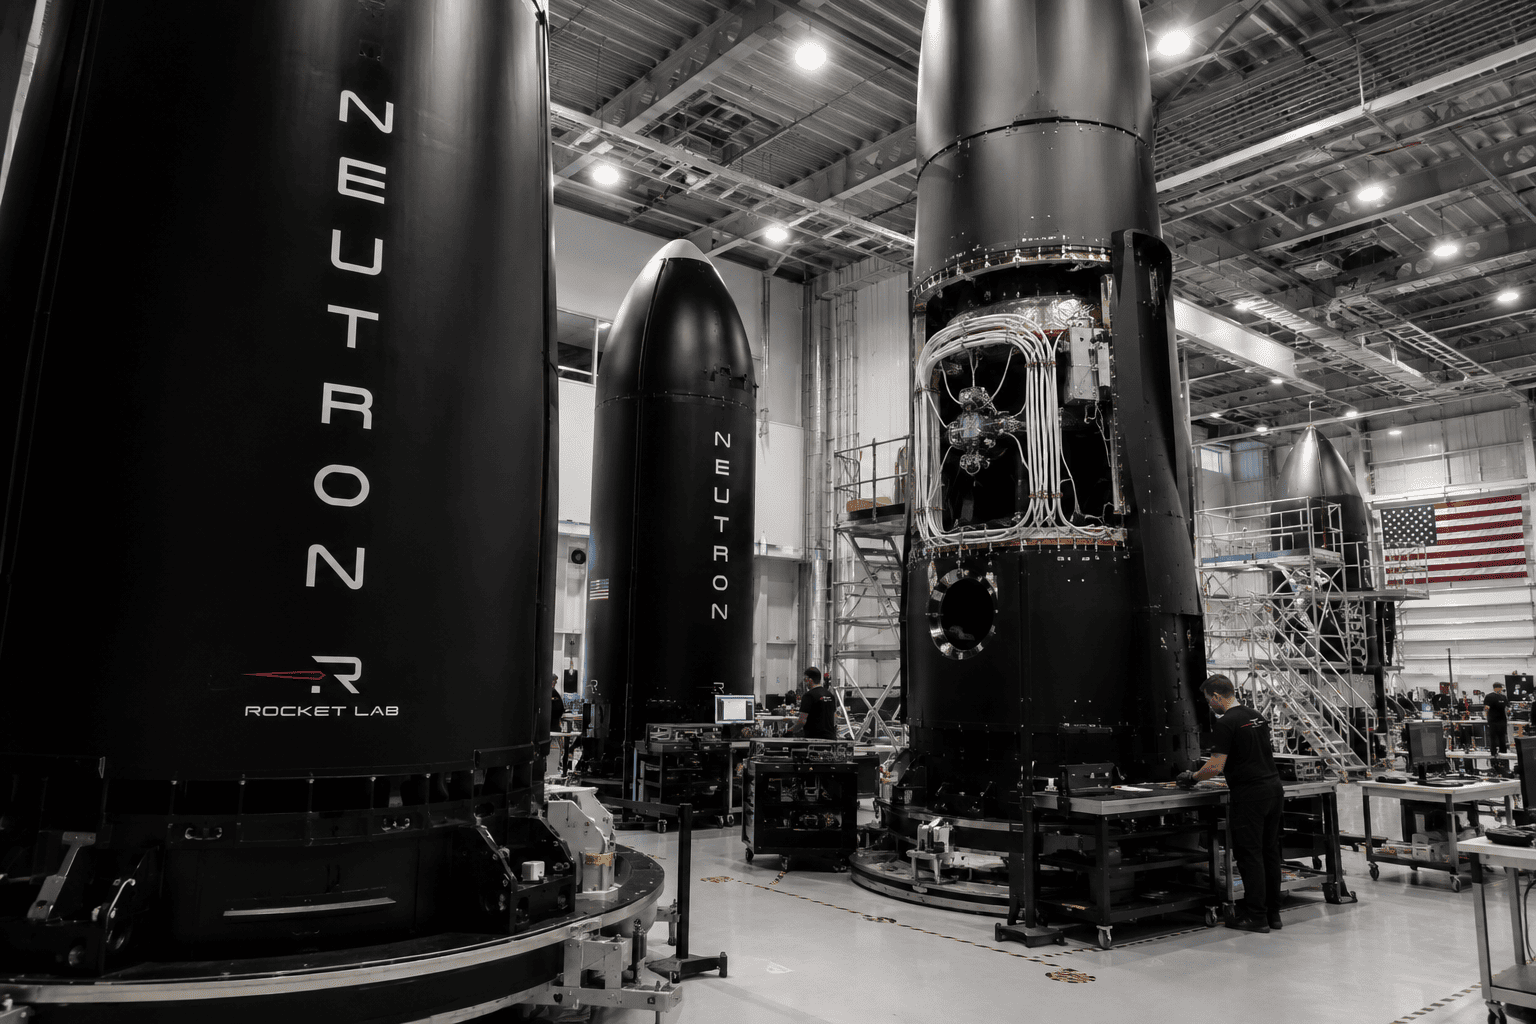
Electron, the company's current workhorse, carries payloads of 300 to 320 kilograms. The upcoming Neutron rocket is designed for much heavier loads of about 13,000 kilograms, and its first launch is targeted for late this year or early next year. Analysts expect annual revenue to grow 60% to $958 million this year and to $1.36 billion next year.
The proposed acquisition of Iridium could add further scale. Iridium operates with a 47% EBITDA margin and a 10% net income margin, which would contribute meaningfully to profitability. Analysts covering Iridium project revenue of $938 million this year and $995 million next year.
Analyst sentiment and risks
Wall Street remains largely positive. Cantor Fitzgerald's Andres Sheppard reiterated an overweight rating on Monday, and Raymond James' Brian Gesuale initiated coverage with an outperform rating. Still, investors should weigh several risks. Neutron is an unproven product, and the Iridium deal, like many mergers, may not deliver the expected synergies. Execution on both fronts will determine whether the technical pattern translates into a lasting uptrend.
This article is for informational purposes only and does not constitute financial advice.

