Lockheed Martin's stock has been under pressure this year, dropping roughly 20% from its March peak of $683 to the current $548. The decline reflects growing concerns about political headwinds and intensifying competition in the defense sector. As the company prepares to report third-quarter earnings, investors are closely watching for signs of sustained weakness.
Political Uncertainty Weighs on Defense Spending
A key factor behind the selloff is the upcoming midterm elections. Polls indicate a strong likelihood of a Democratic victory in the House, with odds of a Senate flip also rising on prediction markets like Polymarket and Kalshi. This political shift could threaten the defense budget expansion that President Trump has championed, aiming to increase spending from $1 trillion to $1.5 trillion.
Even with Republican control of Congress, Trump has struggled to secure the additional funding. Tensions between Defense Secretary Pete Hegseth and lawmakers have further complicated matters, and Congress has yet to approve the nearly $100 billion in supplementary funding requested to replenish munitions used in the Iranian conflict.
Anduril's Low-Cost Interceptor Threatens Market Share
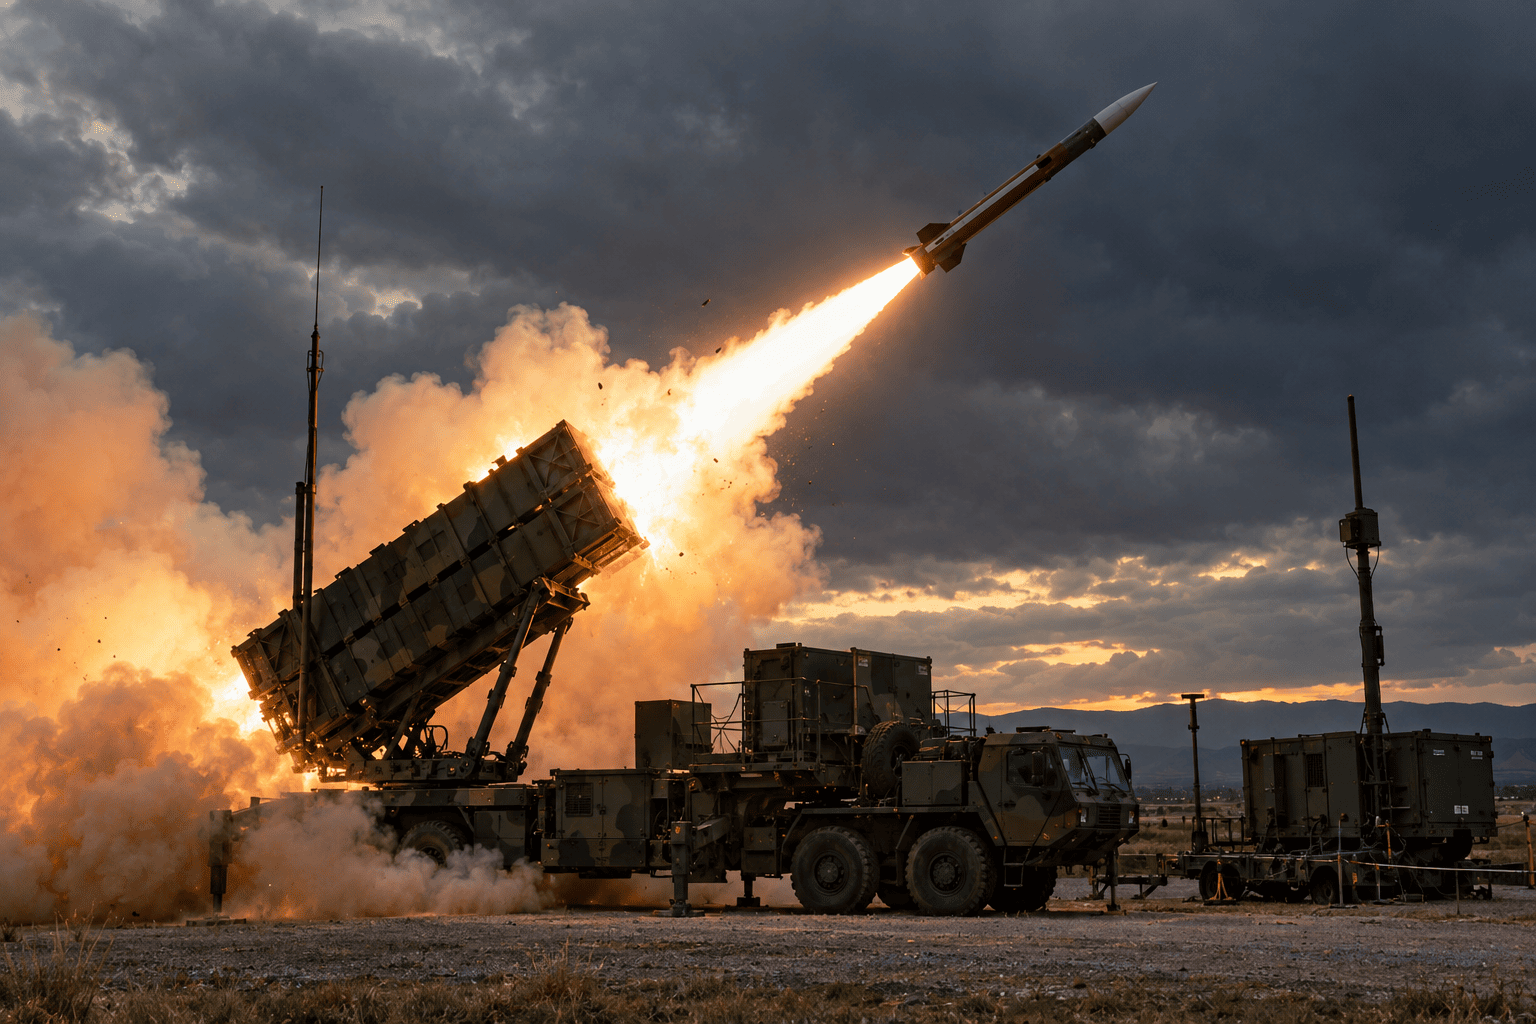
Beyond politics, Lockheed Martin faces a competitive challenge from Anduril, a startup founded by Palmer Luckey, which has ties to the Trump administration. Anduril, now valued at over $60 billion, is developing a new missile interceptor called Steelfin that promises to be significantly cheaper and easier to produce than the Patriot and THAAD systems. Steelfin is expected to cost about a third of current Patriot missiles and will be compatible with existing launchers.
If Steelfin gains traction, it could erode Lockheed Martin's dominance in the missile defense market, a segment that has been a reliable revenue driver for decades. The broader shift toward more agile and cost-effective defense solutions, driven by startups and European competitors, adds another layer of risk to Lockheed's long-term growth prospects.
Earnings Preview and Technical Outlook
Investors are now looking ahead to Lockheed's upcoming earnings report, scheduled for this week. Analysts expect revenue to rise 9.9% year-over-year to $20.4 billion, with earnings per share climbing to $7.52 from $6.95 in the same period last year. These figures will provide crucial insight into how the company is navigating current challenges.
From a technical perspective, the stock has been forming a head-and-shoulders pattern, a classic bearish reversal signal. The recent rebound from the $496 support level, which coincides with the 61.8% Fibonacci retracement, has stalled, and a breakdown below this pattern could trigger a move back toward that key support. The $496 level has acted as a floor multiple times this year, but a decisive break could open the door to further declines.
As the political landscape evolves and competitive pressures mount, Lockheed Martin's ability to maintain its market position and financial performance will be closely scrutinized. The upcoming earnings report and the midterm elections are likely to be pivotal catalysts for the stock in the near term.
This article is for informational purposes only and does not constitute financial advice.