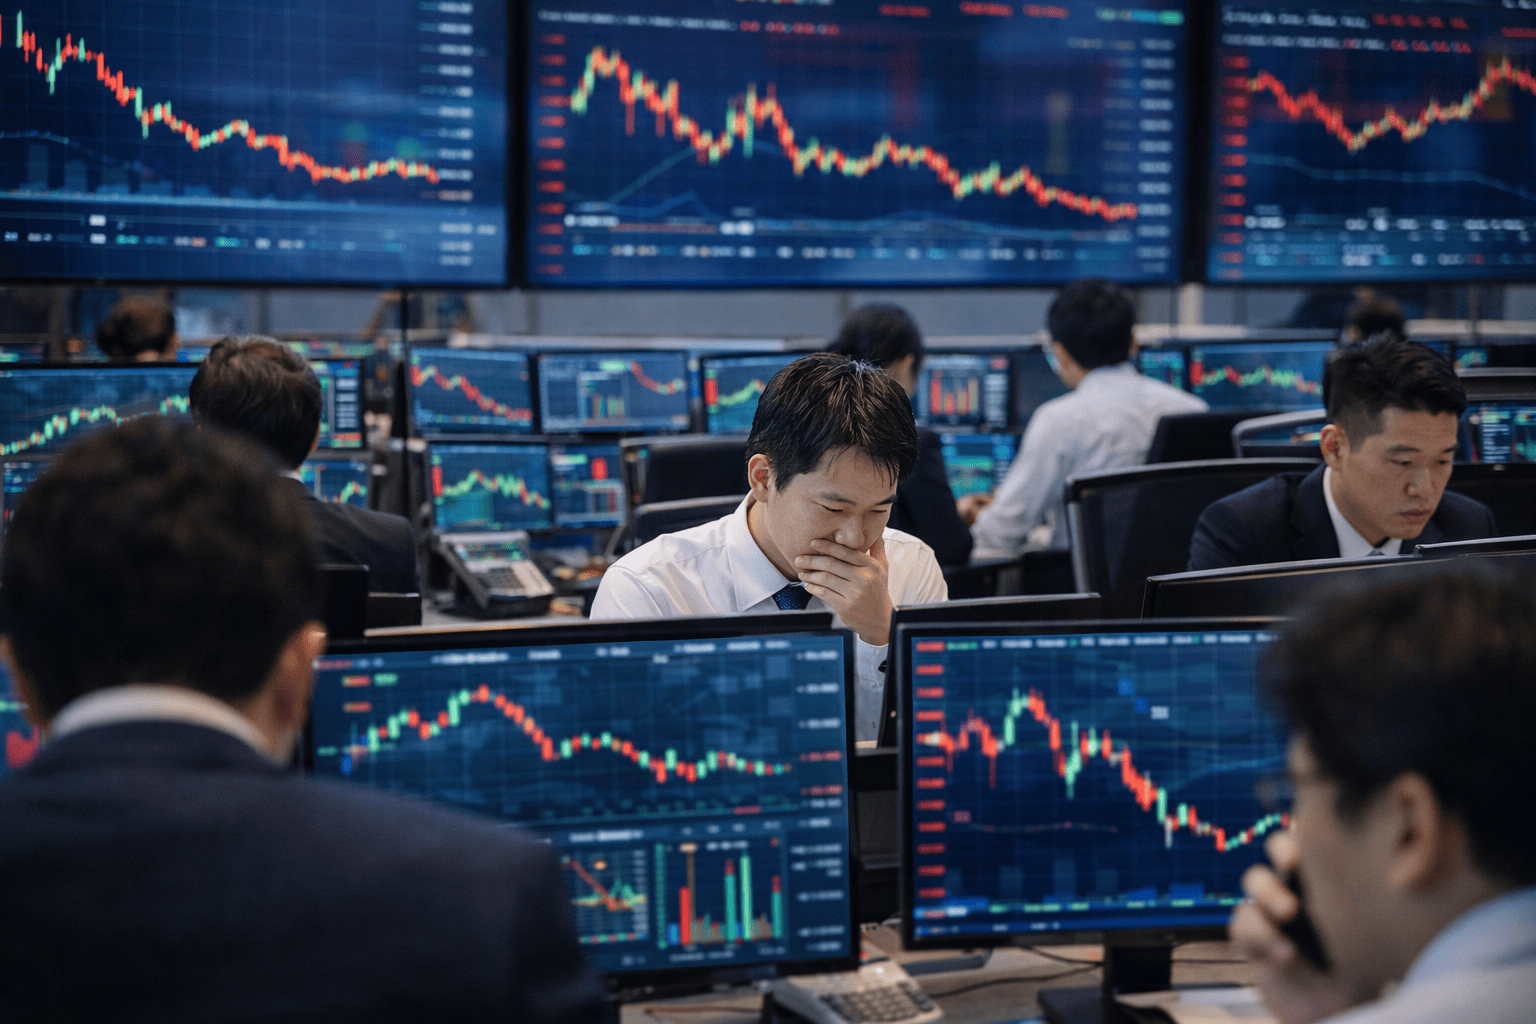
Asian equities faced renewed selling pressure on Monday as a fresh climb in oil prices and global bond yields reignited concerns over how long richly valued technology stocks can withstand higher borrowing costs.
South Korea bore the brunt of the selloff after returning from the Chuseok holiday, with the KOSPI dropping sharply as foreign investors trimmed exposure to semiconductor heavyweights. Samsung Electronics and SK Hynix both fell more than 4% in early trading, while institutional and foreign investors were net sellers, though retail buyers stepped in to provide some support.

Japan’s Nikkei 225 proved more resilient, trading near flat to modestly higher as chip-related shares and a weaker yen helped offset the pressure from rising yields. Advantest, SoftBank Group, and Disco were among the early gainers, cushioning the index from the global rates shock.
The divergence between the two markets highlights the varying degrees of holiday catch-up risk. The KOSPI had entered the break with momentum, closing Wednesday at 7,080.92, up 0.9%, following a rebound in AI and memory-chip shares. Monday’s decline appears partly as an adjustment to the rise in global bond yields while Seoul was closed.
Kiwoom Securities strategist Han Ji-young told MoneyToday that investors are likely to keep a close eye on the 7,000 level this week, with US employment figures, Korean export data, and Micron earnings providing the next tests for semiconductor sentiment.
Brent crude climbed about 2% toward $106.50 a barrel after US President Donald Trump rejected an Iranian proposal to reopen the Strait of Hormuz, though discussions are said to continue. Oil’s September gain now stands at roughly 18%, adding to inflationary pressures.
Meanwhile, markets are pricing about a 66% chance of another Federal Reserve rate increase in October, while the US 30-year Treasury yield traded near 5.52%, close to its highest since 2004. Bank of America rates strategist Mark Cabana noted in a market update that the bond repricing reflects a major shift in expectations for the Fed, with elevated yields likely to remain a key source of volatility.
Elsewhere, the CSI 300 fell about 1.4%, and MSCI’s Asia-Pacific index outside Japan declined. US equity futures also traded lower, while European futures edged higher.
This article is for informational purposes only and does not constitute financial advice.

