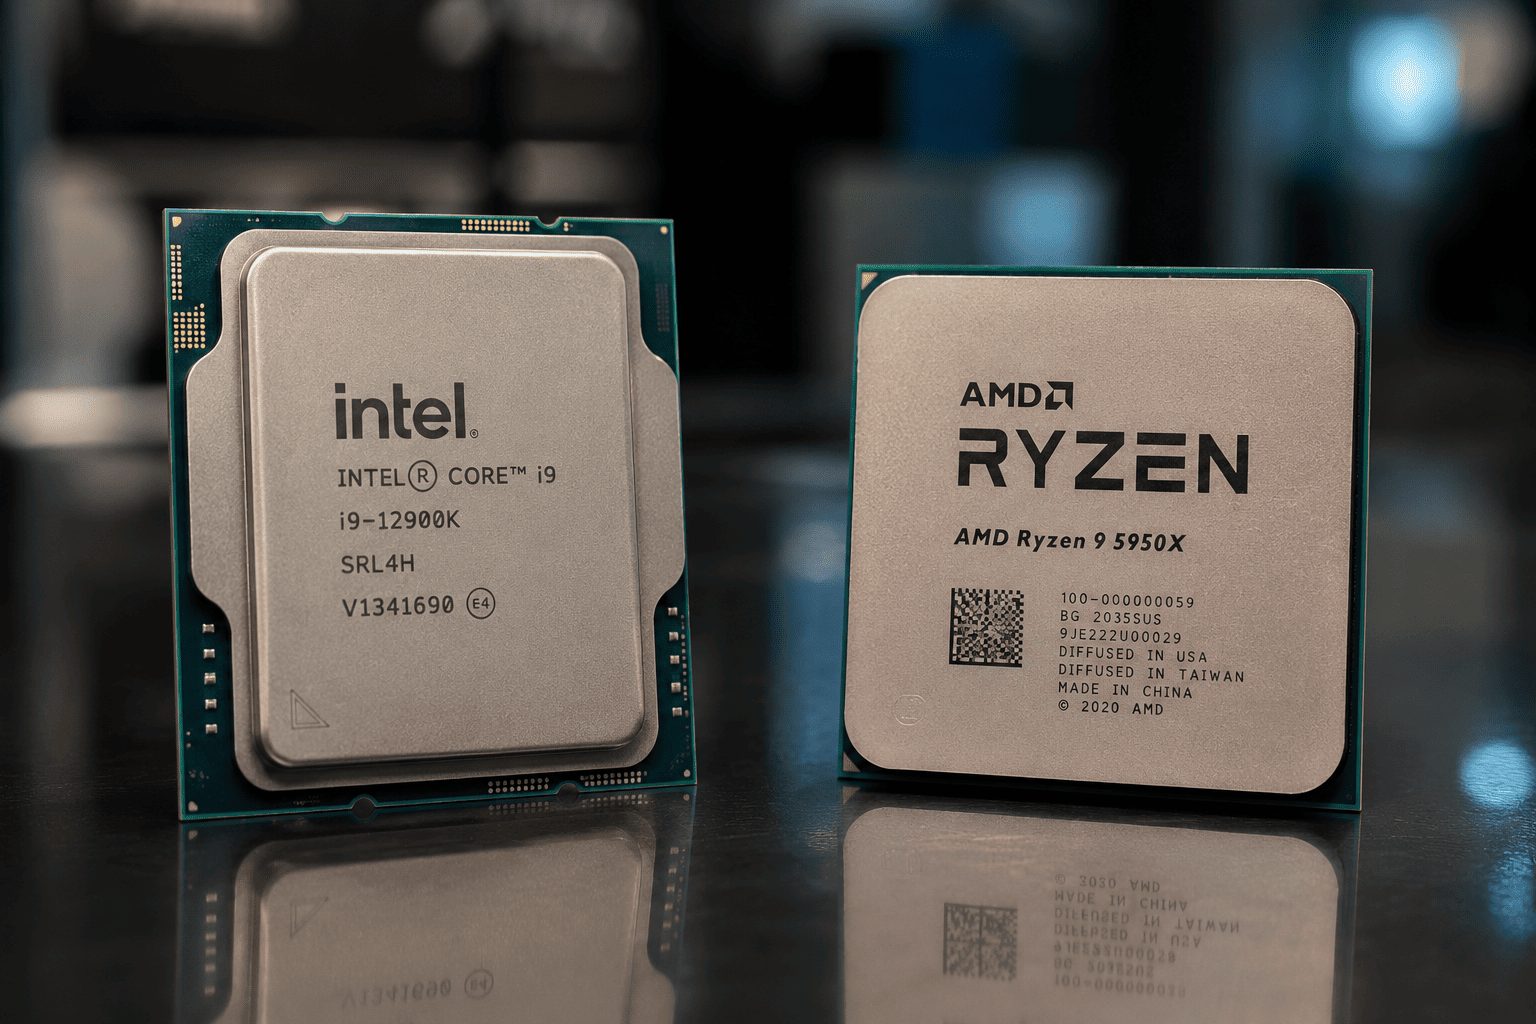
Intel and AMD shares rallied on Wednesday, driven by a mix of company-specific developments and broader optimism about the semiconductor sector's long-term growth prospects.
Intel rose approximately 4.5% following a Reuters report that South Korea's SK Hynix is in discussions to potentially manufacture memory chips on US soil, possibly at Intel's planned Ohio facility. The talks, according to sources, could involve leasing part of the Ohio fab or forming a joint venture with Intel and major cloud providers to secure memory supply. For Intel, such a deal would bolster its foundry business as it seeks to regain ground in the industry. It would also align with US government efforts to expand domestic chip manufacturing amid surging AI and data-center demand. However, Reuters noted that potential opposition from the South Korean government could complicate an agreement. SK Hynix stated it is reviewing various options but has not finalized anything with any specific company.

AMD also gained about 4%, extending its recent rebound after Piper Sandler reaffirmed an Overweight rating and a $600 price target. Analyst David O'Connor, following AMD's pre-quiet period call, indicated that CPU and GPU product ramps are on track, with demand exceeding supply. He noted that current supply capacity supports existing guidance and leaves room for potential upside. The discussion covered key growth areas, including Helios servers, Venice CPUs, and high-bandwidth memory supply.
Adding to the positive sentiment, Bank of America analyst Vivek Arya projected the semiconductor industry's total addressable market (TAM) to reach $3.2 trillion by 2030, up from an estimated $1.7 trillion this year. Arya cited memory chips and data-center demand as primary growth drivers, alongside recoveries in automotive and industrial segments. He saw no signs of slowing in customer orders, long-term agreements, or chip pricing despite recent market volatility. Arya expects Micron, Intel, and equipment makers Lam Research and Applied Materials to lead the sector once momentum strengthens.
The rally comes amid lingering concerns about a potential slowdown in AI spending, which have weighed on chip stocks recently. However, Arya's analysis suggests limited near-term evidence of such deterioration. Investors are also watching broader market dynamics, as chip stocks rebound from earlier AI-driven selloffs.
For Intel, the potential SK Hynix partnership could be a significant step in its turnaround strategy. The company has been working to expand its foundry services and attract external customers. A deal with SK Hynix would not only bring revenue but also validate Intel's manufacturing capabilities. The reported talks have already sparked investor enthusiasm, though details remain fluid.
AMD's gains reflect confidence in its execution, particularly in the AI accelerator market where it competes with Nvidia. The company's roadmap, including the upcoming MI400 series, is seen as critical to capturing more market share. Piper Sandler's positive assessment reinforces the view that AMD is well-positioned to benefit from sustained demand for high-performance computing.
Looking ahead, the semiconductor sector faces both opportunities and challenges. While long-term demand projections are bullish, near-term volatility persists due to macroeconomic factors and AI investment cycles. Investors should monitor developments in US-China trade policies, memory pricing, and AI infrastructure spending. The BofA forecast provides a bullish backdrop, but execution remains key for individual companies.
As of Wednesday's close, Intel and AMD were among the top gainers in the semiconductor space, reflecting renewed investor confidence. The coming weeks will likely bring more clarity on the SK Hynix talks and AMD's product ramp progress.
This article is for informational purposes only and does not constitute financial advice.

