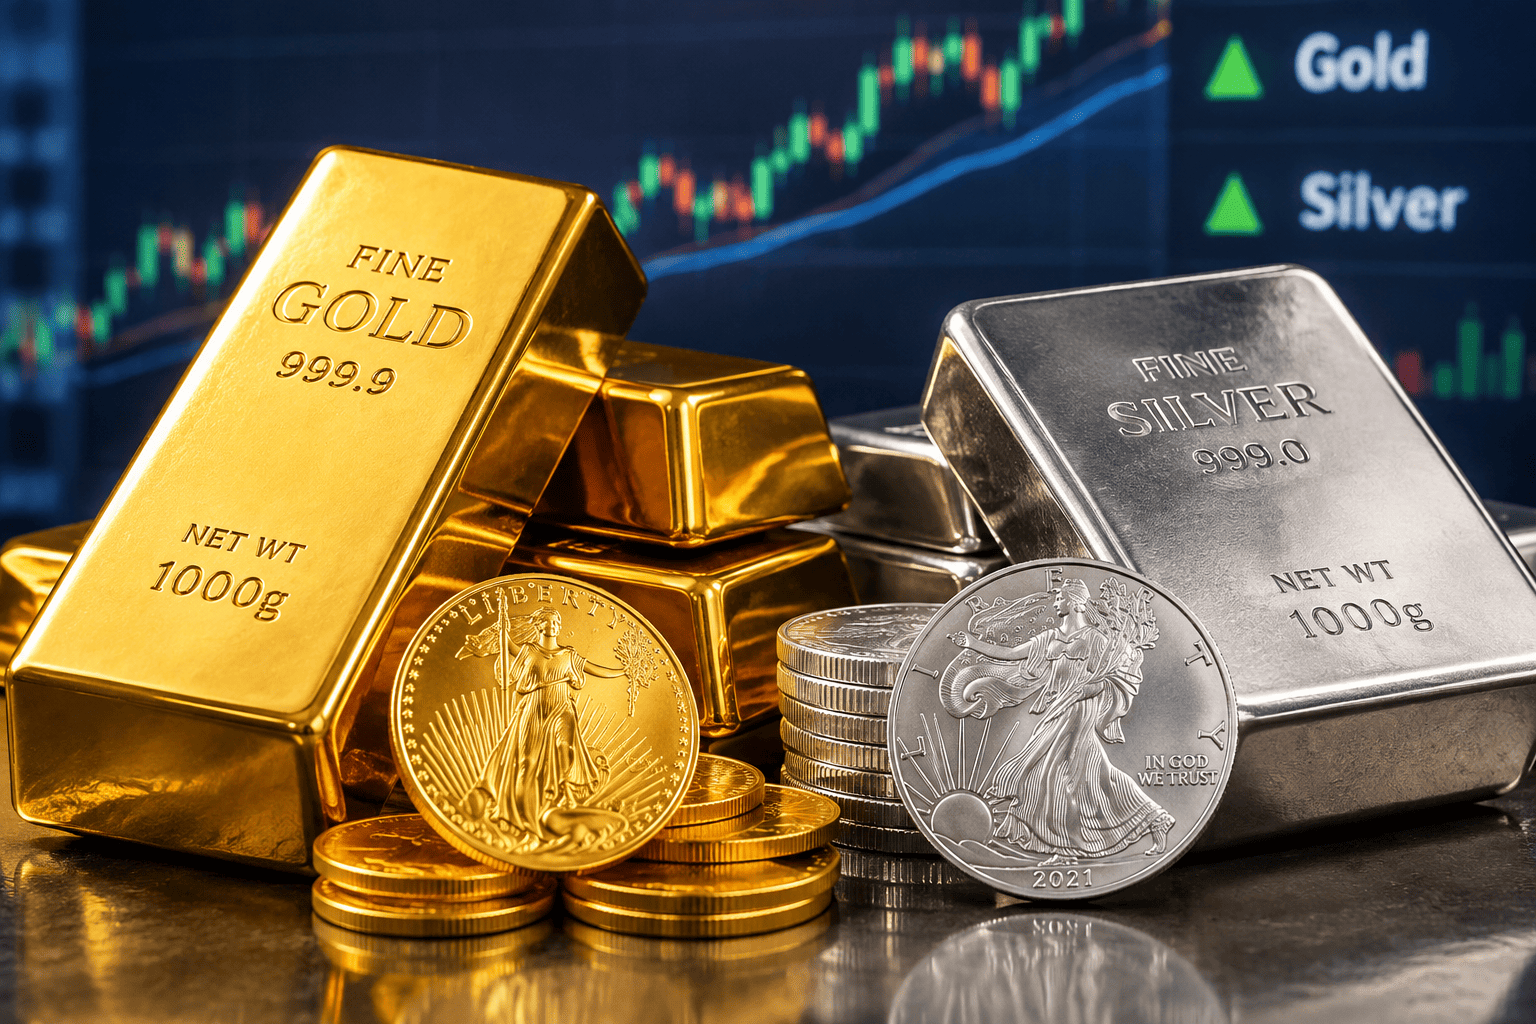
Gold prices have steadied near $4,160 an ounce even as billions of dollars continue to pour into bullion-backed exchange-traded funds, highlighting a growing disconnect between persistent investment demand and lackluster price momentum.
Spot gold traded around $4,161.67 in Asian hours, following a 6.6% decline in September—its worst monthly performance since June. Despite the price slump, US-listed gold ETFs attracted $3.8 billion in September, building on the $7.9 billion inflows recorded in August, according to MarketWatch.
ETF inflows signal long-term commitment
The contrast between robust ETF flows and weak price action suggests that long-term investors have not abandoned bullion. Amy Gower, head of metals and mining strategy at Morgan Stanley, told CNBC that ETF demand has remained unusually resilient even as markets anticipated and then experienced Federal Reserve tightening. She also pointed to central-bank buying, particularly from China, and noted that Morgan Stanley views $4,000 an ounce as a support level.
The selling pressure appears concentrated elsewhere. Gower explained that algorithmic and momentum funds, which had built positions during August's rally, have reversed those trades as technical signals deteriorated.
Softer inflation data offers limited support
Wednesday's US inflation report, which typically would bolster gold, provided only modest relief. The personal consumption expenditures price index rose 0.3% in August, below expectations, while core PCE increased 0.2%. Traders subsequently cut the probability of an October Fed rate increase to about 38%, down from more than 70% earlier in the week.
Despite this, gold struggled to build momentum. OCBC Group Research described the rebound as "not so convincing," arguing that softer inflation alone is insufficient while Treasury yields and energy prices remain elevated. This distinction matters because gold is now responding less to the next Fed meeting and more to conditions at the long end of the bond market.
Bond market remains the primary obstacle
Elevated Treasury yields increase the opportunity cost of holding a non-yielding asset like gold, while a stronger dollar makes bullion more expensive for overseas buyers. Peter Grant of Zaner Metals told Reuters that there are still "fairly significant headwinds for gold," citing high yields, dollar strength, and expectations for further Fed tightening.
Oil adds another layer of complexity. Brent crude eased to about $98 on Thursday but still gained roughly 14% in September, keeping longer-term inflation concerns alive even as near-term Fed expectations soften.
The paradox is uncomfortable for gold investors: the inflation uncertainty that would normally support bullion is also helping keep long-term bond yields high enough to suppress it.
This article is for informational purposes only and does not constitute financial advice.