General Motors (GM) shares tumbled more than 7% in premarket trading Tuesday, even after the automaker reported third-quarter earnings and revenue that topped Wall Street expectations. The selloff reflects investor concerns about escalating costs and a more cautious outlook for 2026, which overshadowed the stronger-than-expected quarterly performance.
The Detroit-based company posted adjusted earnings before interest and taxes (EBIT) of $4.1 billion, up 21.6% from the same period last year. Adjusted earnings per share came in at $3.70, surpassing the $3.63 consensus estimate compiled by LSEG. Revenue rose nearly 3% year over year to $50 billion, exceeding the $48.77 billion analysts had projected.
GM revises 2026 guidance
GM narrowed its full-year 2026 adjusted EBIT guidance to a range of $14.5 billion to $15.5 billion, compared with the previous $14 billion to $16 billion. The company also trimmed its adjusted earnings-per-share forecast to $12.75 to $13.75, from $12.00 to $14.00 previously. However, it raised its adjusted automotive free cash flow outlook to $11.5 billion to $12.5 billion, up from $9.5 billion to $11.5 billion.
The revisions present a mixed picture for investors. While the midpoint of the adjusted EBIT range remains unchanged, the improved cash flow forecast provides a positive counterpoint to rising expenses. GM now expects commodity inflation of approximately $2 billion, at the upper end of its earlier estimate of $1.5 billion to $2 billion. That figure includes logistics and dynamic random-access memory (DRAM) chip costs, which have been climbing significantly. The company also lowered its expected regulatory benefits to around $500 million from as much as $750 million.
North American margins improve
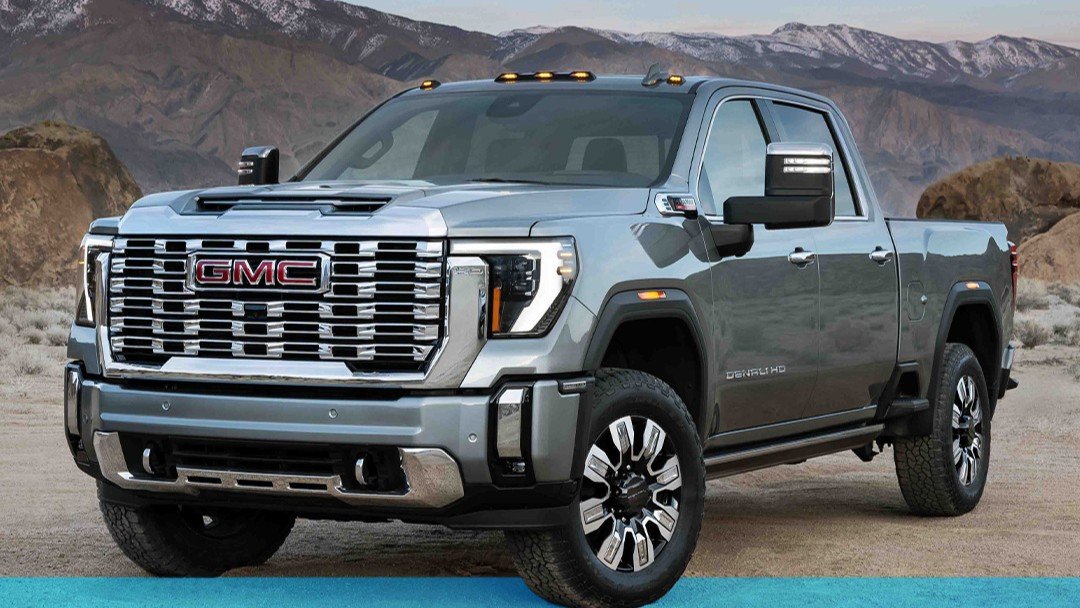
GM's North American profit margin expanded to 8.7% from 6.2% a year earlier, despite a decline in sales. The automaker attributed the improvement partly to a higher sales mix of large pickup trucks and fewer electric vehicles during the quarter. GM has been pulling back on EV sales following the Trump administration's withdrawal of support for the segment.
CEO Mary Barra said the company was working to sustain its performance despite rising costs. GM also announced a multiyear $20 billion share repurchase program, although it did not specify a timeline for the planned buybacks. The company has repurchased approximately $29.5 billion of its own shares since 2023.
The latest announcement signals a continued commitment to returning capital to shareholders as GM manages costs and adjusts its business strategy.
Investors focus on future earnings
JPMorgan analyst Rajat Gupta had warned before the results that investors would focus on revisions to GM's 2027 outlook rather than its quarterly performance. "Investor focus is likely to be on 2027 revisions and we don’t see results driving meaningful upside," Gupta said.
Despite the earnings beat, investors are assessing whether GM can sustain profitability and cash generation as inflation increases expenses. Its improved free cash flow outlook and buyback program offer support, but the revised guidance and higher projected costs remain important considerations for shareholders.
This article is for informational purposes only and does not constitute financial advice.