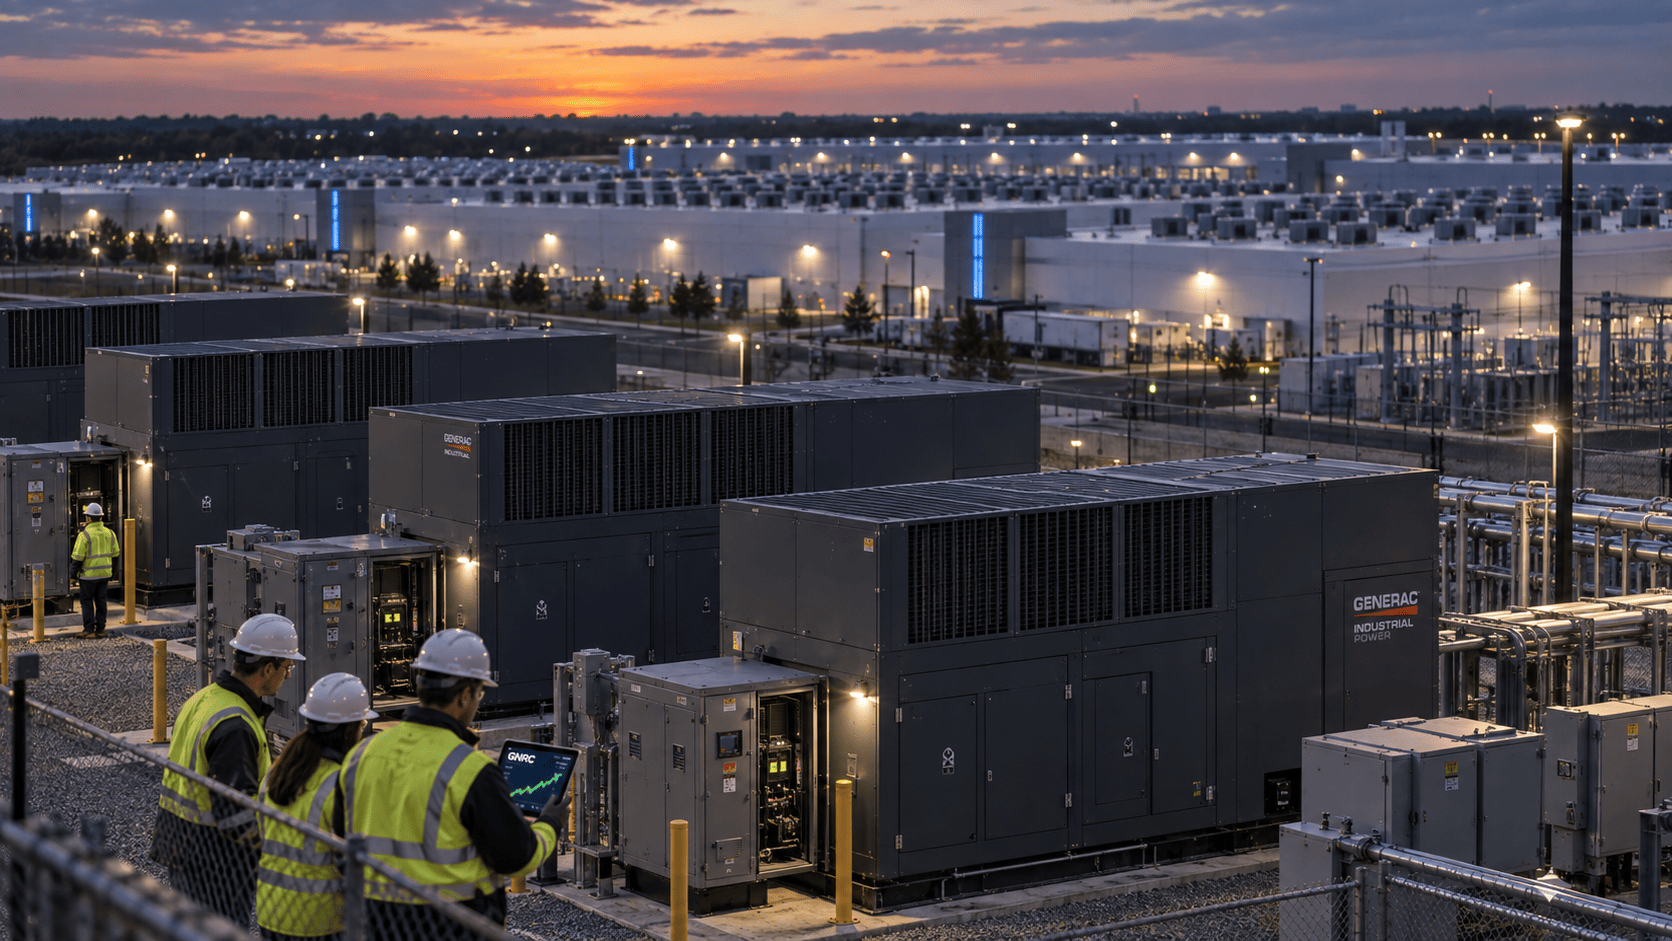
Generac Holdings (NYSE: GNRC) saw its shares jump roughly 34% in premarket trading Thursday after Amazon committed to a multi-billion-dollar agreement for backup generators to support its expanding data-center network. The deal, however, includes a provision that gives Amazon more than just equipment—it also grants the tech giant warrants to acquire a stake in Generac, creating a unique trade-off for existing shareholders.
Amazon's Commitment and Revenue Visibility
Under the agreement, Generac expects initial deliveries worth $2.4 billion across 2027 and 2028, with total payments tied to the broader relationship potentially reaching $8 billion. This is a significant boost for a company that generated $4.21 billion in total revenue in 2025. The scale of the order addresses a key question about Generac's ability to replenish its backlog beyond 2027, which had reached about $1.6 billion by late July. In the second quarter, commercial and industrial sales rose 29% to $556 million, partly driven by growing data-center revenue.

Cantor Fitzgerald called the Amazon agreement Generac's "most important data centre" development since its first hyperscaler win, maintaining an Overweight rating and a $333 price target. The firm argues that the deal provides far greater revenue visibility and gives Generac a marquee customer at the heart of the AI infrastructure boom.
The Catch: Warrants and Dilution
The unusual aspect of the agreement lies in the warrant structure. Amazon can acquire up to 1,693,745 Generac shares at an exercise price of $200.9266. Of those, 307,954 shares vested immediately, with the remainder vesting in stages as qualifying payments from Amazon rise toward $8 billion. If fully vested and exercised, the warrant would represent nearly 3% of Generac's outstanding shares.
This potential dilution is not a simple giveaway. The structure links Amazon's ownership upside directly to the amount of business it sends Generac. As the commercial relationship grows, so does Amazon's potential equity stake. Baird, which upgraded Generac to Outperform earlier this month, sees an "attractive risk reward" and points to large commercial and industrial generators as a new growth opportunity. The Amazon deal provides concrete evidence behind that thesis.
Concentration and Execution Risks
The deal also shifts the risk profile for investors. Jefferies had previously described Generac's hyperscaler push as a "moment of truth," and Amazon's commitment suggests the company has passed that test. However, success brings customer-concentration and execution risks. A larger share of future growth will depend on hyperscaler capital spending, Amazon's purchasing schedule, Generac's ability to deliver large generator programs, and continued data-center construction.
The warrant reinforces this relationship because Amazon's potential ownership rises alongside its commercial importance. That concentration could eventually matter as much as the headline revenue. Shareholders are effectively exchanging some potential future dilution for visibility into billions of dollars of hyperscaler spending.
Whether the rally proves justified will depend on how quickly those orders translate into earnings and whether Generac can leverage Amazon as a launchpad to win additional data-center customers. The market's initial reaction suggests optimism, but the long-term impact will hinge on execution and the evolution of the partnership.
This article is for informational purposes only and does not constitute financial advice.

