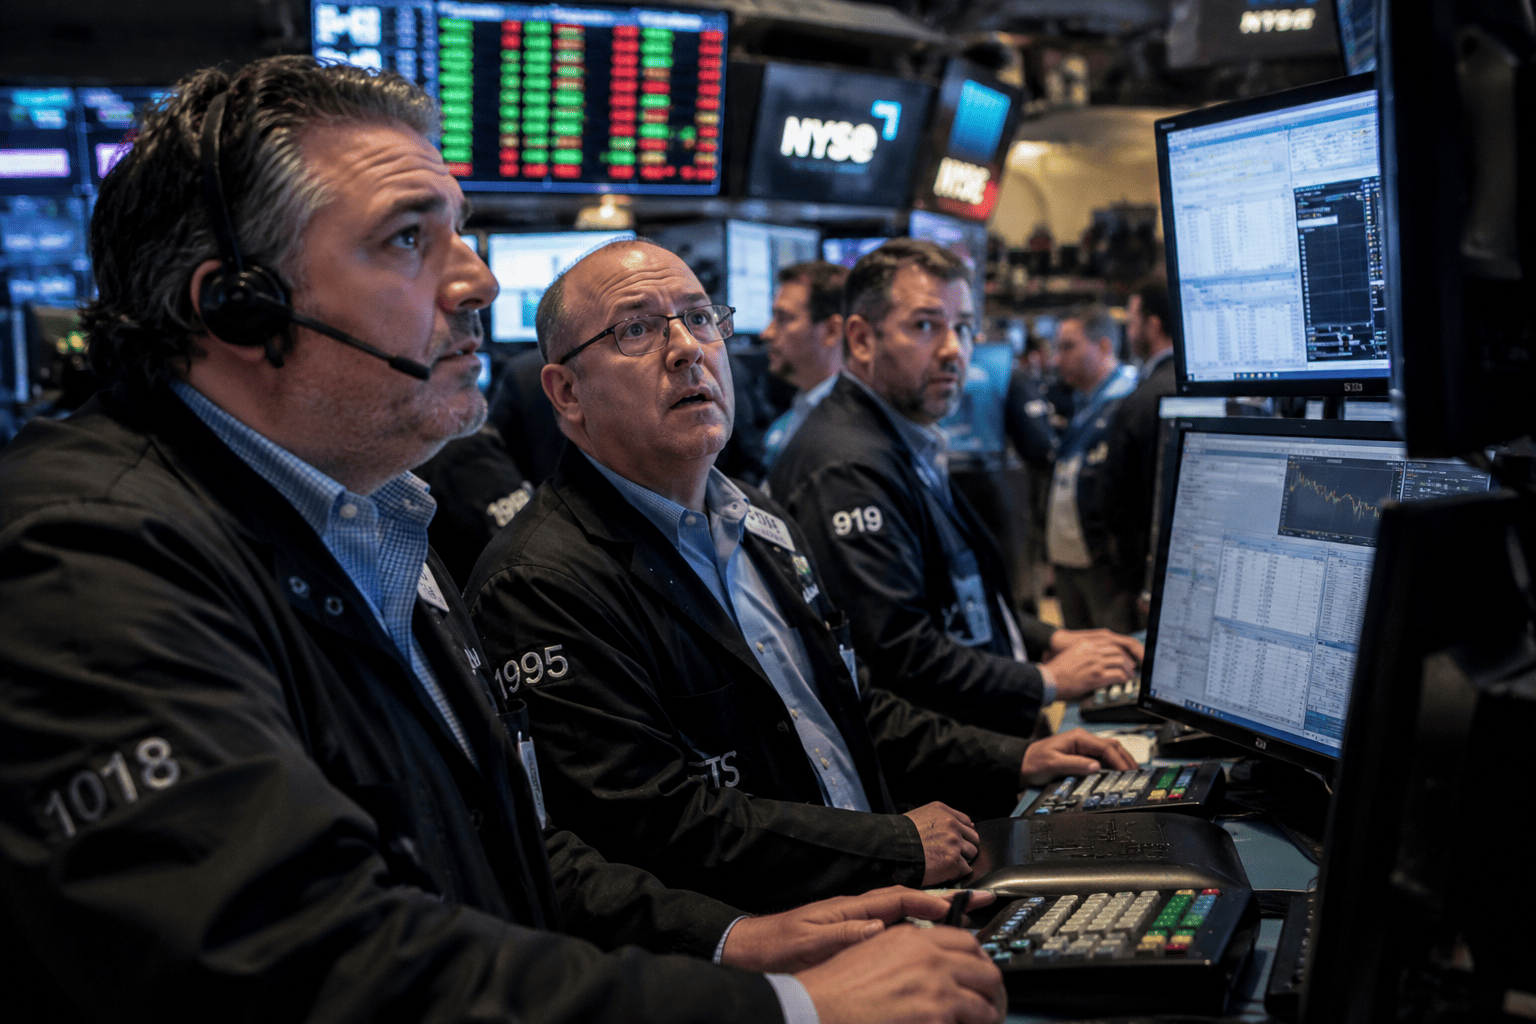
US stocks opened with little direction on Monday, as technology shares pulled back from recent peaks and investors weighed the persistence of elevated Treasury yields and firm oil prices against the outlook for Federal Reserve policy. The Dow Jones Industrial Average slipped about 98 points, while the S&P 500 edged up 0.2% and the Nasdaq Composite gained roughly 0.43%.
The muted start followed a robust session for tech stocks on Friday, when the Nasdaq reached a record high after softer-than-expected US jobs data dampened expectations for an October rate hike. That labor market report provided some relief to equities, but the broader market remains sensitive to the interplay between yields, energy costs, and central bank signals.

Tech shares cool after recent run
Chipmakers were among the notable laggards. Intel fell 2.4%, Micron Technology declined 0.83%, while Nvidia edged up 1.28% after hitting a record high on Friday. The pullback in semiconductors reflects profit-taking after a strong advance, with investors now turning attention to the upcoming earnings season.
Around 70% of the S&P 500's market capitalization is expected to report results by the end of October. Recent corporate optimism has helped US equities outperform global markets over the past six months, despite geopolitical risks and inflation concerns. Goldman Sachs analysts project median S&P 500 earnings growth of 9% year over year for the current quarter.
In individual movers, PTC surged 35.7% after Schneider Electric agreed to acquire the software firm in an all-cash deal valuing its equity at roughly $22.6 billion. RXO climbed 23% following C.H. Robinson Worldwide's agreement to buy the transportation broker for $5.8 billion in a stock-and-cash transaction. Cerebras Systems added 4.4% after OpenAI CEO Sam Altman described the chip designer as a close partner.
Treasury yields remain elevated
The benchmark 10-year Treasury yield hovered around 5.30% on Monday, while the 30-year yield stood near 5.66%. Both have reached multi-year highs in recent weeks as investors assess inflation risks, government finances, and heavy debt issuance. The Federal Reserve raised its overnight interest rate by 25 basis points last month, and the market will get more detail when the central bank releases minutes from its September meeting on Wednesday.
According to CME FedWatch data, traders currently see an 80% probability that the Fed will hold rates steady at its October meeting. However, expectations for a December hike remain elevated. Investors will also monitor September services-sector activity data due later Monday, including the Institute for Supply Management's services report.
Oil prices stay near $100
Oil remained a key focus as concerns over potential disruptions to Gulf oil infrastructure kept crude prices elevated. Brent crude futures slipped 0.3% to $101.88 a barrel, while West Texas Intermediate traded around $89.32, down about 1.93%. The recent rise in oil prices has added to worries that higher energy costs could sustain inflationary pressures and complicate the Fed's policy path.
US stocks entered October after a volatile week marked by a sharp rise in Treasury yields and a weaker-than-expected September jobs report. While the labor data reduced odds of an October rate increase and offered some support to equities, investors remain focused on the broader risks from higher yields, oil prices, and geopolitical uncertainty.
This article is for informational purposes only and does not constitute financial advice.

