US equities closed lower on Friday, with the Dow Jones Industrial Average dropping 1.25% (about 659 points) to 52,209.16, as rising oil prices and geopolitical concerns weighed on investor sentiment. The S&P 500 slipped 0.52% to 7,623.86, while the Nasdaq Composite edged down 0.21% to 25,955.34. Despite the day's losses, the Dow managed a 0.4% weekly gain, whereas the S&P 500 and Nasdaq each fell 0.5% and 0.7%, respectively.
Oil Surge on Middle East Tensions
Energy prices climbed sharply as renewed fears of conflict involving the US, Israel, and Iran raised the possibility of supply disruptions. West Texas Intermediate crude futures jumped 3.8% to settle at $103.34 per barrel, while Brent crude rose 3.25% to $116.85, its highest settlement since April. Reports that the US and Israel might be preparing new attacks on Iran, and Iran's stated readiness to retaliate, added uncertainty to the energy market outlook.
The energy sector hit a record high on Friday, bucking the broader market weakness. However, higher oil prices also stoked inflation concerns and potential pressure on consumer spending. University of Michigan data showed consumer sentiment slipped close to a record low in October, as rising prices linked to the conflict dampened households' economic outlook.
Broad-Based Declines Beyond Tech
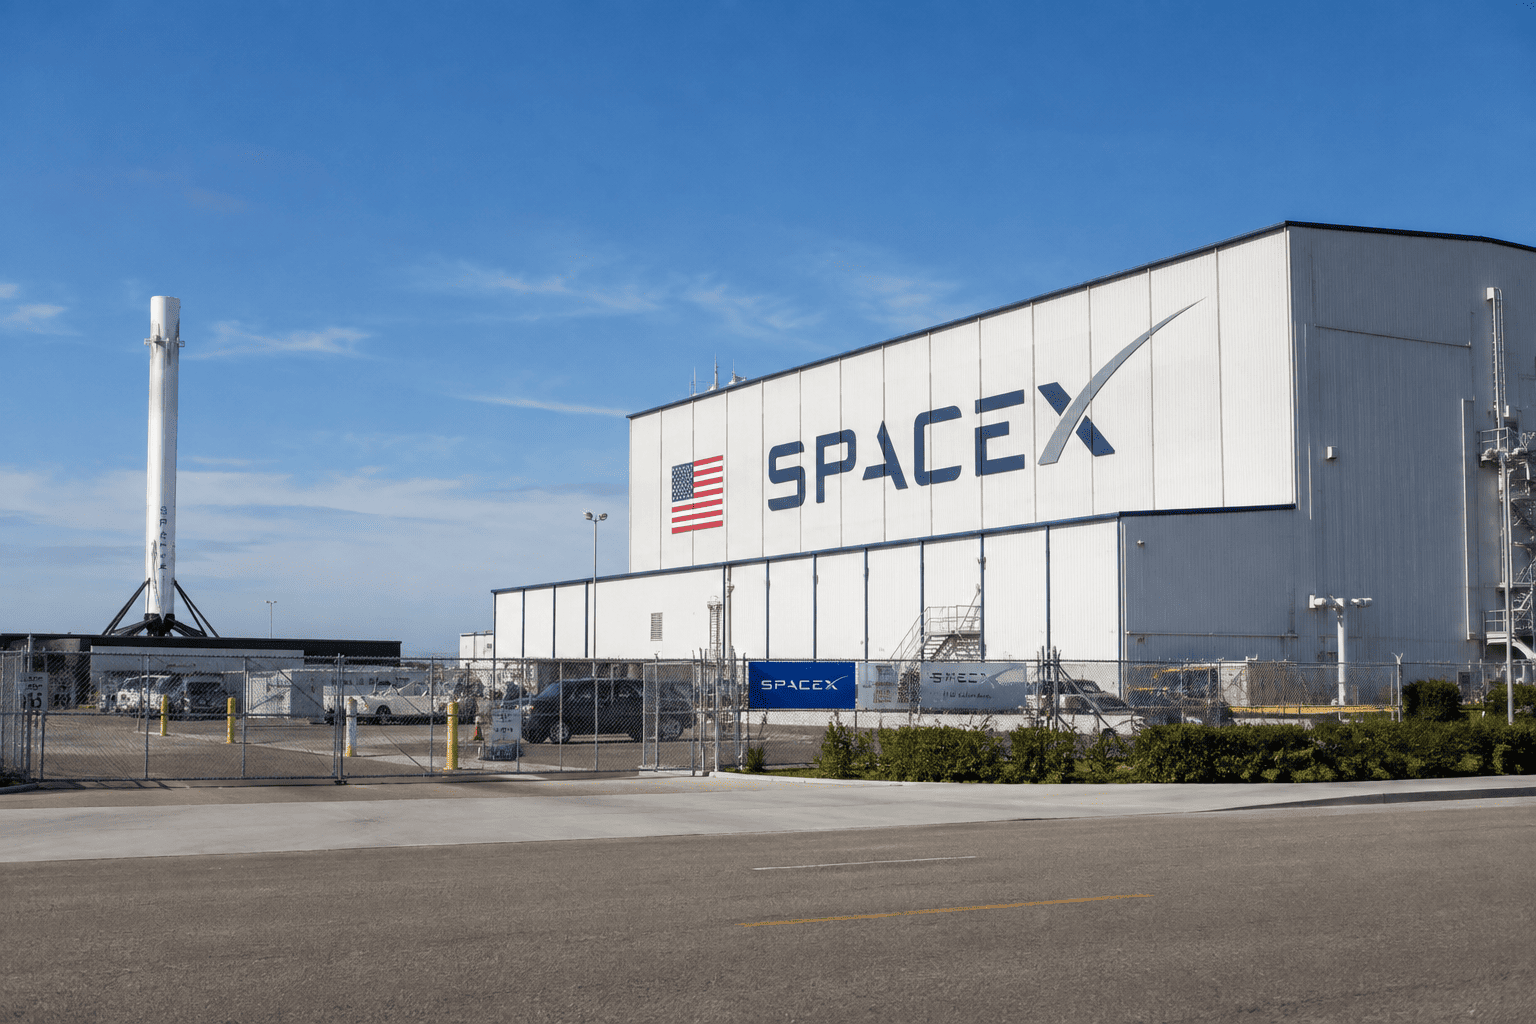
Selling pressure extended across consumer staples, utilities, healthcare, and financials. American Express fell more than 3% after announcing plans to cut about 5% of its global workforce, citing preparations for increased AI adoption. Caterpillar declined around 2%, and Goldman Sachs lost over 1%. Telecommunications stocks also weakened following a report that SpaceX is seeking access to thousands of cellular sites as it explores becoming a fourth nationwide wireless carrier.
Technology shares showed relative resilience after the previous session's sell-off. Microsoft edged higher, Micron Technology gained 2.5%, and Advanced Micro Devices rose 1.7%. Investors have been reassessing AI-related stocks amid concerns about the scale of borrowing needed to finance data centers and the potential impact of higher interest rates, though recent earnings have provided some support.
The 10-year US Treasury yield rose more than four basis points to around 4.999% on Friday, returning above the 5% level after briefly dipping below it a day earlier.
Fed Decision and Big Tech Earnings in Focus
Investors are bracing for a busy week, with about one-third of S&P 500 companies reporting quarterly results, including Alphabet, Microsoft, and Amazon. Their capital expenditure forecasts will be closely watched for signs of whether AI infrastructure spending will continue at its current pace. According to LSEG IBES data, S&P 500 companies are on track to increase earnings by more than 32% in the third quarter, supporting the market's gains this year.
The Federal Reserve is widely expected to hold interest rates steady at its Wednesday meeting, but investors will look for signals on whether policymakers could raise rates in December. Additionally, the November 3 US midterm elections, which will determine control of Congress, are also on the radar. Together, corporate earnings, interest-rate expectations, and geopolitical risks could shape the direction of US stocks in the coming week.
This article is for informational purposes only and does not constitute financial advice.