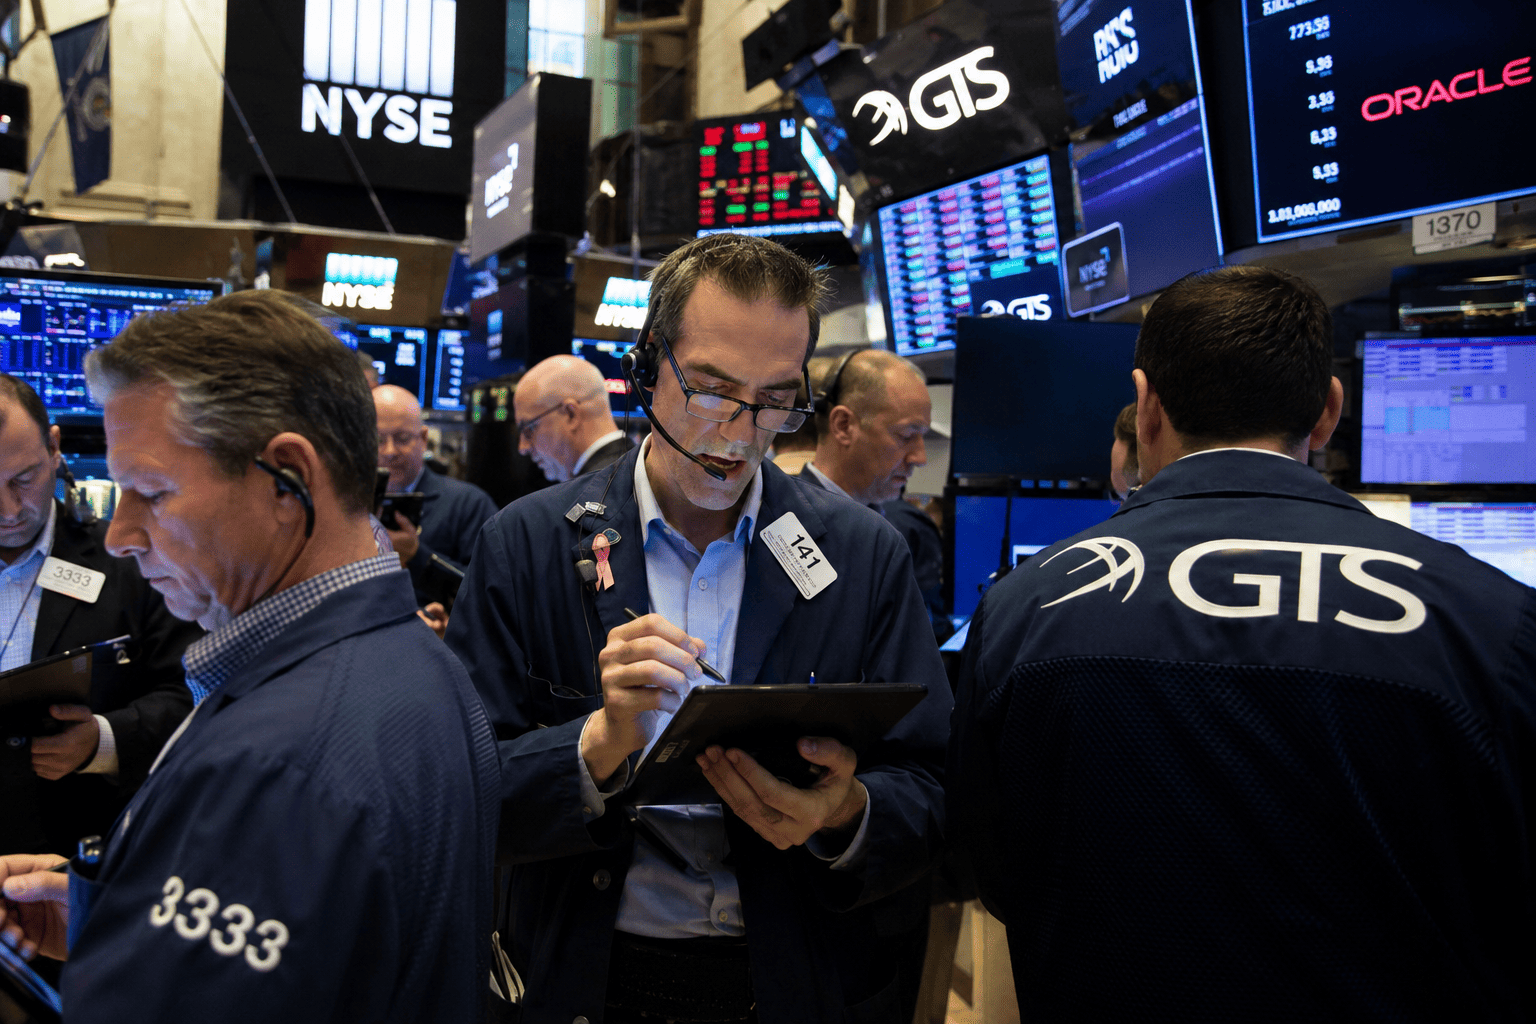
US equities finished Monday's session with a split performance, as rising crude prices and geopolitical concerns offset optimism ahead of a heavy week of corporate earnings and inflation reports. The Dow Jones Industrial Average advanced 198.22 points, or 0.38%, to close at 51,853.17, while the S&P 500 slipped 0.05% to 7,807.79. The Nasdaq Composite underperformed, dropping 0.44% to 27,246.
The mixed close followed a week of gains for all three major indexes, driven by technology shares and enthusiasm around artificial intelligence investments. However, Monday's trading saw a rotation away from tech, with the Philadelphia Semiconductor Index falling to a three-week low. Micron Technology dropped about 3% amid concerns over competition from China's ChangXin Memory Technologies, which reported progress on a new memory-chip structure.
In contrast, the Dow was supported by a 2% rise in Salesforce after Bank of America upgraded the stock to Buy from Underperform. Microsoft added 0.9% after announcing plans for a major deployment of its own AI chips, briefly pushing its market capitalisation above $4 trillion for the first time in a year. Energy stocks also outperformed as crude prices climbed.
Oil climbs on Middle East tensions
West Texas Intermediate crude futures rose 2.06% to settle at $93.74 a barrel, while Brent crude gained 1.84% to $106.65. The advance followed deadly attacks on Riyadh's international airport over the weekend, which heightened concerns about potential disruptions to global energy supplies. The gains overshadowed the prospect of additional Russian diesel supplies and a proposed Russia-Ukraine ceasefire covering energy infrastructure.
The rise in energy prices added to inflation worries, particularly as US Treasury yields have recently reached their highest levels in decades. The Treasury market was closed Monday for Columbus Day. Cleveland Federal Reserve President Beth Hammack indicated that the central bank should move relatively quickly towards a more restrictive monetary policy to address increasingly broad-based inflation pressures. Traders priced in less than a 22% probability of a Fed rate hike in October, according to CME's FedWatch tool, up from 17.7% on Friday.
Bank earnings and inflation data in focus
Investors are bracing for a busy week of corporate results, with major financial institutions including JPMorgan Chase, Goldman Sachs, Citigroup, Bank of America, Morgan Stanley and Wells Fargo scheduled to report earnings. Analysts expect strong third-quarter results, supported partly by continued investment in AI infrastructure. FactSet estimates cited by CNBC indicated that S&P 500 earnings growth could reach 29.6%, marking a fourth consecutive quarter of growth above 25%.
September consumer price index data is due Wednesday, followed by the producer price index and retail sales figures on Thursday. These reports could influence expectations for the Federal Reserve's next policy decision, particularly as rising energy prices complicate the inflation outlook. Investors will also assess whether corporate earnings can sustain the recent stock market rally amid geopolitical uncertainty and higher borrowing costs.
This article is for informational purposes only and does not constitute financial advice.

