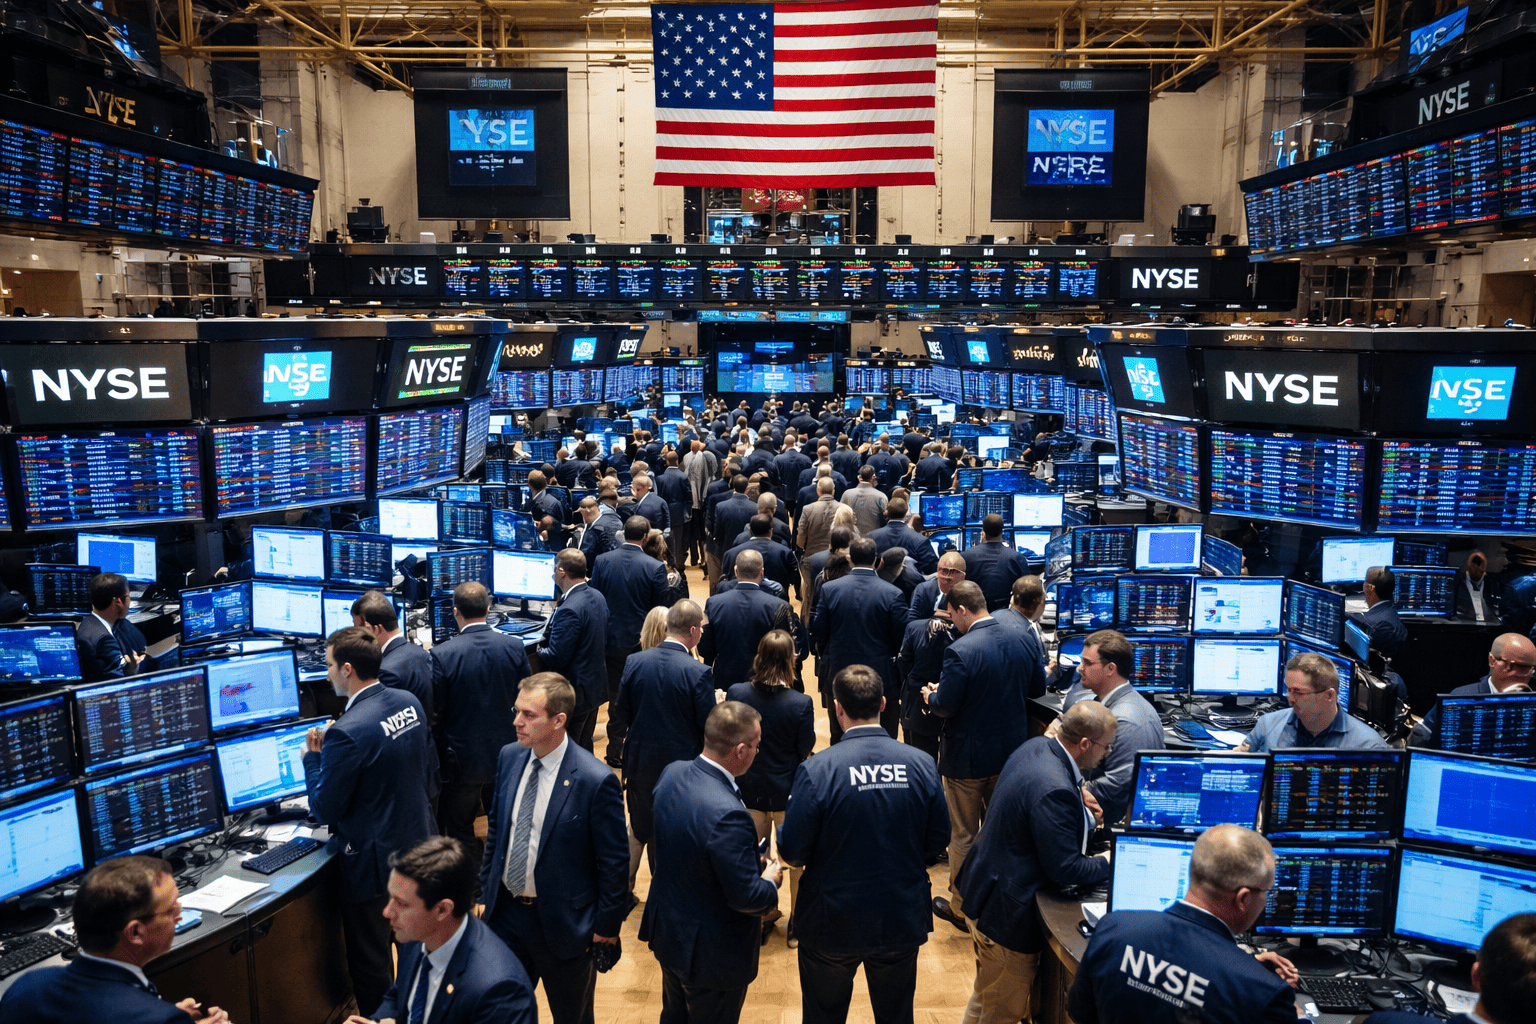
US equities opened lower on Thursday, with the Dow Jones Industrial Average shedding 127 points, as a renewed climb in oil prices and persistently elevated Treasury yields dampened risk appetite. The S&P 500 slipped 0.28%, while the Nasdaq Composite fell 0.48%, extending Wednesday's losses when all three major indexes closed in the red after yields reached multi-year highs.
Oil Surges on Middle East Supply Risks
Brent crude futures jumped about 4.2% to above $104 a barrel, while West Texas Intermediate rose roughly 4% to around $92, as concerns over Middle East supplies intensified following increased attacks on shipping in the Gulf and the Strait of Hormuz. The spike in energy prices adds to inflation worries, potentially complicating the Federal Reserve's efforts to bring inflation back to its 2% target.

Geopolitical tensions remain elevated, and the market is closely monitoring developments involving Iran and their potential impact on energy supplies. The sustained rise in oil prices has contributed to recent equity volatility, with investors fearing that prolonged energy inflation could keep interest rates higher for longer.
Treasury Yields Stay Near Multi-Year Highs
The bond market remained under pressure. The benchmark 10-year Treasury yield initially rose to 5.35%, close to its highest level since 2002, before easing seven basis points to 5.28%. The 30-year yield climbed more than five basis points to around 5.73%, a 24-year high, later dropping to 5.66%.
Higher yields weighed on interest-rate-sensitive sectors, with technology and bank stocks under pressure. Intel and AMD each fell 2% and 1.8%, respectively, while Bank of America and Citigroup declined around 1%.
Investors also assessed comments from Federal Reserve Governor Christopher Waller, who indicated that additional rate increases might be necessary to bring inflation down to the central bank's 2% target, while leaving flexibility on the pace of hikes. Markets broadly expect the Fed to hold rates steady at its October meeting, though a December increase remains possible.
Earnings Season in Focus
The latest market weakness comes as investors prepare for the third-quarter earnings season, which is expected to begin in earnest next week with major banks reporting. According to FactSet, the S&P 500 is expected to post quarterly earnings growth of around 30%, while LSEG data puts expected growth at 30.6%. Technology and energy companies are projected to deliver some of the strongest growth.
Strong earnings expectations have helped support US equities despite concerns over higher interest rates and geopolitical risks. Investors will be watching whether companies can meet or exceed forecasts as higher borrowing costs and energy prices create additional pressure.
Individual Stock Moves
Palantir Technologies was an exception to the broader weakness, with shares rising about 4% after Goldman Sachs upgraded the company, citing potential expansion in its addressable market driven partly by sovereign AI and bespoke applications. Wolfspeed shares surged 4.88% after receiving a $1.5 billion conditional loan commitment from the US Department of Defense. PepsiCo shares rose 0.8% despite the company cutting its annual core profit forecast and announcing additional cost reductions.
This article is for informational purposes only and does not constitute financial advice.

