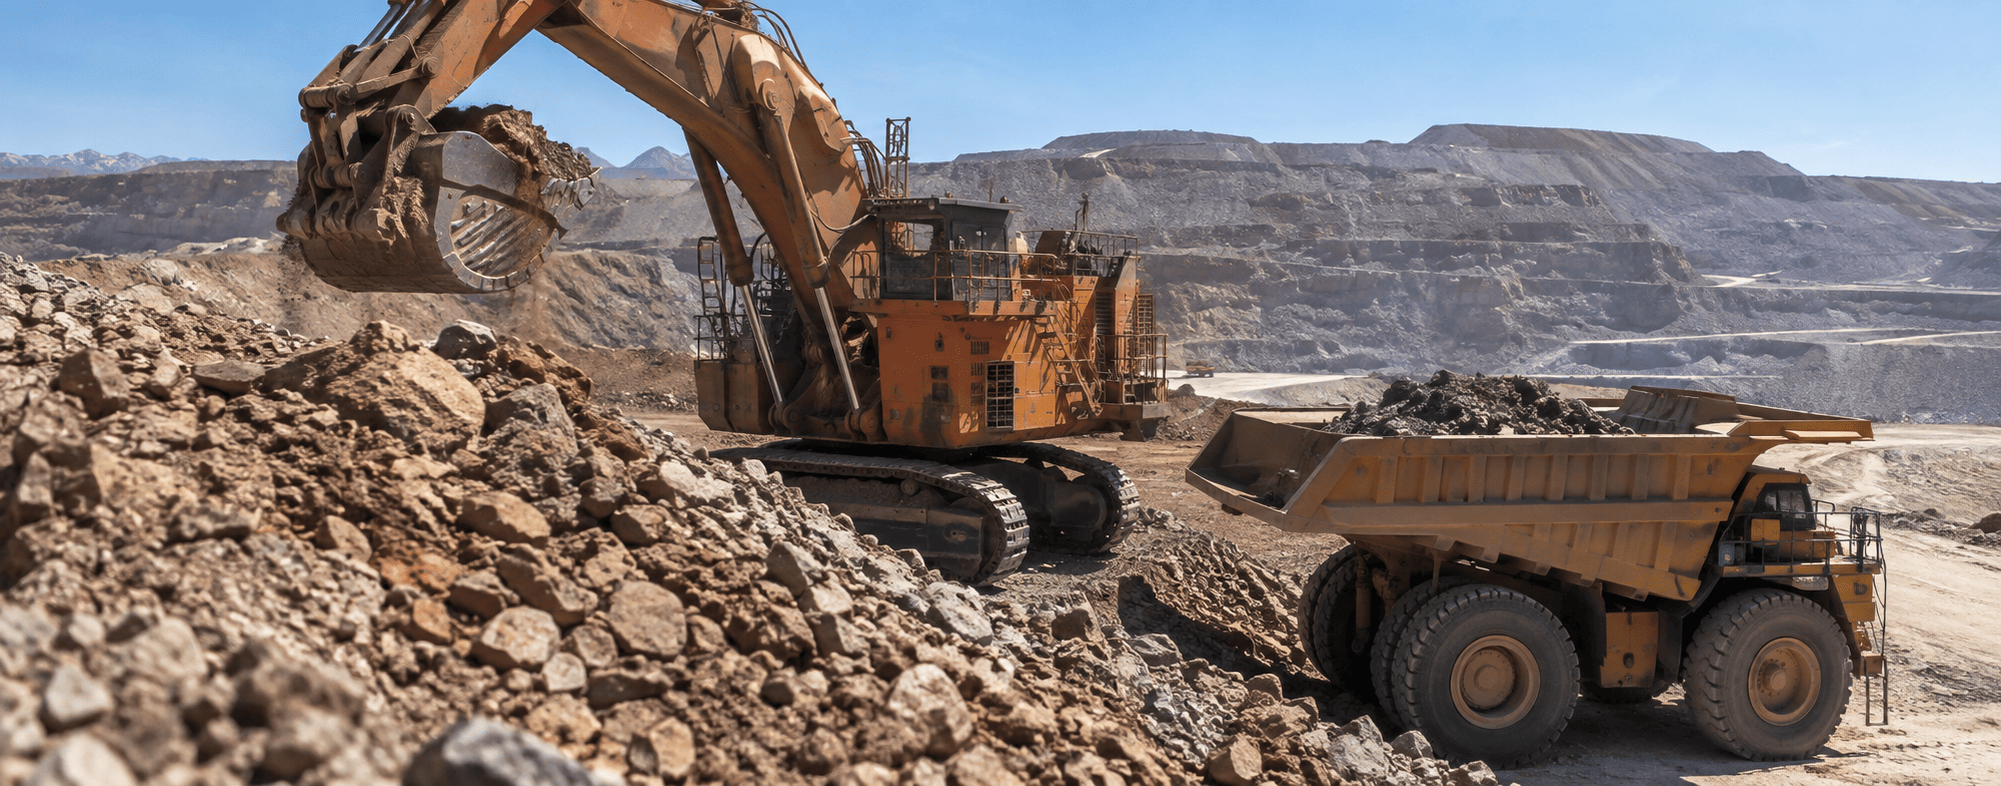
Deutsche Bank has issued a bullish forecast for copper, suggesting prices could climb to $10 per pound, or approximately $22,050 per metric ton. The investment firm attributes this potential surge to robust demand from artificial intelligence (AI) and electric vehicles (EVs), which it believes is only in its early stages. Such a move would represent a gain of more than 50% from the late September level of around $14,200 per metric ton, creating a significant tailwind for copper producers.
Among the companies positioned to benefit, Freeport-McMoRan (FCX) stands out due to its explicit copper price leverage. The company estimates that each 10-cent change in copper prices shifts its 2026 operating cash flow by approximately $300 million, which it projects at $8.3 billion assuming copper at $6 per pound. While second-quarter copper output fell 18% as Indonesia's Grasberg mine recovered from a September 2025 mud rush, management expects the district to reach nearly 65% of capacity in the second half and 80% by mid-2027, with a larger share of sales now anticipated in the final quarter. FCX also offers a dividend yield of about 0.83%, enhancing its appeal as a long-term holding.
Teck Resources (TECK) presents a bullish case driven by rising production volumes and declining unit costs. In the second quarter, copper production climbed 25% year-over-year to 135,900 metric tons, with every copper operation reporting higher output. Net cash unit costs fell to $1.64 per pound from $2.02. The Quebrada Blanca mine in Chile produced 55,800 tons, marking a third consecutive stable quarter, and management reaffirmed full-year guidance of 455,000 to 530,000 tons. Additionally, the Highland Valley extension is expected to sustain output of about 132,000 tons annually through 2046. TECK also pays a dividend yield of 0.54%, making it attractive for income-focused investors.
Southern Copper (SCCO) is already posting record profits despite shrinking copper volumes. Its second-quarter adjusted EBITDA reached $2.96 billion on sales of $4.3 billion, a margin near 69%, while copper production slipped to 230,662 metric tons as Peruvian output fell 12% due to lower ore grades. However, by-product credits of $2.24 per pound offset nearly all of the $2.29 per pound in operating cash costs before credits. Importantly, management raised its 2026 copper outlook to about 917,000 metric tons. Among the three stocks, SCCO offers the most lucrative dividend yield of 1.91% as of writing.
From a technical perspective, Southern Copper currently trades decisively above its key moving averages, with an RSI in the mid-50s indicating significant buying pressure that could drive its share price higher in the near term. This technical strength, combined with the fundamental outlook, makes SCCO a compelling play on the copper rally.
Deutsche Bank's forecast underscores the growing importance of copper in the global energy transition. AI data centers and EV production are intensive users of copper, and the bank expects this demand to outpace supply, pushing prices higher. For investors, these three miners offer direct exposure to this trend, each with distinct operational strengths and financial profiles.
While the outlook is optimistic, investors should consider the inherent risks, including operational disruptions, commodity price volatility, and broader economic conditions. The copper market remains sensitive to global growth expectations, and any slowdown could temper the projected demand surge.
This article is for informational purposes only and does not constitute financial advice.