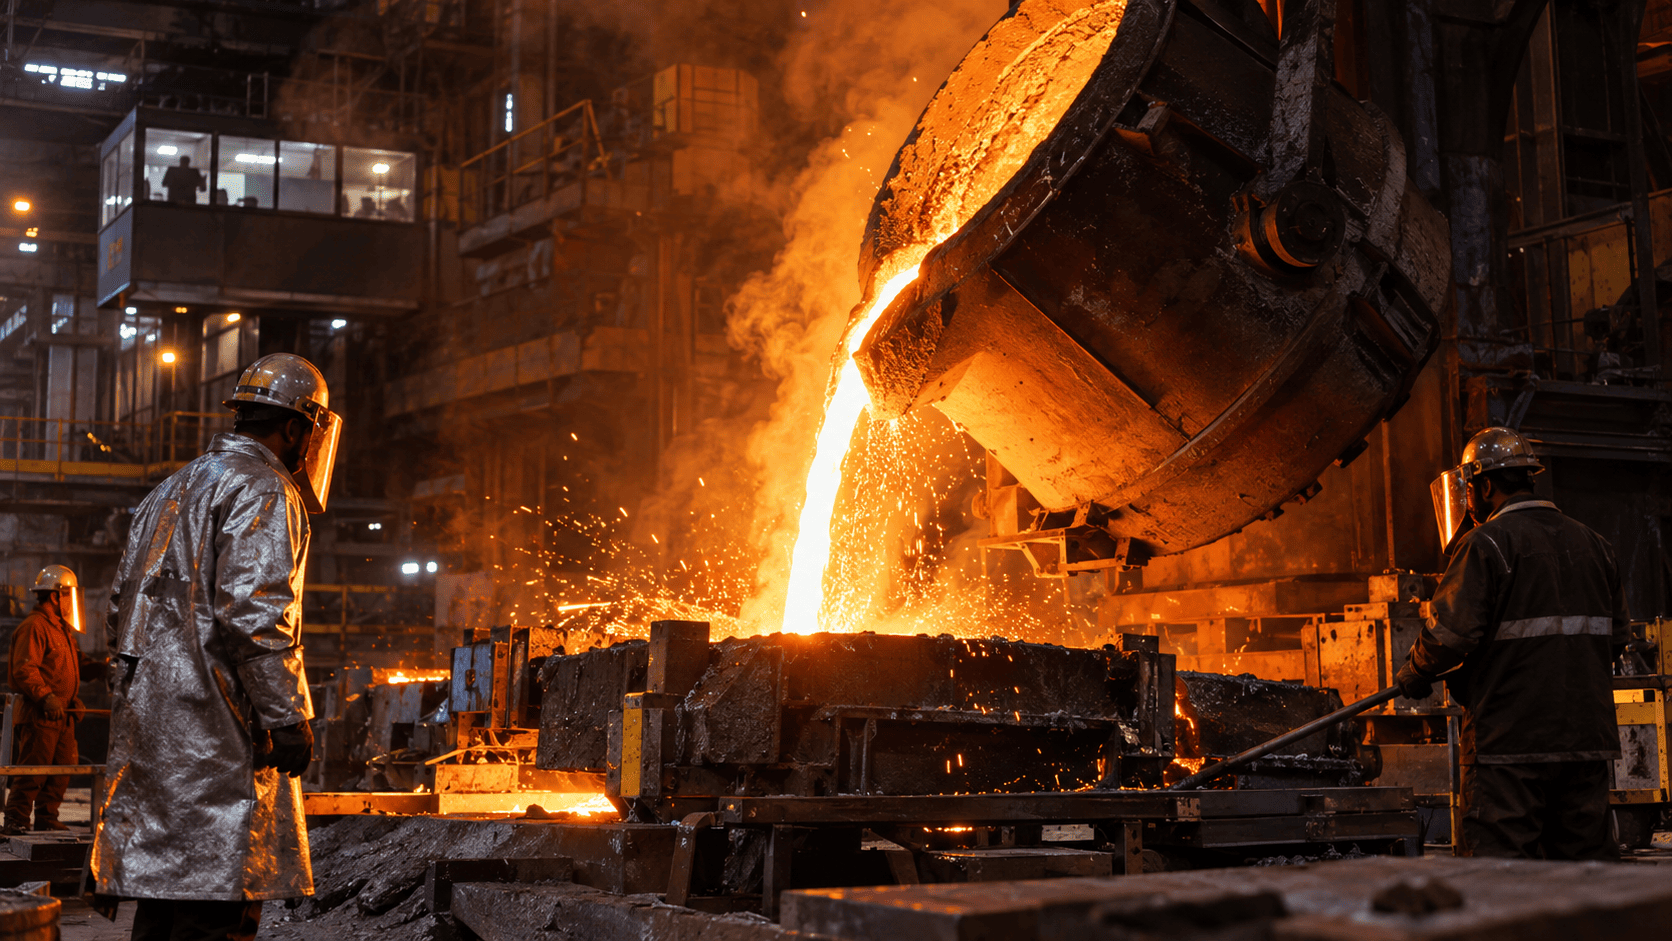
Cleveland-Cliffs (NYSE: CLF) shares advanced on Monday after the steelmaker reported a return to quarterly profitability and issued an earnings outlook that exceeded Wall Street's expectations. The stock broke above its 20-day moving average, a technical signal that near-term momentum has shifted in favor of buyers.
The primary catalyst was management's projection of more than $4 billion in adjusted EBITDA for 2027, well above the roughly $2.5 billion analysts had modeled. The company cited newly signed customer contracts and supportive steel-price assumptions, with U.S. tariffs helping to underpin domestic pricing.
Third-quarter results provided tangible evidence of improvement. Cleveland-Cliffs posted adjusted earnings of 28 cents per share, beating the 21-cent FactSet consensus. Revenue rose to $5.61 billion from $4.73 billion a year earlier, though it fell short of expectations. Higher selling prices and increased shipments drove the quarterly gains.
The question now is whether the earnings reset can support a sustained recovery in CLF shares or whether the market is pricing in too much improvement too quickly. Monday's jump does not automatically exhaust the upside, but it raises the bar for what comes next.
A stronger earnings outlook can justify a higher valuation only if the underlying assumptions prove durable. Management's 2027 projection depends partly on prevailing price forecasts. Signed contracts provide visibility, but they do not eliminate exposure to the steel cycle.
Cleveland-Cliffs also expects fourth-quarter pricing benefits to be partially offset by maintenance outages, seasonality, input costs, and incentive compensation. The operating recovery deserves attention, but an aggressive purchase immediately after a sharp rally leaves less room for disappointment.
The next decisive test is whether improving operations translate into a healthier balance sheet. CEO Lourenco Goncalves expects stronger fourth-quarter free cash flow and property-sale proceeds to support substantial debt reduction. Management remains focused on bringing net debt below 2.5x EBITDA by mid-2027. The company ended September with $3.2 billion in total liquidity.
For shareholders, the quality of that progress matters. Property disposals can accelerate repayments, but recurring cash generation would offer stronger evidence of lasting financial improvement. Lower borrowings could reduce financing pressure and give the company greater flexibility when industry conditions soften.
Investors now have a concrete way to judge whether Monday's enthusiasm is developing into a more durable investment case. The balance between cyclical risk and earnings momentum will determine if CLF stock has further upside left.
This article is for informational purposes only and does not constitute financial advice.