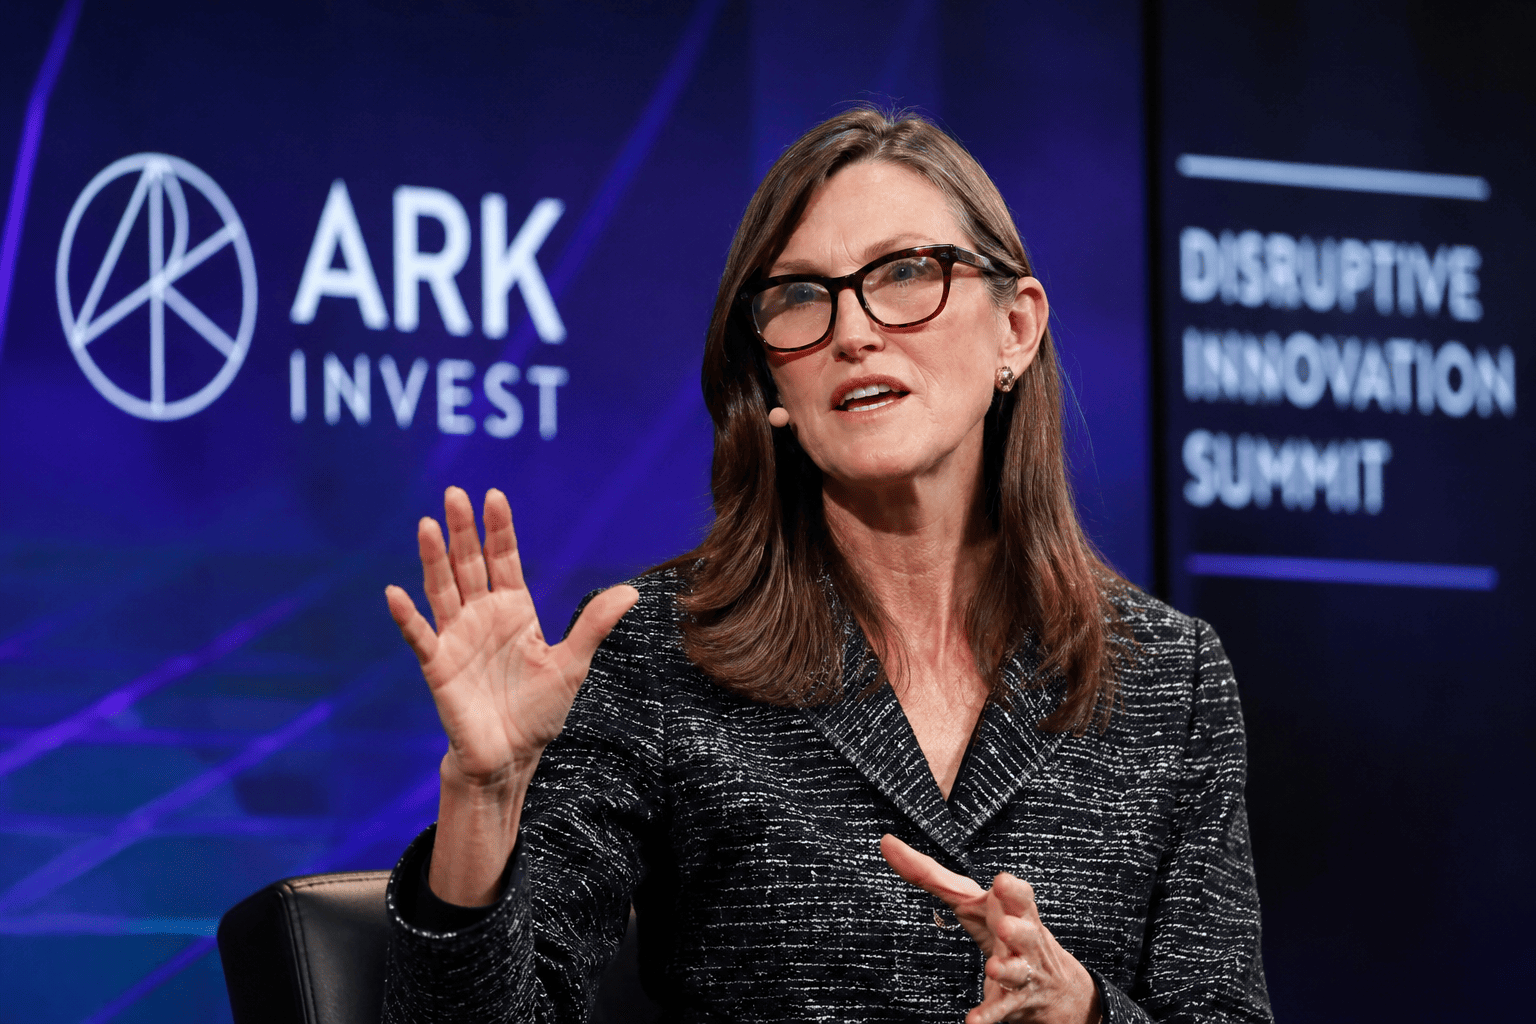
Archer Aviation (NYSE: ACHR) has seen its shares decline roughly 38% in 2026, yet Cathie Wood's ARK Invest is adding to positions. On October 6, ARK funds acquired about 2.57 million ACHR shares valued at $12.1 million, while simultaneously selling approximately $9.4 million of SpaceX stock from its ARKW fund.
At $4.65, Archer is trading near the bottom of its 52-week range, but TipRanks data shows a consensus price target of $11.60, implying about 149% upside. A broader set of nine analysts puts the average target near $10.61, though the range is wide: the lowest target is $4.50 (slight downside) and the highest is $18 (nearly 290% upside).

The bull case for Archer extends beyond passenger air taxis. During the company's earnings call, Cantor Fitzgerald analyst Andres Sheppard noted that Archer "no longer is an eVTOL company," describing it instead as an aerospace, defence, and advanced-air-mobility platform. Archer plans to acquire Boeing's Wisk Aero, Insitu, and SkyGrid businesses, adding autonomy, military drones, and airspace software. Insitu alone contributes more than $200 million in annual revenue.
Canaccord Genuity analyst Austin Moeller maintained a Buy rating and $12 target after the Boeing transaction, seeing Archer "evolving into a more defence tech-focused business." The firm raised its 2027 revenue estimate to $325.5 million from $124.5 million, reflecting expected contributions from defence and autonomous-aviation assets alongside the Midnight aircraft.
Archer is also developing Halo and Thunder autonomous aircraft and ZEE, an aviation-focused AI foundation model. Boeing is set to become a strategic shareholder and partner, broadening the company's addressable market.
Despite the optimistic outlook, execution risks loom large. Archer reported $5 million in second-quarter revenue, while adjusted EBITDA showed a $177.1 million loss. Operating expenses approached $280 million, and cash used in operations reached $156.4 million. Canaccord estimates quarterly free-cash use at roughly $194 million and projects an adjusted EBITDA loss of about $717 million for 2026.
Certification remains a central hurdle. Canaccord noted that Archer has not provided detailed timing for Phase 4 testing and analysis required for Midnight's airworthiness certification. This uncertainty helps explain the gap between bullish price targets and weak price momentum.
H.C. Wainwright analyst Amit Dayal reiterated a Buy rating and $18 target after the results, implying nearly 290% upside from current levels. However, the $4.50 low target serves as a counterweight, suggesting at least one Wall Street view sees little reason for the stock to trade materially higher until Archer proves more of its commercial story.
Investors are being asked to value businesses that could become large before the underlying programmes demonstrate they can scale commercially. Cathie Wood's purchase reflects a bet on the long-term potential of Archer's expanded aerospace and defence platform, but the stock's near-term trajectory will depend on execution and certification milestones.
This article is for informational purposes only and does not constitute financial advice.

