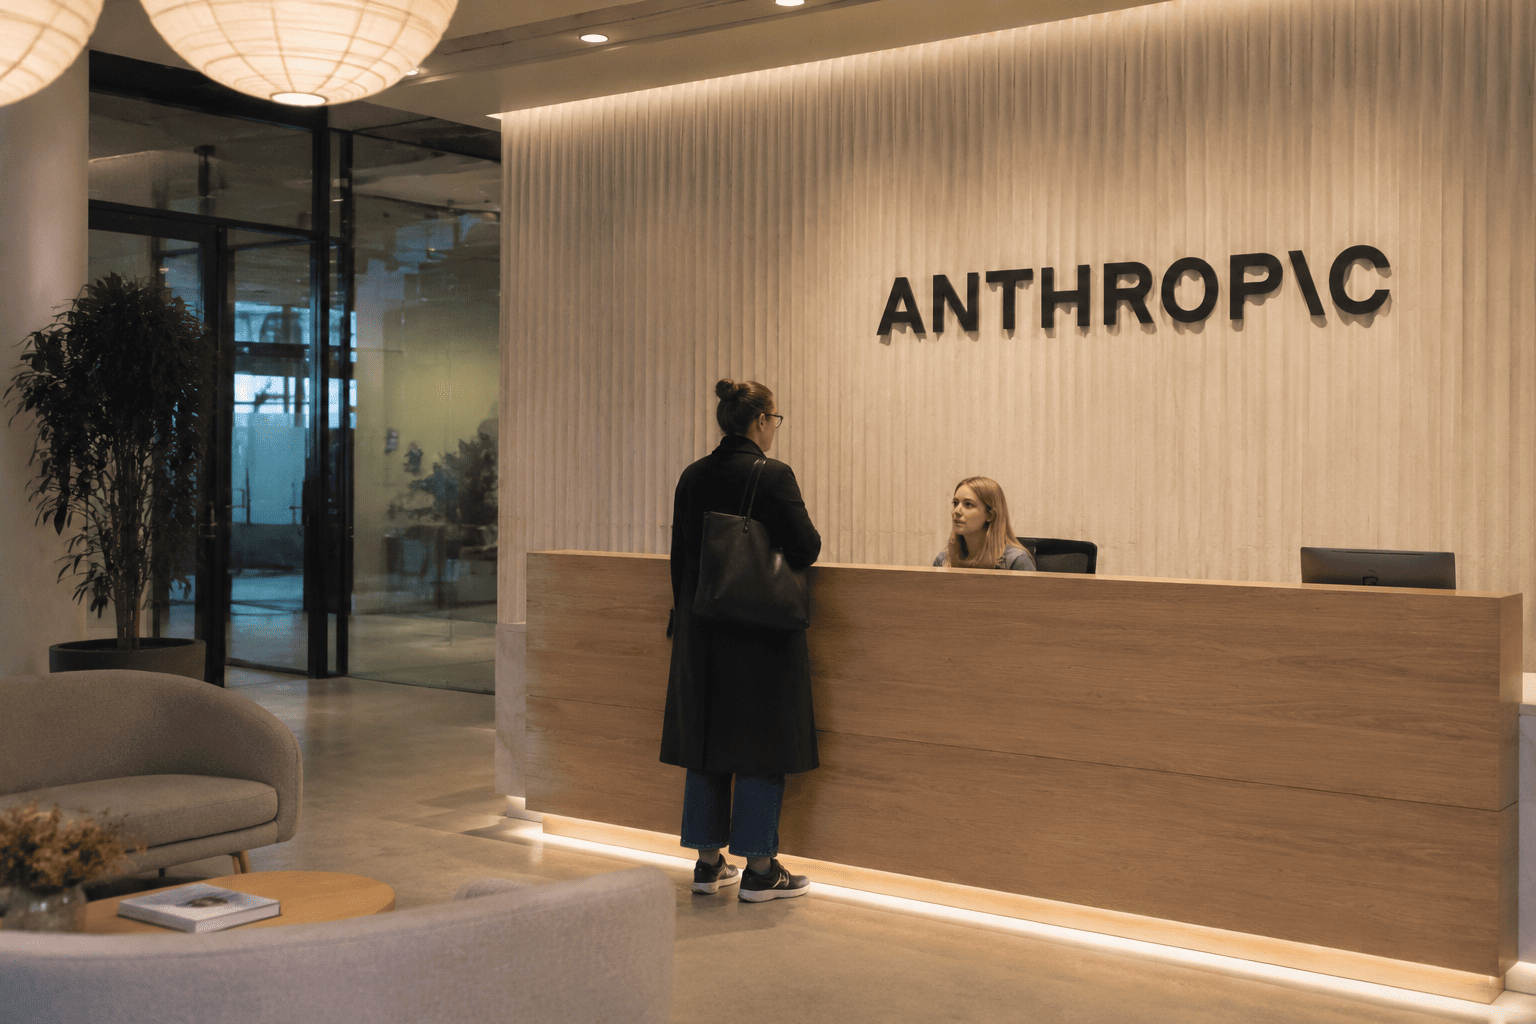
Anthropic is exploring an initial public offering that could launch as early as mid-November, according to Bloomberg News, which cited people familiar with the matter. The artificial intelligence developer may begin formal marketing in the week of Nov. 9, potentially allowing shares to trade before the Thanksgiving holiday. The company still aims to complete a listing by year-end, though the schedule remains subject to change.
Prospective investors have reportedly assigned a valuation of between $1.8 trillion and $2 trillion. That range would place the offering on par with or above the size of SpaceX's IPO, based on earlier Bloomberg reporting. The move comes as Anthropic faces intensifying competition from OpenAI and heightened regulatory attention on AI safety.

Financial disclosures show Anthropic recorded a net loss of nearly $42 billion in 2025, widening from about $8.3 billion in 2024. Revenue climbed to roughly $4.6 billion from $386 million. More than $34 billion of the 2025 loss stemmed from changes in the fair value of the company's liabilities.
Gold advances as rate-hike odds fall
Spot gold gained 0.49% to $4,176.16 an ounce, while US gold futures for December delivery settled 0.54% higher at $4,209.20. The metal had lost more than 6% in September. The rebound followed US inflation data for August that came in below expectations, with earlier price pressures revised downward.
Following the report, the market-implied probability of an October Federal Reserve rate hike dropped to 31%, down from 45% before the release and 69% a week earlier. Lower rate expectations typically support gold, but gains were capped by elevated Treasury yields and a firmer dollar. Investors now await the September nonfarm payrolls report for additional policy signals. HSBC cut its average gold price forecasts for 2026 and 2027 to $4,490 and $4,825 an ounce, respectively, while noting the metal may be approaching a bottom.
Oil rallies on supply disruptions
Crude prices jumped more than 4% a barrel as concerns over global fuel supplies intensified. December Brent futures settled at $102.46 a barrel, up 4.54%, while US West Texas Intermediate ended at $93.17, up 3.04%. China suspended oil product exports, adding strain to markets already affected by supply disruptions. Russia extended a diesel export ban through October, and damage to refinery infrastructure in the Gulf and Russia has contributed to tight refined-product supplies.
The US was also reportedly deploying a third aircraft carrier and up to 10,000 additional troops to the Middle East as President Donald Trump weighed options on Iran. The European Union's energy taskforce is set to discuss a potential release of diesel stockpiles. Saudi Arabia has resumed oil tanker loadings from Yanbu after restarting its East-West Pipeline.
Treasury yields ease from multi-decade highs
US Treasury yields pulled back after longer-dated rates reached their highest levels in more than two decades. The 10-year yield briefly exceeded a level last seen in April 2002 before easing more than four basis points to 5.234%. The 30-year yield also touched a 24-year high before falling to 5.60%. Higher oil prices and persistent inflation have fueled volatility in longer-dated yields, while investors assess government borrowing needs and fiscal deficits across major economies.
Japan's 10-year yield reached 3.126%, its highest since the mid-1990s, and Germany's 10-year yield topped 3.6%, its highest since 2008. France, Italy and the UK also recorded higher 10-year yields during the session before some rates retreated.
This article is for informational purposes only and does not constitute financial advice.

